
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Dividend Cut Require Action From Crown Castle (CCI) Investors?
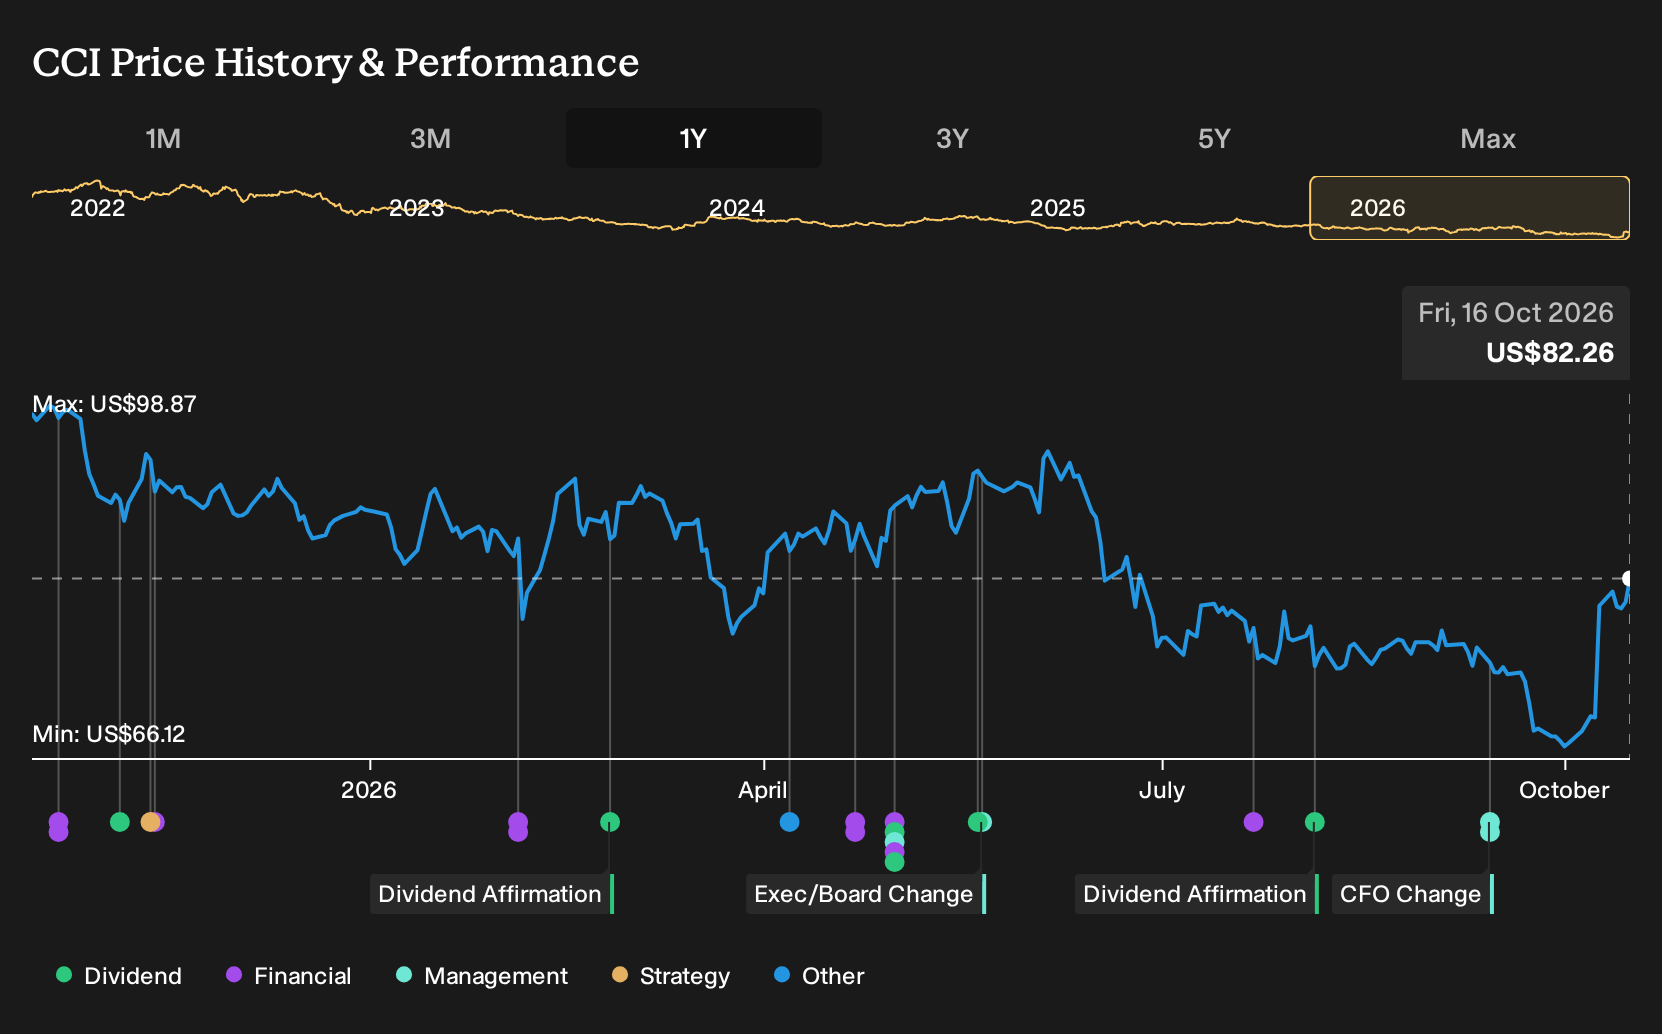
- Crown Castle reset its annual dividend from US$6.26 to US$4.75 per share after selling its fiber segment and shifting to a pure-play U.S. tower model, with management prioritizing debt reduction, ground lease buyouts, and focused tower investments.
- The business now carries a relatively high AFFO payout ratio and faces expected revenue pressure from DISH and Sprint churn, so the reset dividend and tighter capital spending give investors a clearer view of how tower cash flows support both income and balance sheet repair.
- This article examines how Crown Castle's dividend reset and tower-only focus change the longer term investment narrative for investors.
Crown Castle Investment Narrative Recap
Crown Castle appeals to shareholders who believe a focused U.S. tower portfolio can turn stable lease contracts into recurring cash flow while the firm works through churn from Sprint and DISH. The near term swing factor is how quickly lost revenue from those customers is absorbed by amendments and densification, especially with services activity already under pressure.
The dividend reset, high AFFO payout, and planned margin program make execution on cost control and ground lease buyouts the key short term watchpoints. Earnings expectations for the upcoming quarter matter mostly as a read on churn timing and services demand. Unless those trends break meaningfully, the core tower thesis remains largely intact.
The dividend cut from US$6.26 to US$4.75 per share is the announcement that ties this all together. That move redirected cash toward debt reduction, lease buyouts, and tighter tower capex while keeping a relatively high yield in place. For you, the question is whether this capital mix supports the tower only plan through the DISH and Sprint revenue headwind.
With interest costs not well covered by earnings and dividend coverage still thin, Crown Castle’s execution on the targeted 200 basis points of cash EBITDA margin improvement between 2026 and 2030 takes on more importance. Progress on that program, plus evidence that tower cash flows offset churn and softer services revenue, will likely frame how investors judge the reset payout over the next few years.
Crown Castle’s current analyst script points to revenues of US$4.3b and earnings of US$1.4b by 2029, built on forecast revenue growth of 1.3% a year, and an earnings increase of about US$300m from US$1.1b today.
Uncover why Crown Castle's fair value indicates a 15% potential upside to its current price. This opportunity could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight US$94.82 to about US$116.91 band, yet they still show that views on Crown Castle can swing meaningfully. You also have Sprint and DISH churn risk plus softer services demand in play, so explore multiple viewpoints before leaning on any single forecast.
Explore another Crown Castle fair value estimate, including one that suggests as much as 42% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Crown Castle research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Crown Castle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crown Castle's overall financial health at a glance.
Looking For More Ideas Beyond Crown Castle?
If you want to cross-check Crown Castle against other opportunities, use the Simply Wall St Screener to line up different income, quality, and risk profiles side by side.
- For investors who care most about resilience and downside protection, start with a group of companies flagged as having relatively lower risk using the 32 resilient stocks with low risk scores.
- If you want income that looks better supported by underlying cash flows, compare Crown Castle with other payout options by reviewing the 8 dividend fortresses.
- For those hunting for potential mispriced opportunities with solid fundamentals, broaden your watchlist by scanning our 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com