
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Johnson Electric Holdings (SEHK:179) Cuts Profit Outlook As Valuation Questions Grow
Johnson Electric Holdings (SEHK:179) has just pointed investors to a tougher earnings stretch. New guidance for the six months to 30 September 2026 highlights a sharp drop in expected profit.
The share price tells you how quickly sentiment has swung. Johnson Electric Holdings now trades at HK$13.22 after the stock fell about 57% on a year to date share price basis, even though the three year total shareholder return is still positive at about 43%.
Scan how other auto and robotics suppliers are priced against this kind of earnings pressure by running our curated list of 92 robotics and automation stocks alongside Johnson Electric Holdings.
After a 57% year to date slide and profit guidance pointing sharply lower, Johnson Electric Holdings now asks a blunt question: Does the lower price truly compensate you for the earnings hit when you weigh up valuation next?
Price-to-Earnings of 7.7x: Is it justified?
On current numbers, Johnson Electric Holdings trades on a P/E of 7.7x, which sits below several reference points and helps explain why some investors see value after the recent share price fall.
The P/E ratio compares what you pay today per share with the earnings that the business generates per share. For a manufacturer of motion systems that earns the bulk of its HK$3,650.4m revenue from auto parts and accessories, this measure provides a way to line up Johnson Electric Holdings against similar auto components groups where profits are a key focus.
Against direct peers, the gap is wide. Management is running the group on a lower P/E than the peer average of 11x and also beneath the Asian Auto Components industry average of 16.7x. The stock also trades below an estimated fair P/E of 9.3x. This comparison suggests that the current market multiple may be out of line with these reference points if sentiment or earnings expectations were to change.
Explore the SWS fair ratio for Johnson Electric Holdings.
Result: Price-to-Earnings of 7.7x (UNDERVALUED)
Still, the sharp earnings guidance cut and the reliance on a single Auto Parts & Accessories segment together raise the risk that Johnson Electric Holdings remains priced cautiously.
Find out about the key risks to this Johnson Electric Holdings narrative.
Another View: DCF Puts a Bigger Question Mark on Johnson Electric Holdings
A simple earnings multiple paints Johnson Electric Holdings as cheap. Our DCF model goes further, indicating the share price of HK$13.22 sits well below an estimated future cash flow value of HK$34.32, which implies a large valuation gap that investors need to judge carefully.
That kind of spread can signal opportunity or point to real concern about execution risk, balance sheet structure, or industry headwinds. The hard part is deciding whether this discount reflects temporary pressure or deeper issues in Johnson Electric Holdings' earnings power over time, and only you can make that call.
Look into how the SWS DCF model arrives at its fair value.
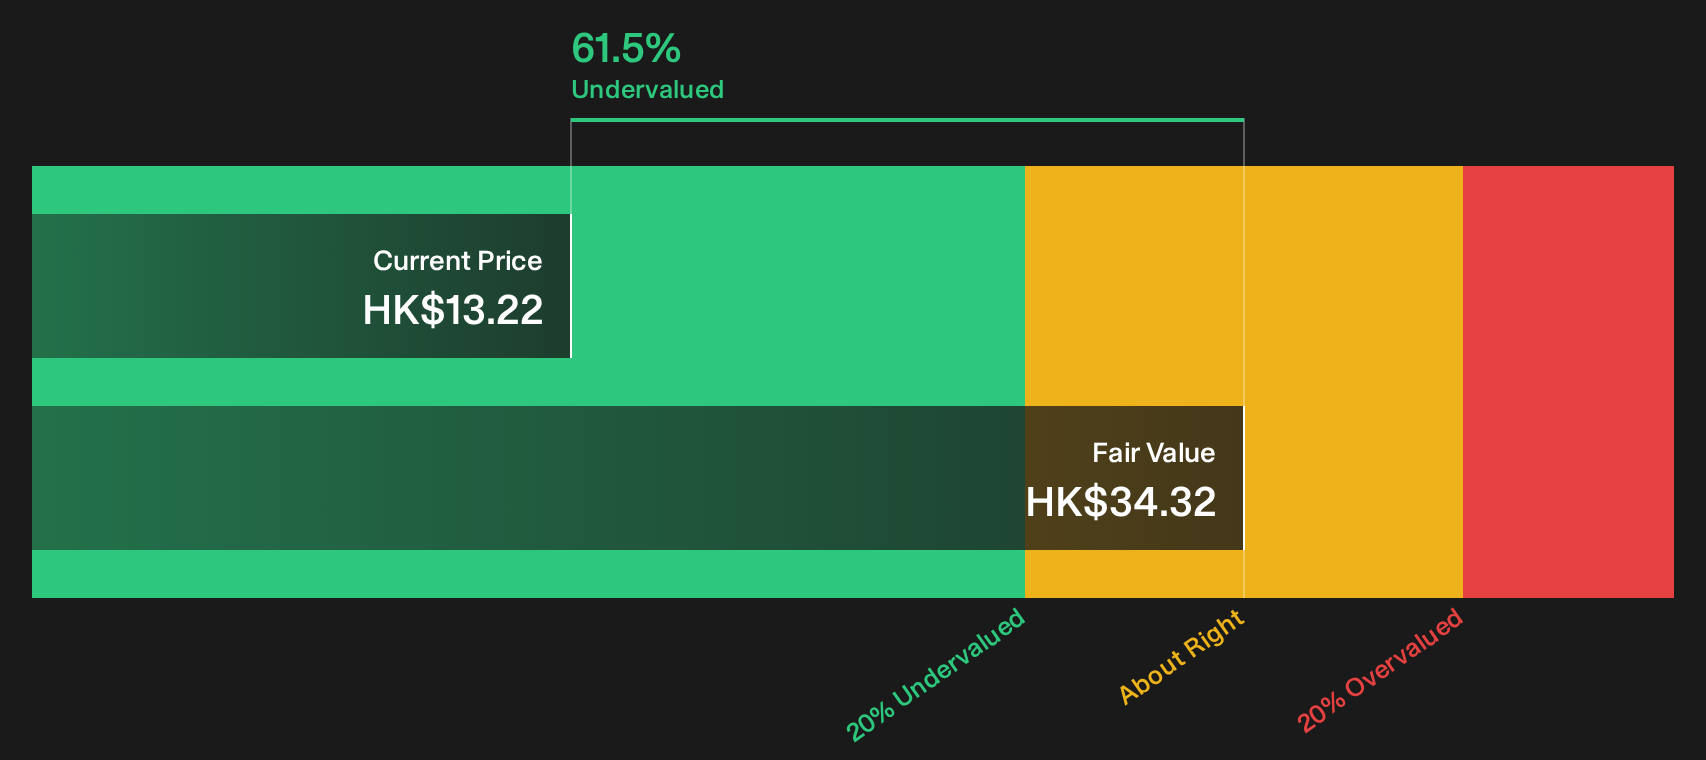
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Johnson Electric Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment in this piece has been cautious, and the clock is already ticking on fresh guidance and pricing. Move quickly, review the numbers yourself, weigh both sides of the story, and then check the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Johnson Electric Holdings?
You have already done the hard work on Johnson Electric Holdings. Do not stop there when a wider set of opportunities is only one smart filter away.
- Target stability first by scanning companies that appear on the 233 resilient stocks with low risk scores to see which businesses line up with your comfort level.
- Hunt for value by reviewing the 191 high quality undervalued stocks and compare those candidates with what you see in Johnson Electric Holdings.
- Prioritise resilience and financial strength with the list of solid balance sheet and fundamentals (203 results) so you are not relying on a single turnaround story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com