
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To VEON (VEON) Satellite To Mobile Launch
- VEON reported that its Bangladeshi operator Banglalink has launched a satellite-to-mobile service powered by Starlink, allowing users with a 4G phone and Banglalink SIM to access essential apps and location services in areas where traditional mobile coverage may be unavailable.
- This collaboration introduces satellite connectivity into VEON’s service mix in Bangladesh, which could influence future network investment choices, digital product design and cost structures across its emerging market portfolio.
- We will now assess how VEON's investment narrative could shift as satellite powered coverage extends Banglalink’s reach beyond conventional mobile networks.
Scan VEON's move into satellite-backed coverage against a wider peer set by reviewing the 41 power grid technology and infrastructure stocks.
VEON Investment Narrative Recap
To hold VEON, you need to believe its push into digital services in high population emerging markets can offset pressure on traditional telecom lines and justify its current P/E of 97.4x. The Starlink backed Banglalink service fits that digital thesis but is still small compared with group revenue of US$4.76b and net income of US$59m.
The more immediate swing factor is execution on growth while servicing US$4.63b of gross debt when interest payments are not well covered by earnings. Satellite coverage may support customer engagement and ARPU, but currency volatility, lower net margins at 1.2% and one off losses remain the bigger near term watchpoints.
There are no other fresh announcements tied directly to this launch, which puts the focus on how the satellite service supports VEON's existing digital app ecosystem. Access via MyBL, with RYZE to follow, plugs satellite connectivity into platforms that already host financial services, entertainment and lifestyle products.
For catalysts, the key question is whether this wider reach helps VEON add more high usage, multiplay customers without materially raising capital intensity. If uptake is limited or pricing pressure builds from rival connectivity options, the group could carry the complexity of a new technology layer without clear relief for earnings, leverage or its still thin profit margin.
Analysts frame VEON's narrative around revenues of US$6.2b and earnings of US$730.9m by 2029, which implies 9.2% yearly top line growth and an earnings increase of about US$672m from current earnings of US$59.0m.
Uncover why VEON's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
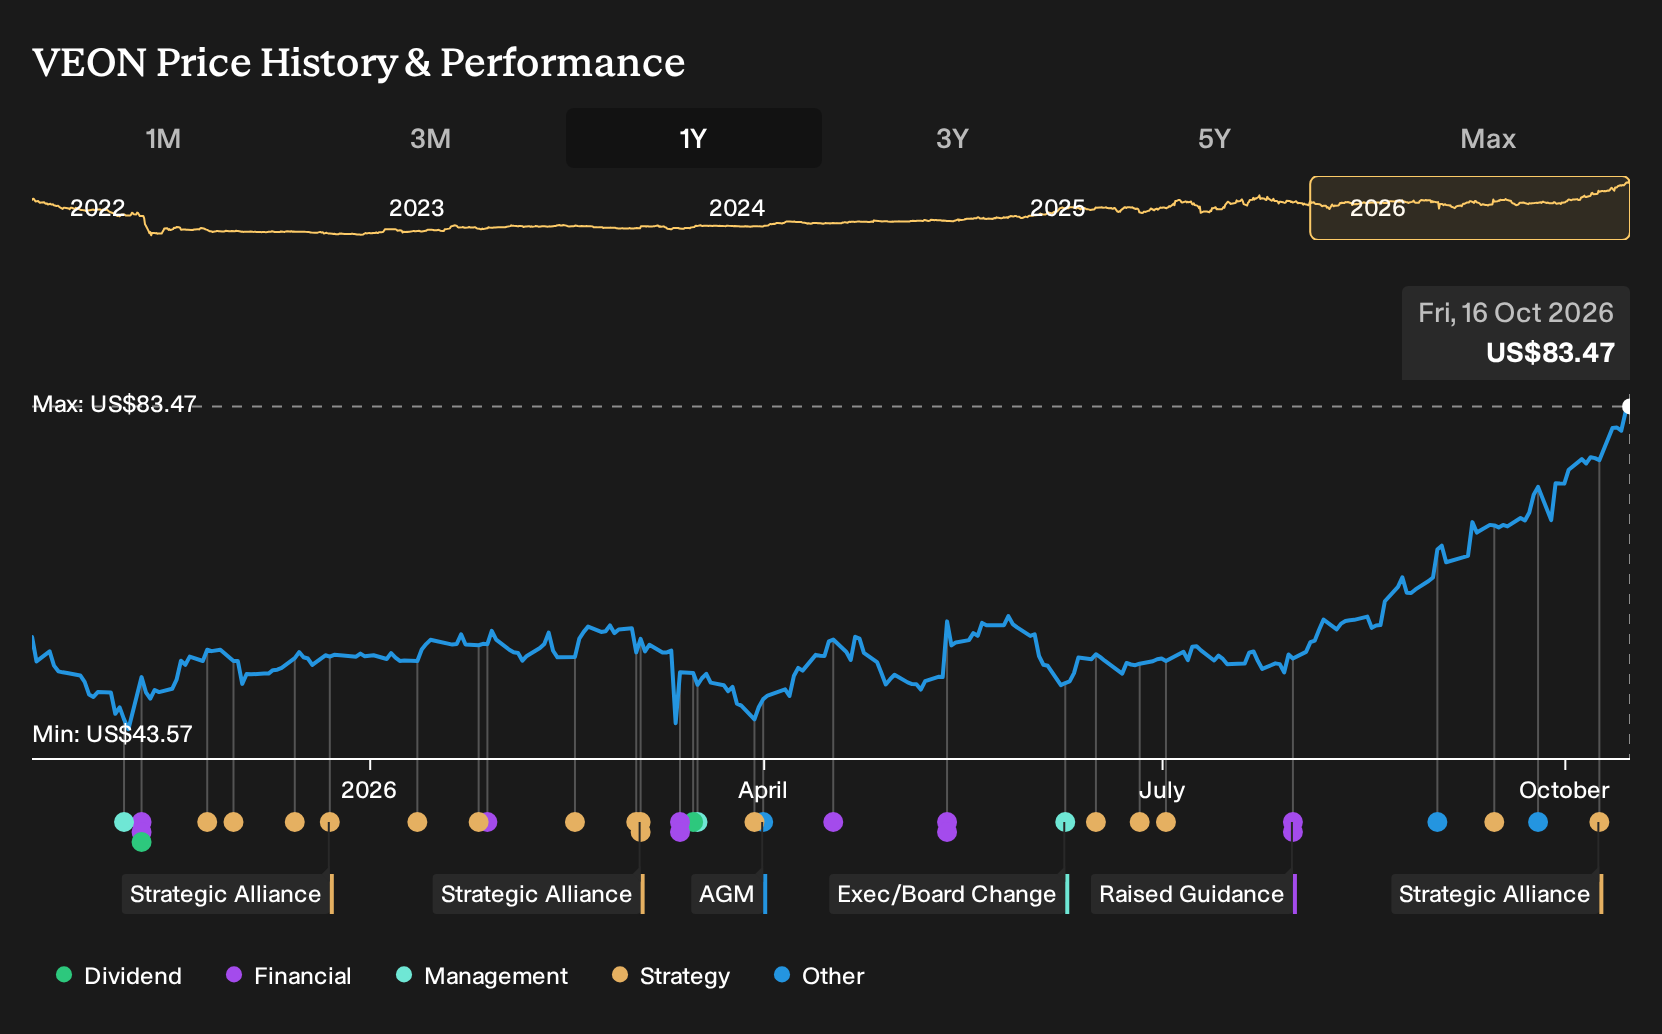
Exploring Other Perspectives
One bullish angle you might want to weigh against the baseline is the idea that VEON’s planned digital bank and payments rollout in Bangladesh could be the real earnings swing factor, not satellite coverage. The most optimistic analysts were already pencilling in US$6.6b of revenue and US$897.5m of earnings by 2029 before this Starlink news, so expectations vary widely and may shift again as the story evolves.
Explore 4 other VEON fair value estimates, including one that suggests as much as 591% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your VEON research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for VEON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VEON's overall financial health at a glance.
Looking For More Ideas Beyond VEON?
If VEON has sharpened your focus on risk, growth and balance sheet strength, it can help to line it up against other opportunities using a consistent framework.
- If you want potential upside but still care about financial resilience, start with a 20 high quality undiscovered gems that already show strong underlying fundamentals.
- If capital preservation sits higher on your priority list, compare VEON with a 32 resilient stocks with low risk scores that score well on stability and risk metrics.
- If rock solid finances matter most to you, broaden your watchlist with a list of solid balance sheet and fundamentals (25 results) that pair healthier balance sheets with robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com