
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Top Trust Ranking Change The Bull Case For Cochlear (ASX:COH)?
- Cochlear was recently ranked No. 1 in Newsweek's World's Most Trustworthy Companies 2026 for Health Care & Life Sciences, reflecting strong trust from customers, investors, and employees.
- The repeat recognition underscores how Cochlear’s recipient-first culture and focus on quality and safety sit at the center of its operating reality.
- We will now assess how Cochlear's top trust ranking could influence the existing investment narrative around product leadership and margins.
Scan how Cochlear's trust driven model compares with other high quality businesses by reviewing our hand picked 6 resilient stocks with low risk scores that aim to pair resilience with disciplined fundamentals.
Cochlear Investment Narrative Recap
To own Cochlear, you need to believe that its implantable hearing ecosystem, from surgery through upgrades and connected care, can keep pulling more patients into treatment and keep them engaged for years. The Newsweek trust ranking mainly reinforces that thesis. It may help with surgeon confidence and payer discussions, but it does not materially change near term demand or pricing pressure on its own.
The more immediate swing factors still sit elsewhere. The key catalyst is successful commercial rollout of systems like Nexa and reacceleration of upgrade volumes, especially in the U.S. The biggest risk remains margin pressure from lower tier pricing in China, slower implant uptake in Western Europe and high fixed costs tied to R&D and transformation projects.
Among recent developments, the Nexa cochlear implant system stands out as most relevant to this trust recognition. A smart implant with clear differentiation fits tightly with a recipient first culture and could matter for surgeons who already see Cochlear as a safe operational partner. That combination of perceived reliability and product capability often shapes which devices get recommended in practice.
For investors watching catalysts, Nexa is central. Execution on pricing, training and postoperative support will influence whether expected gains in average selling prices and share in developed markets actually show up in reported numbers. Any hiccups in manufacturing expansion or regulatory processes, including Chengdu, could weigh on the upside that a trusted, higher end platform like Nexa is aiming to capture.
Cochlear trust narrative versus the numbers
Cochlear's narrative projects A$2.7b revenue and A$418.9m earnings by 2029. This assumes 4.5% yearly revenue growth and an earnings increase of about A$271.6m from A$147.3m today.
Uncover why Cochlear's fair value indicates a 7% potential upside to its current price that could narrow quickly.
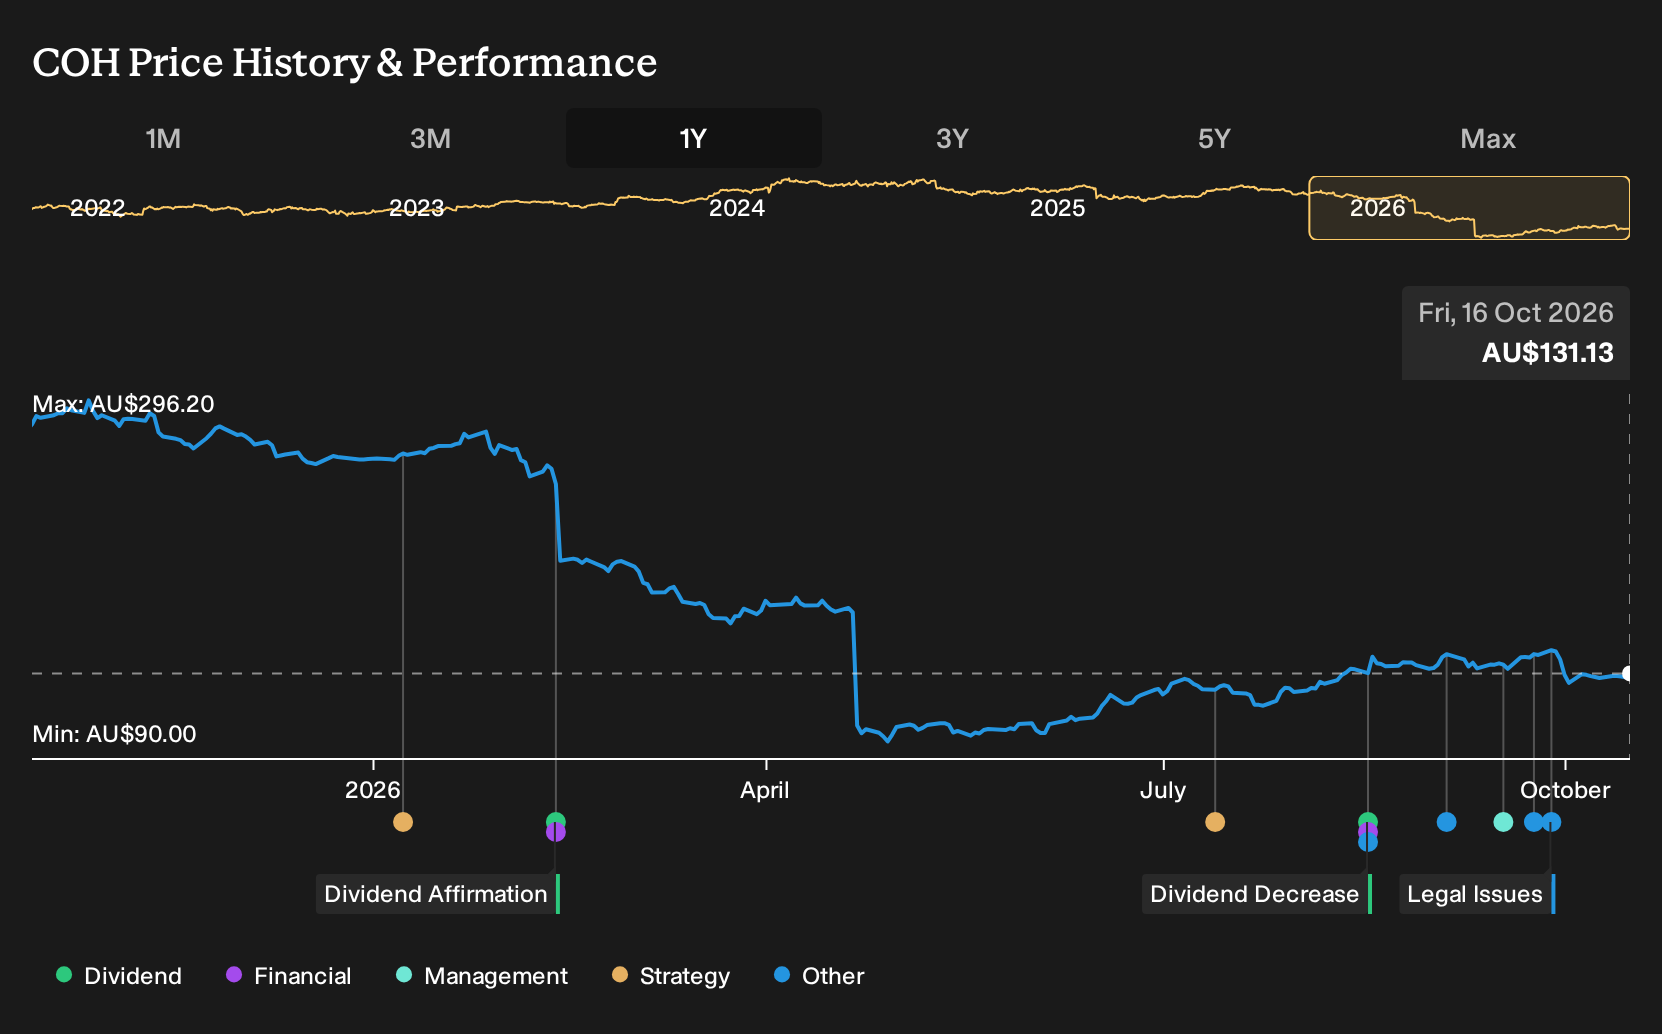
Exploring Other Perspectives
Some of the most optimistic analysts lean into Nexa as the real swing factor for Cochlear rather than trust rankings. They were already modeling revenue of about A$2.8b and earnings near A$476.4m by 2029, compared with the A$2.7b and A$418.9m consensus view. You now get to ask whether this new trust signal nudges those narratives higher or lower.
Explore 6 other Cochlear fair value estimates, including one that suggests potential upside of as much as 72% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view based on thorough research.
- A great starting point for your Cochlear research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cochlear. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Cochlear's overall financial health at a glance.
Looking for more Cochlear style investment ideas?
If the Cochlear story has sharpened what you look for in a business, use that same lens to filter other opportunities with the Simply Wall St Screener. Focus on balance sheet strength, income potential or underappreciated quality, then build a shortlist that actually fits your risk tolerance and goals.
- For resilient businesses that aim to cushion portfolio swings, start with a 6 resilient stocks with low risk scores that prioritise stability over drama.
- If reliable income is more your thing, scan a curated 4 dividend fortresses that focus on higher yields backed by solid fundamentals.
- When you want mispriced quality, sift through a 15 high quality undiscovered gems that highlight companies the market may not be paying full attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com