
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Fabrinet (FN) Stock Could Trade At A 12% Discount To Cash Flow
Fabrinet has been through a sharp swing, with a multiyear climb now giving way to a pullback, so the key issue is how today’s share price lines up with the cash the business can generate over time. After such a shift in sentiment, the question is whether the recent price still makes sense when you focus only on its cash flows.
- Over the past 5 years, Fabrinet has delivered a return of 277.1%, which puts a lot of weight on whether those gains are grounded in sustainable cash generation.
- The company’s role as a contract manufacturer in optical and advanced technology hardware means its ability to convert customer demand into steady free cash flow may support or constrain what investors are willing to pay for the stock.
- If you'd rather focus on earnings, this one's for you. See what Fabrinet's 27.5x P/E says about the price.
The stock’s next move may depend on whether Fabrinet’s current price can be explained by the intrinsic value suggested by its cash flows.
If you are weighing Fabrinet through the lens of its cash flows, it can help to compare these metrics with a broader set of companies that have been screened on similar valuation and quality cues using 33 high quality undervalued stocks
Is Fabrinet Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model values Fabrinet by weighing the cash it is expected to produce for shareholders against today’s price. Fabrinet generated trailing twelve month free cash flow of about $77.0 million, which sits well below the analyst based projections that build toward higher annual cash generation over the coming decade. The forecast path assumes a growing stream of free cash flow rather than a one off spike, then tapers that growth as the business matures.
Those projections feed into a two stage DCF that points to an intrinsic value modestly above the current share price of $363.51. The gap reflects the model’s view that Fabrinet’s expected cash flows, once discounted back to today, support a valuation slightly richer than what the market is currently assigning. That leaves investors weighing how comfortable they are with the implied long term growth in free cash flow that underpins this outcome, and whether the current price already reflects enough of that potential. Find out what Fabrinet could be worth using our Discounted Cash Flow (DCF) estimate.
The Fabrinet Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take Fabrinet’s valuation puzzle and spell out which paths for growth, margins and earnings would need to hold for the shares to be worth materially more or less than today’s price, and they sit on the stock’s Community page. Each narrative links a specific fair value to a clear story about Fabrinet’s possible catalysts and setbacks, so you can track over time which version is actually unfolding.
One of the top community narratives on Fabrinet: 49% undervalued
"The current narrative suggests Fabrinet’s share price may not fully reflect the earnings power indicated by its AI related data center activity…"
Discover why this Narrative puts Fabrinet at 49% undervalued.
One more Fabrinet signal worth checking before you move on
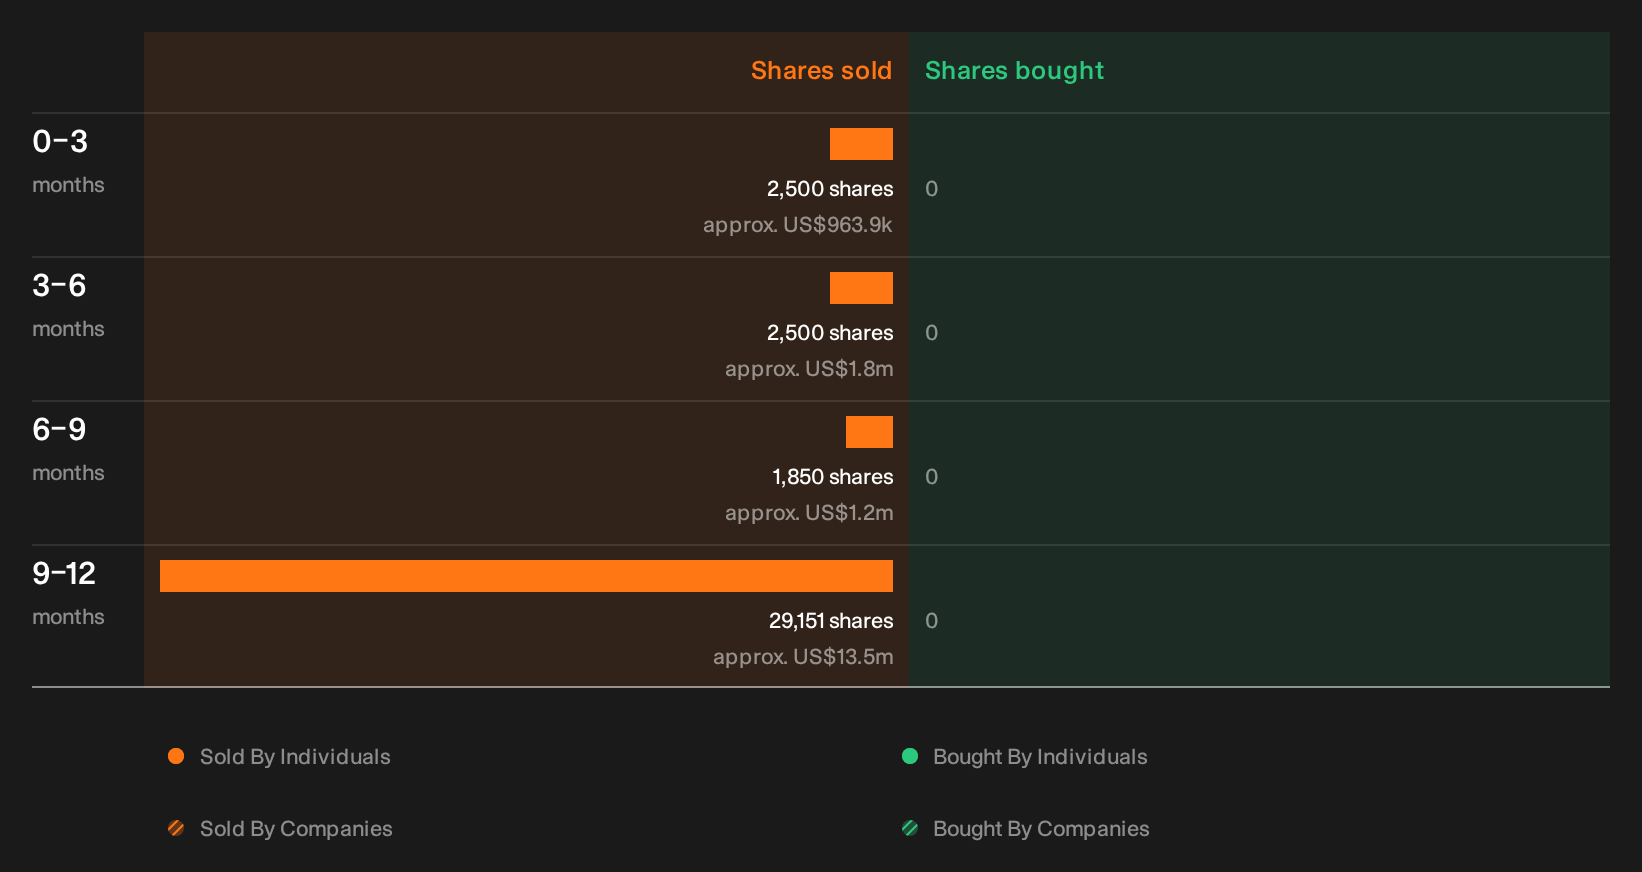
Cash flows tell one story for Fabrinet, but the trading decisions of its own leaders tell another, and recent share disposals flagged by our checks leave the sellers, sizes and possible read throughs for you to unpack. See the recent insider selling flagged for Fabrinet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com