
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 AI Infrastructure Stocks Retail Investors Are Watching For Data Center Growth
Artificial intelligence is turning from a buzzword into a construction project, with trillions of dollars earmarked for data centers, chips, and power gear, and that buildout is reshaping which stocks carry the most risk and potential reward. Miss this wave and you could miss where a lot of capital is quietly migrating. This article focuses on 3 stocks from our AI Infrastructure Enablers screener that appear especially exposed to this trend, and explains what that could mean for your portfolio.
The stocks featured below are just a sample, and the full screen surfaced 49 more large AI infrastructure enablers with equally compelling stories that are not covered here. To move from ideas to your own shortlist, head straight into the AI Infrastructure Enablers (Data Centers, Semiconductors, and Power Equipment) screener to identify, filter, and analyze the highest conviction plays for your style.
Eugene TechnologyLtd (KOSDAQ:A084370)
Overview: Eugene TechnologyLtd supplies semiconductor manufacturing equipment and related services, directly linking its thermal and plasma tools to AI chip fabrication demand.
Operations: Eugene TechnologyLtd generates about ₩371,093 million from semiconductor equipment and ₩15,137 million from industrial gases, with roughly ₩269,039 million from South Korea and ₩117,192 million overseas.
Market Cap: ₩2,925.4 billion
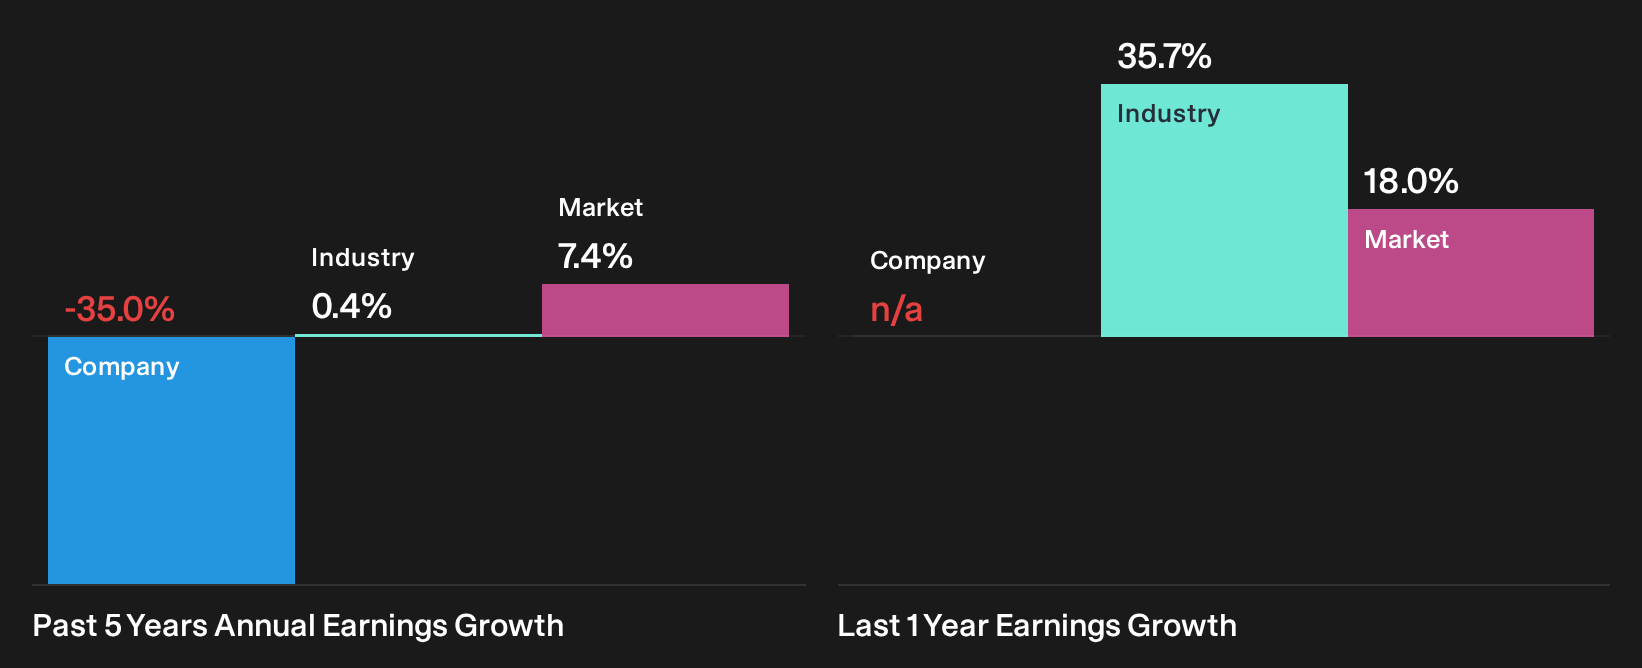
Eugene TechnologyLtd builds core tools such as LPCVD, ALD and plasma systems that chip fabs use to expand AI compute capacity. The link to AI data center spending is clear, and future profitability depends on how one less visible pressure shapes the real cash behind the company’s reported margins.
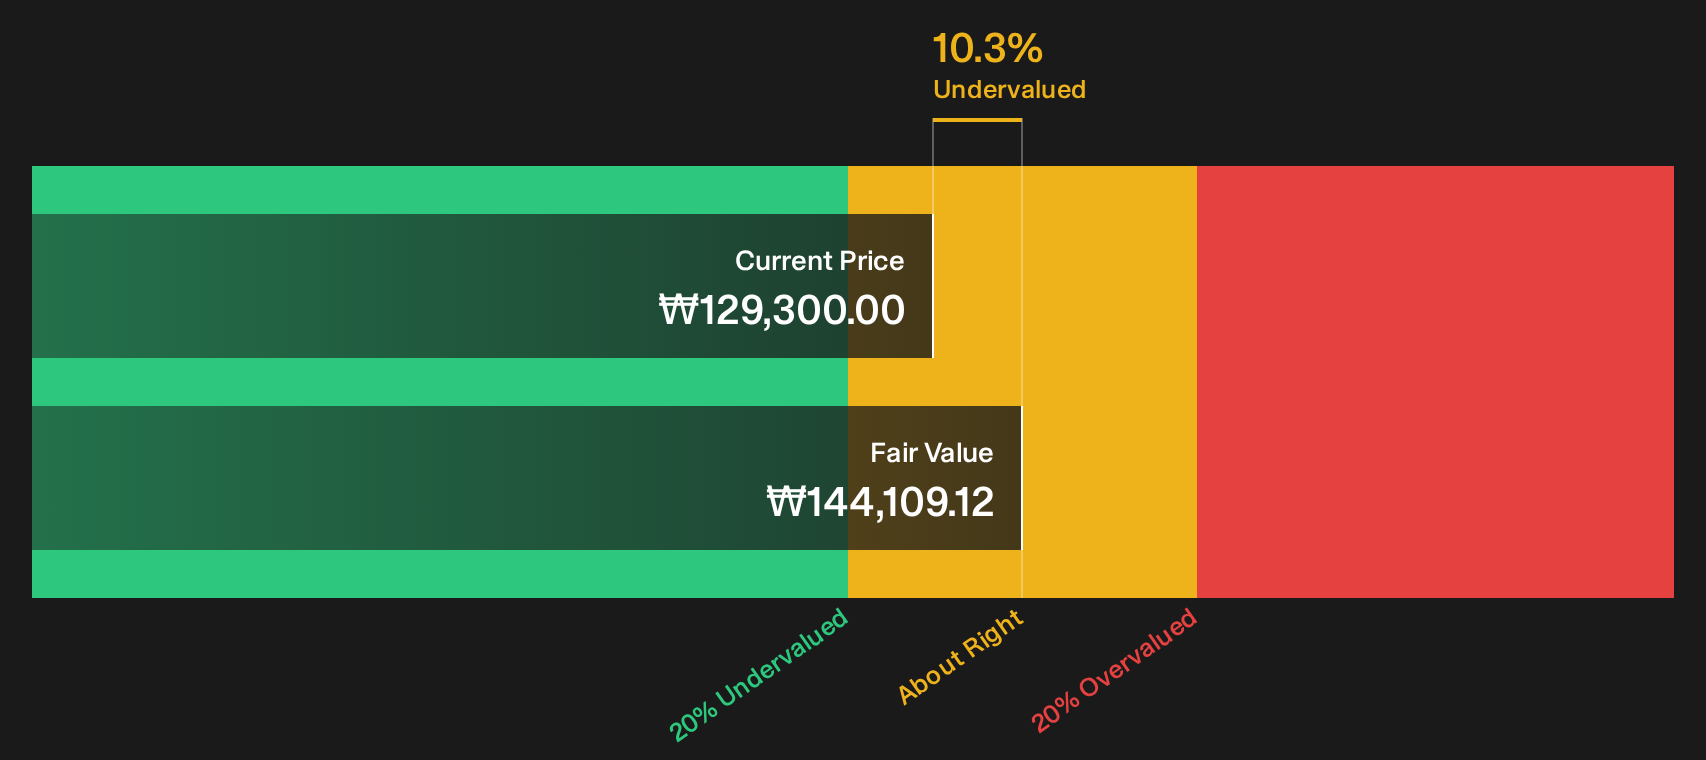
That pressure on real cash returns is exactly why many investors study the DCF valuation analysis for Eugene TechnologyLtd to see whether Eugene TechnologyLtd’s AI exposure is already fully priced in.
Delta Electronics (TWSE:2308)
Overview: Delta Electronics supplies power and thermal management hardware that keeps AI data centers, high density servers, and critical infrastructure running efficiently.
Operations: Delta Electronics generates NT$337,932 million from Power Supply and Spare Parts, NT$226,211 million from Infrastructure, NT$57,611 million from Automation, and NT$31,676 million from Transportation.
Market Cap: NT$4,246.98 billion
Delta Electronics matters in this AI Infrastructure Enablers theme because it sells the electrical and cooling backbone that keeps AI data centers online and within temperature limits when server racks are working at full tilt.
"Sustained investment in AI and data center infrastructure by hyperscalers continues to support strong demand for Delta Electronics server power products and cooling solutions, which recently accounted for a combined share of more than 30% of revenue. The shift from selling individual components toward integrated liquid cooling systems and upcoming high voltage DC power rack offerings extends Delta Electronics' role in the data center stack beyond its traditional base."
What happens to Delta Electronics margins and earnings power depends heavily on how that quiet shift in product mix ultimately plays out.
That shift in mix is exactly what makes the full narrative for Delta Electronics worth a closer read, revealing how AI demand, pricing power, and execution could be decoupling under the surface.

Allegro MicroSystems (ALGM)
Overview: Allegro MicroSystems designs sensor and power management ICs that help manage power, motion control, and cooling inside AI data centers and industrial systems.
Operations: Allegro MicroSystems generates about US$945.9 million from designing, producing, and distributing integrated circuits, with sales spread across Asia, Europe, and the Americas.
Market Cap: US$6.0b
Allegro MicroSystems matters to this AI infrastructure group because its sensors and power ICs sit where rising rack power and cooling demands are turning into real component orders.
"Ongoing investments and recent improvements in Allegro MicroSystems' manufacturing and cost structure, including gross margin of 51.1% in first quarter fiscal 2027 versus 48.2% a year earlier, continued factory efficiency work, bill of material transitions such as gold to copper wire bonding, and selective price actions expected to be more impactful in the back half of fiscal 2027, give the company tangible levers to pursue its stated target of 55% gross margin and beyond."
What happens if a single cost lever or mix shift quietly prevents Allegro MicroSystems from translating rising AI data center demand into lasting margin gains?
When that margin story looks fragile, the full narrative for Allegro MicroSystems shows how Allegro MicroSystems’ AI leverage, capital choices, and risk gaps could be accelerating or quietly stalling the thesis.
Seeking Fresh Alternatives Beyond AI?
Fresh ideas move first, and late entries often chase after the breakout. Scan curated screeners while the momentum is under the radar for now and get in early.
- Target steady portfolio anchors by reviewing a curated 213 dividend fortresses that focuses on income while prices still look reasonable and yields have not been crowded yet.
- Hunt for mispriced quality using the hand picked 192 high quality undervalued stocks before more investors catch on and potential valuation gaps start narrowing.
- Track the next automation wave through a focused 92 robotics and automation stocks that highlights businesses building real traction before headlines send volumes higher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com