
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Order Surge Require Action From Oxford Instruments (LSE:OXIG) Investors?
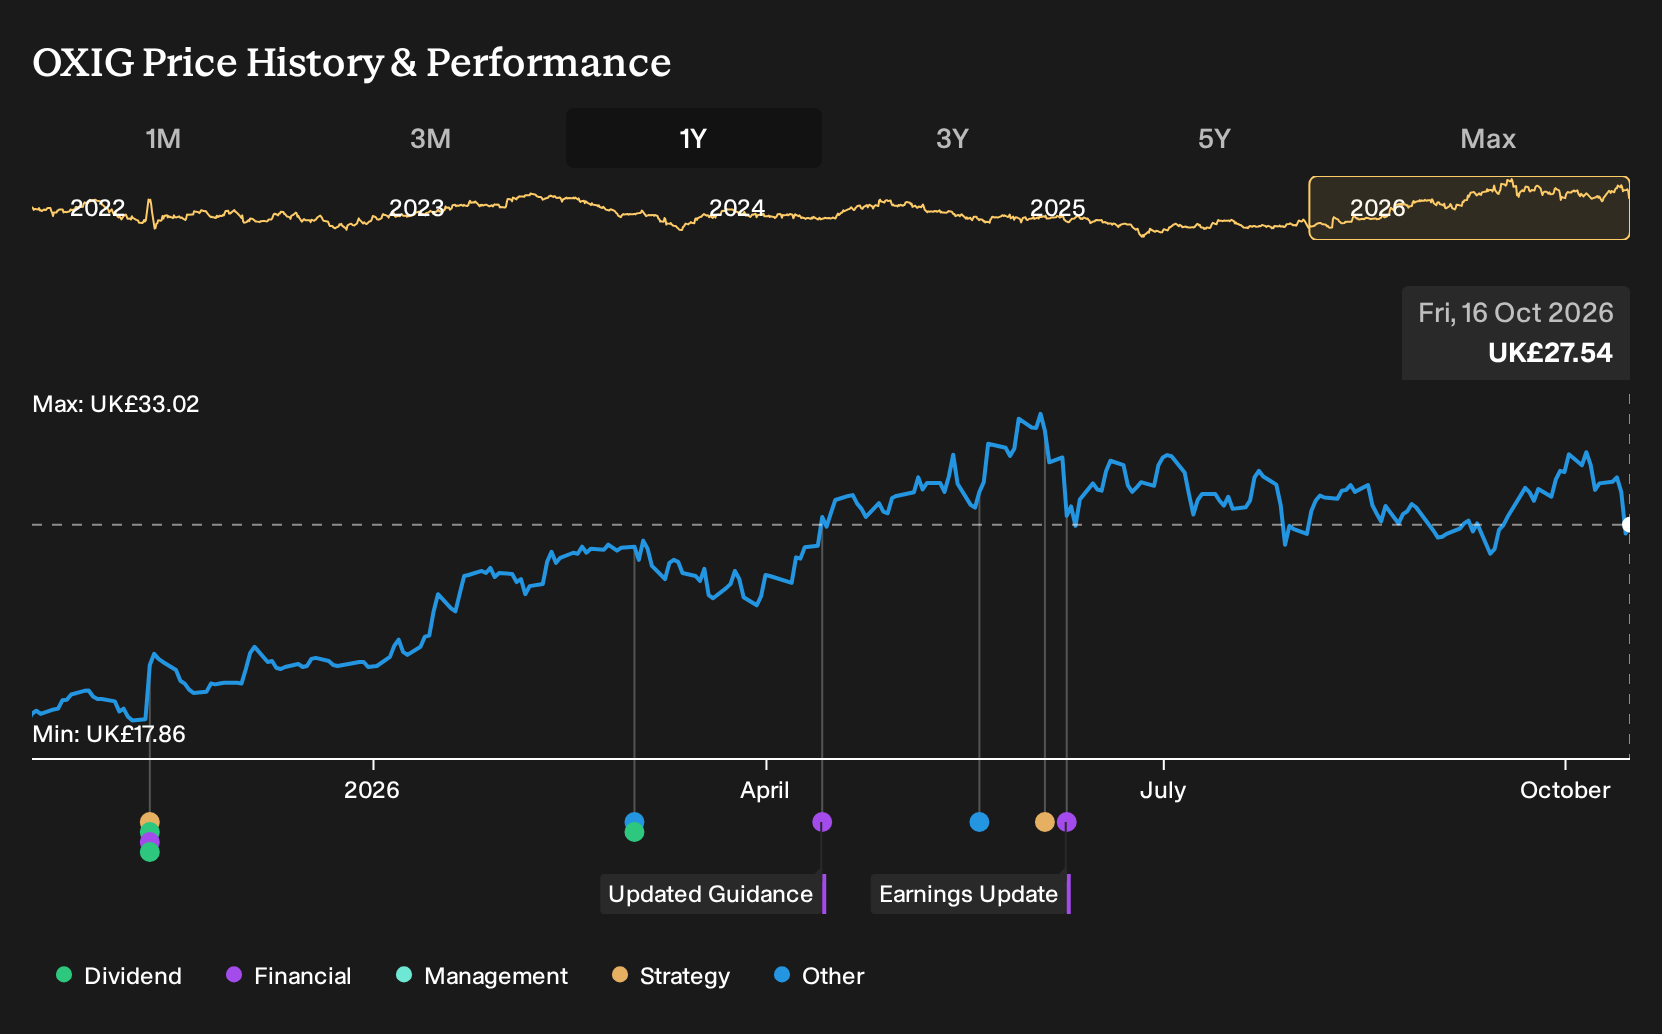
- Oxford Instruments recently reported group order intake up nearly 44%, with Advanced Technologies orders more than 125% higher, supported by facility expansions, supply chain work, margin progress and a planned £100 million share buyback, while management reiterated confidence in meeting full year expectations.
- The strongest demand is currently in compound semiconductor plasma systems for datacom and AI infrastructure, which highlights how Oxford Instruments is increasingly tied to long term AI hardware spending instead of short cycle lab budgets.
- We will now examine how this surge in AI linked orders could reshape Oxford Instruments’ investment narrative and medium term execution priorities.
Oxford Instruments Investment Narrative Recap
To own Oxford Instruments, you need to believe the surge in Advanced Technologies orders, especially in compound semiconductor tools for datacom and AI infrastructure, can translate into reliable long term equipment shipments rather than a one off spike. The key near term catalyst now sits in how quickly Severn Beach capacity and supply chain upgrades can turn that 44% group order intake increase into delivered revenue.
The biggest operational risk in the short run is execution friction. Capacity constraints, working capital already stretched by large quantum contracts, and ongoing weakness in Healthcare and Life Sciences all increase the chance that strong intake takes time to show up in cash and profit. The latest trading update does not remove that risk, but it does not materially worsen it either.
The £100 million share buyback announced alongside the order update is the most relevant move here. It tells you Oxford Instruments is running this AI hardware upswing while also committing a sizeable pool of capital to shrink the equity base rather than to further expansion projects or balance sheet flexibility.
In terms of catalysts, that program can amplify any progress on margins and earnings. However, it also concentrates exposure if operational issues, currency movements or China related volatility weigh on performance. With the share price already carrying a higher P/E than the wider European Electronic group, execution on Severn Beach ramp up, cash conversion and ongoing transformation efforts matters even more while the buyback is in effect.
Oxford Instruments' current analyst narrative points to revenues of £509.9 million and earnings of £71.1 million by 2029. This reflects assumed yearly revenue expansion of 6.4% and an earnings increase of about £26.6 million from £44.5 million today.
Uncover why Oxford Instruments' fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One sharper risk in the more optimistic Oxford Instruments narrative is timing. The most bullish analysts were already modelling £551.9 million of revenue and £78.4 million of earnings by 2029 before this AI order surge, assuming quicker operational follow through. If Severn Beach bottlenecks linger, those upbeat timelines might shift and opinions could spread further.
Explore 3 other Oxford Instruments fair value estimates, including one that suggests as much as 27% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Oxford Instruments research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Oxford Instruments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Oxford Instruments' overall financial health at a glance.
Looking for more investment ideas beyond Oxford Instruments?
Once you have a view on Oxford Instruments, it can help to widen the lens and compare it with other businesses that have different risk, income and balance sheet profiles. The Simply Wall St Screener is built for that kind of side by side work.
- If you want potential value combined with quality fundamentals, start with a curated set of 7 high quality undervalued stocks that pass both cash flow and balance sheet checks.
- If resilience matters more than excitement right now, filter the market down to 4 resilient stocks with low risk scores and see which businesses score well on stability and financial strength.
- If you are hunting for under the radar opportunities, scan through 5 high quality undiscovered gems that pair solid metrics with relatively low investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com