
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Gibraltar Industries (ROCK) Simplifies Its Portfolio, Is The Stock Still Cheap?
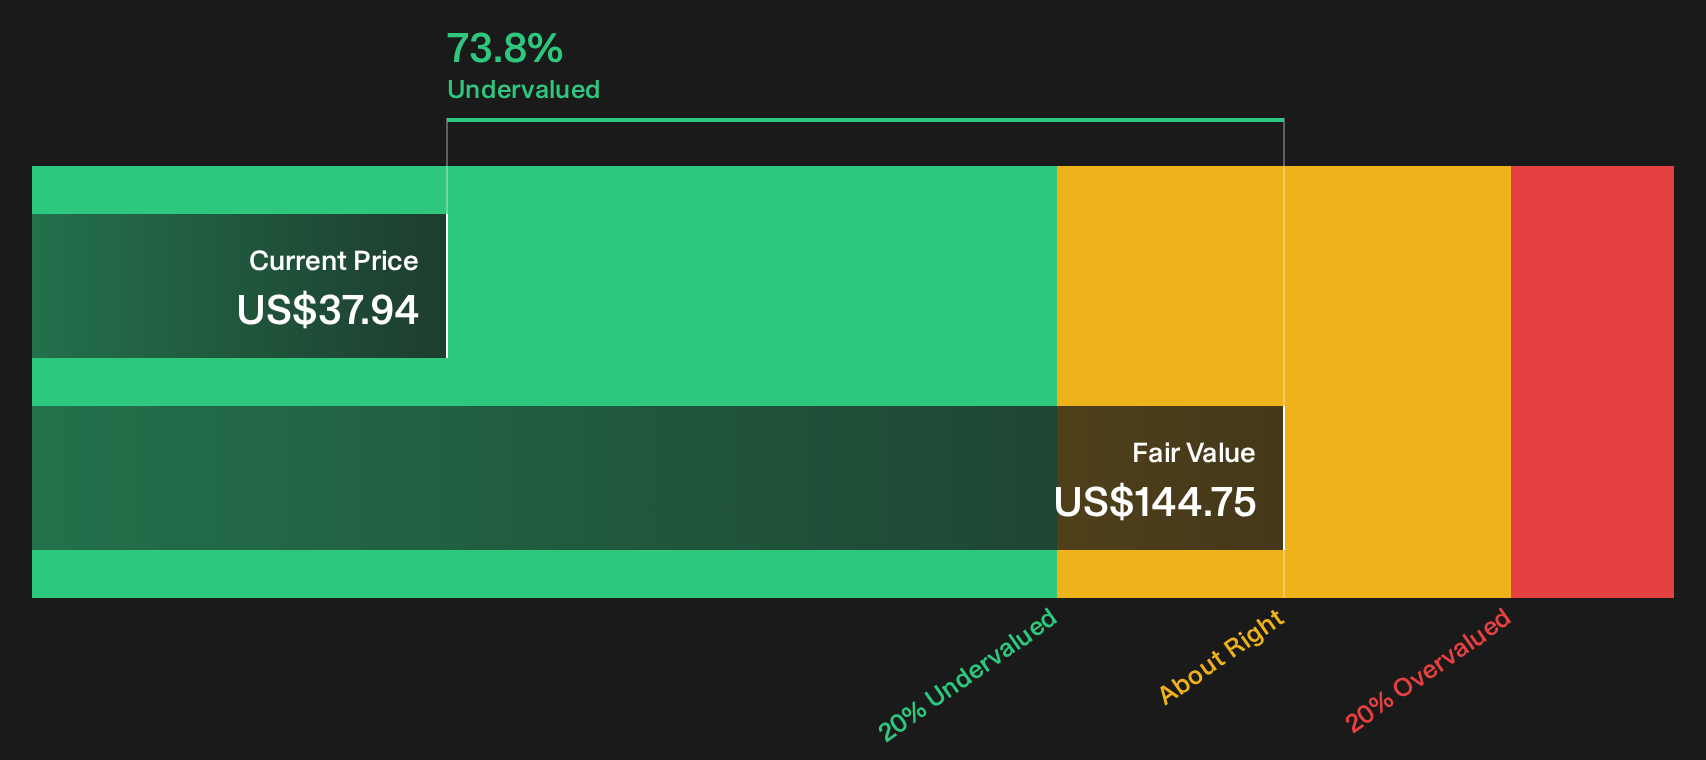
Gibraltar Industries (ROCK) has drawn attention after its share price closed at US$37.94, with the stock down over the past month and past 3 months despite positive annual revenue and net income growth.
Recent trading has been choppy for Gibraltar Industries, with the share price down 15.39% over the past 30 days and 12.14% over 90 days. The 1-year total shareholder return has fallen 43.47%, which points to fading momentum despite the latest 7-day rebound.
Balance recent volatility in Gibraltar Industries by comparing it to hand-picked peers using the list of solid balance sheet and fundamentals (25 results) that investors are watching for potential resilience.
The price has retreated, yet analyst targets and intrinsic value estimates sit far higher. Is Gibraltar Industries being mispriced, or are those valuation anchors out of step with the recent slide?
Most Popular Narrative: 50% Undervalued
Gibraltar Industries is priced at $37.94 while the most followed narrative anchors fair value at $75.25, which implies a wide gap that hinges on execution of its reshaped portfolio and OmniMax integration.
The divestiture of the Renewables segment and full exit from eBOS and racking operations is simplifying Gibraltar Industries, concentrating management attention and capital on Residential, Agtech, and Infrastructure. This can support a clearer revenue mix and margin profile over time. OmniMax integration projects have lifted identified synergy opportunities from US$20 million to US$29.4 million in 2026, with logistics, SKU rationalization, and SG&A savings already contributing to a 19% Residential adjusted EBITDA margin in Q2 2026.
See why 6 investors see Gibraltar Industries as 50% undervalued.
Result: Fair Value of $75.25 (UNDERVALUED)
Still, the story can break if Residential remains tied to a soft roofing market for longer than expected, or if OmniMax synergies and deleveraging progress disappoint.
Find out about the key risks to this Gibraltar Industries narrative.
Another View: How Gibraltar Industries Looks On Earnings
The first narrative leans heavily on discounted cash flows and a $75.25 fair value. On simple earnings math, Gibraltar Industries trades on a P/E of 18.7x versus the US Building industry at 19.7x, while its fair ratio is 38.9x. That gap suggests either a cushion or a warning, depending on how much weight you put on those forward earnings assumptions.
For investors comparing cash flow based and earnings based approaches, it is worth seeing how the SWS DCF model pieces this together in practice. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Gibraltar Industries so far. If you feel the clock is ticking on forming a clear view, consider both sides of the story and take a closer look at the 2 key rewards and 3 important warning signs
Looking for more Gibraltar Industries style investment ideas?
If you only stop at Gibraltar Industries, you risk missing out on other compelling setups that fit your risk, income, and value preferences across the market.
- Target resilient candidates with strong finances by scanning the list of solid balance sheet and fundamentals (25 results) that meet your quality and balance sheet standards.
- Hunt for potential value opportunities by running through the 33 high quality undervalued stocks and lining them up against your own fundamental checklist.
- Build a cash flow focused watchlist by reviewing the 8 dividend fortresses that combine income potential with robust underlying businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com