
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
1 Obvious Metric That Makes Nvidia a Top Stock to Buy Now
Key Points
None of 2027's expected growth has been priced into Nvidia's stock.
The growth thesis for Nvidia is based on solid forecasts.
Nvidia (NASDAQ: NVDA) may be the world's largest company by market cap, but that doesn't mean that its sales and earnings can't get bigger. However, if you look at how the stock market is valuing the company, then it's pretty obvious that the market thinks they won't.
This gap is a major investment opportunity, because if you know which metrics to look at, you can easily discern that Nvidia should soar over the next year. That makes it one of the top stocks to buy now.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: The Motley Fool.
The market isn't baking in any of 2027's growth
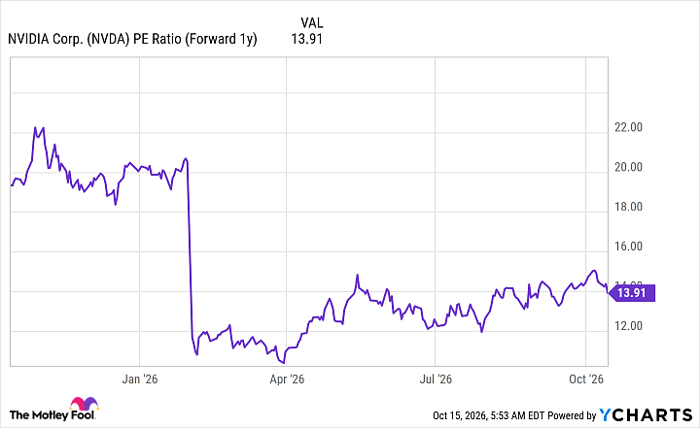
The metric I'm focusing on here is next year's forward price-to-earnings (P/E) ratio. For a rapidly growing company like Nvidia, this makes a lot of sense. Though it's based on estimates, this metric is actually fairly solid, as Nvidia has already told investors that it expects 70% revenue growth next year. Nvidia can make forecasts like that with some confidence because many AI hyperscalers have already locked in their capital expenditure plans for next year, as these decisions must be made well in advance. Contracts for chips have to be signed early if those cloud computing companies are going to ensure that when their new data center facilities have been constructed and connected to power, they'll have the chips and servers they need.
With that in mind, calculating what Nvidia's earnings will look like next year is fairly easy. If Nvidia hits Wall Street estimates for next year, and its stock doesn't move in price from now until then, it will trade for less than 14 times earnings.
NVDA PE Ratio (Forward 1y) data by YCharts.
That's an incredibly cheap price, and it's unlikely that Nvidia will trade at that range. Currently, its trailing P/E ratio is 28, which is quite reasonable for a company of Nvidia's caliber. As a result, I think there's a lot of upside to be had.
If Nvidia meets its earnings growth expectations and also trades at 28 times earnings at the end of its next fiscal year (ending January 2028), the stock would double between now and then. Picking up a stock that has real potential to double in a year and a half is a great investment move, and given Nvidia's great long-term visibility into what its clients will be spending, there's good reason to trust in that potential.
Some investors may be worried about how much the AI hyperscalers are spending, but they're still going to spend massive amounts of money on AI computing. There's too much at stake for them to risk falling behind their peers, and with several of the cloud computing providers stating that they have hundreds of billions of dollars in demand backlog, I think the AI companies will stay aggressive in their spending for a while, benefiting companies like Nvidia.
Keithen Drury has positions in Nvidia. The Motley Fool has positions in and recommends Nvidia. The Motley Fool has a disclosure policy.