
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 British AI Stocks To Watch In October 2026
Central bankers are openly talking about keeping interest rates higher for longer as AI projects soak up huge amounts of capital. That kind of funding squeeze can pressure big tech, while nimble UK AI specialists often stay under the radar. Ignoring them could mean missing some of the most interesting compounding stories in the market. This article highlights three smaller British AI focused stocks that may be worth a closer look.
The three AI small caps in this article are only a sample, and the full screen flagged 1 more UK focused company with a similarly compelling story that is not covered below. To size up that extra opportunity and quickly identify which UK AI plays best fit your criteria, head straight to the AI Small Caps screener.
Beeks Financial Cloud Group (AIM:BKS)
Beeks Financial Cloud Group provides managed cloud, low latency connectivity and analytics for trading venues and financial institutions, with its Market Edge Intelligence and Beeks Analytics platforms bringing AI and machine learning into packet level market data. The business generated about £26 million from public and private cloud services and £9 million from proximity and exchange cloud, and the stock is valued at roughly £120 million.
Beeks plugs AI directly into capital markets plumbing through Market Edge Intelligence and Analytics Enterprise, which analyse trading and infrastructure data rather than consumer clicks. Forecasts point to very strong earnings expansion off a small base. However, the premium P/E and thin margins leave a lot riding on how one unseen pressure shapes that AI pay-off.
With so much riding on that, go straight to the 1 key reward and 2 important warning signs to see what might accelerate Beeks Financial Cloud Group or quietly cap its upside.

Softcat (LSE:SCT)
Softcat blends bread and butter IT reselling with a focused Softcat Intelligence arm that helps clients run AI, automation, and data-heavy workloads in the real world. It generates about £2.0b from its UK operations and has a market value near £3.7b.
Softcat gives this AI Small Caps list a more grounded angle, since its AI and automation work grows out of a large, existing IT infrastructure base rather than a single product bet.
"Expansion into the US through the planned GDT acquisition, with GDT forecast to contribute about US$240m gross profit and US$80m adjusted EBITDA in calendar 2026, could broaden Softcat’s revenue base and support earnings growth as the combined group gains more exposure to multinational customers."
What happens to Softcat’s margins if a quiet shift in its mix of high value AI services and hardware heavy contracts goes the wrong way?
If that shift worries you, read the full narrative for Softcat to see how Softcat’s AI work, US push and capital returns could be pulling in different directions.
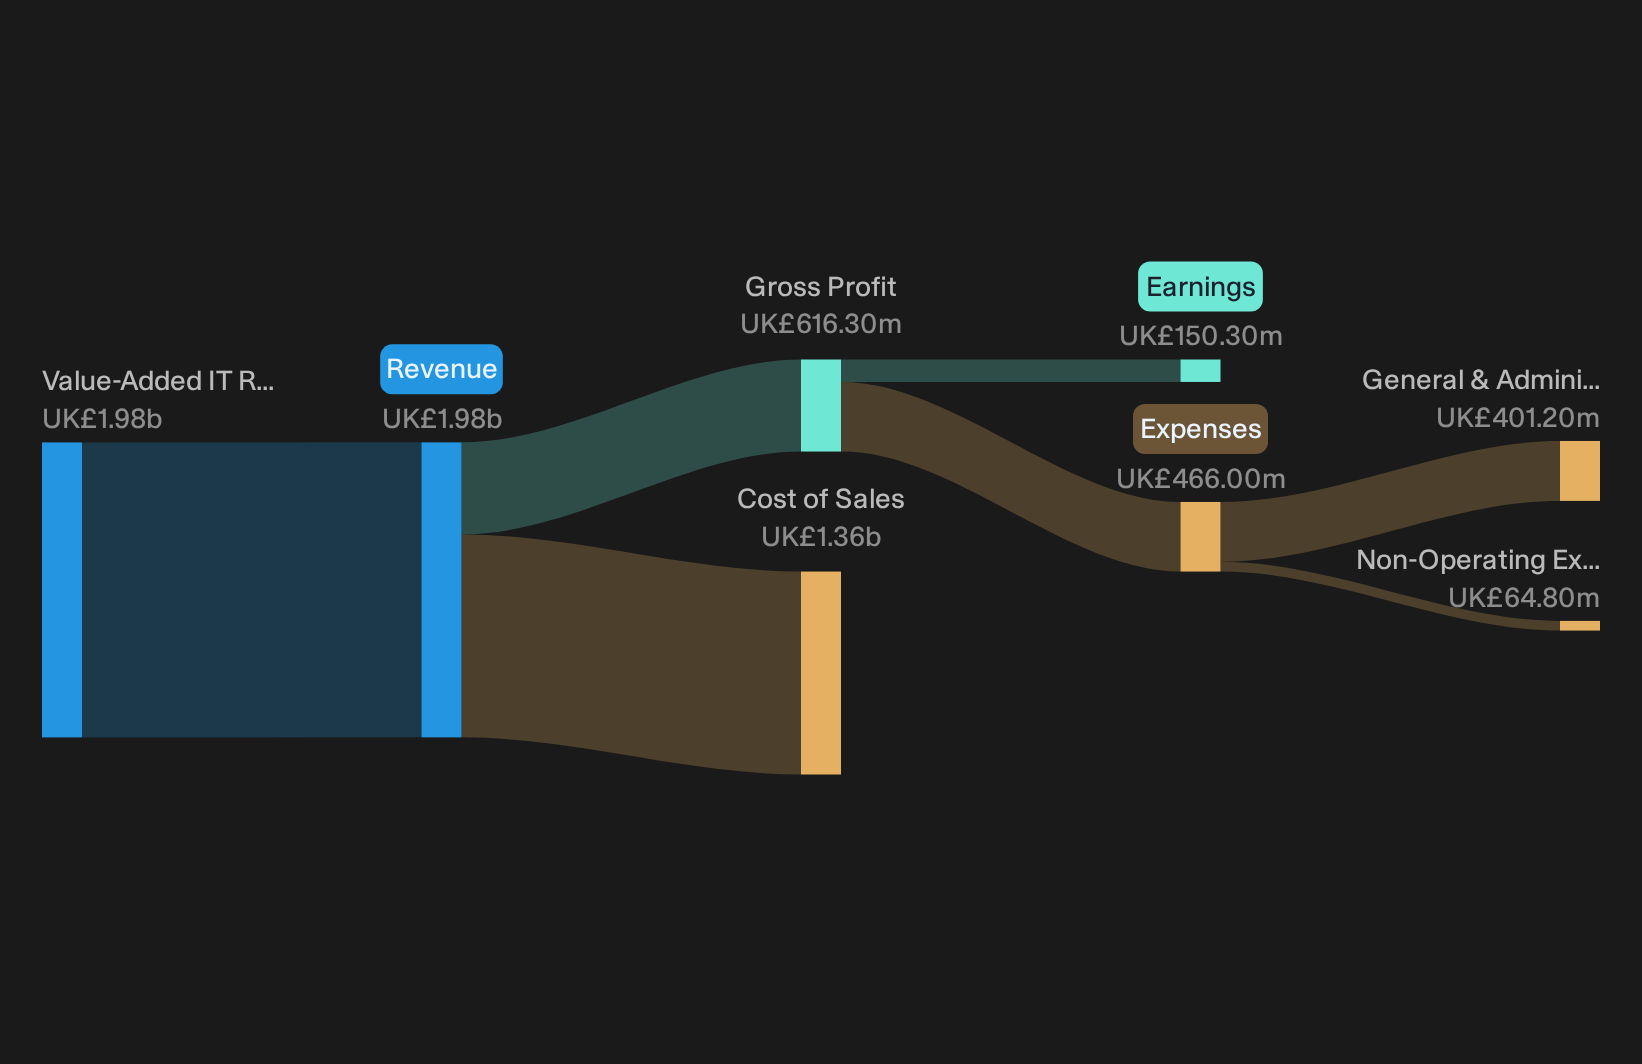
TPXimpact Holdings (AIM:TPX)
TPXimpact Holdings blends consultancy, software development and managed services with a focused data science and AI practice inside its Digital Transformation arm. This arm brought in about £62 million, alongside roughly £11 million from Manifesto and £10 million from KITS, and the stock is valued near £90 million.
TPXimpact Holdings matters for this AI Small Caps list because its AI and data science teams are embedded in real government and public service projects, where practical automation and analytics can reshape how critical services actually run.
"Although the acceleration of AI enabled workflows and case management in government could deepen TPXimpact’s role within existing programmes, its choice to position AI as an embedded capability rather than a stand alone offer may see higher margin opportunities captured by larger, more specialised competitors. This could constrain future earnings expansion."
What happens to TPXimpact’s earnings power if a single assumption about how those long term public contracts translate into pricing strength breaks?
If that contract maths feels fragile, read the full narrative for TPXimpact Holdings to see how TPXimpact Holdings could turn embedded AI work into accelerating pricing power and resilience.

Seeking Alternatives Before The Crowd
Fresh opportunities do not wait. While attention chases the latest breakout, other ideas build quiet momentum under the radar for now. Consider these before the window narrows and be prepared to act based on your own judgment.
- Target sturdier income streams by scanning the 2 dividend fortresses that could help keep cash flowing even when sentiment moves against more fragile payers.
- Look for financial resilience with the list of solid balance sheet and fundamentals (9 results) so you are focusing on businesses that may be better positioned to navigate funding constraints and changes in interest rates.
- Explore early sector momentum by reviewing the 92 robotics and automation stocks that could be relevant as automation spending influences factories, warehouses and everyday services.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com