
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
U.S. Bancorp (USB) Stock Gains Traction After Q3 Earnings Margins Impress
U.S. Bancorp stock closed at US$58.72 on Friday, up 2.3% on the day, even though 30 day and 90 day returns remain in the red. Traders liked what they saw from the freshly released Q3 2026 report, yet the real story sits in how those profits are being earned.
The headline result is simple: basic earnings per share came in at US$1.41 on total revenue of US$7.29b. Beneath that, the key thread is a margin story, with net profit running at roughly 28.7% over the last year. This points directly to the longer term debate on valuation and resilience.
Like the earnings power at U.S. Bancorp but wary that margin quality can change fast when conditions turn? Check our list of solid balance sheet and fundamentals stocks (25 results) for banks and financials that combine firm profitability with balance sheets built to handle stress.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$7,294m vs. US$6,729m (up about 8%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$2,202m vs. US$1,893m (up about 16%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.41 vs. US$1.22 (up about 16%)
- Net Interest Margin (NIM, Q3 2026 vs. Q3 2025): 2.79% vs. 2.75% (slight improvement in lending spread)
Earnings grab headlines, but investors who care about what they are paying usually watch the cash moving through the business just as closely. That is where the regular flow of deposits, loans and fee income at U.S. Bancorp starts to matter.
On those cash flows alone, and using the discounted cash flow work referenced in the summary, the stock could be a hefty 47% undervalued.
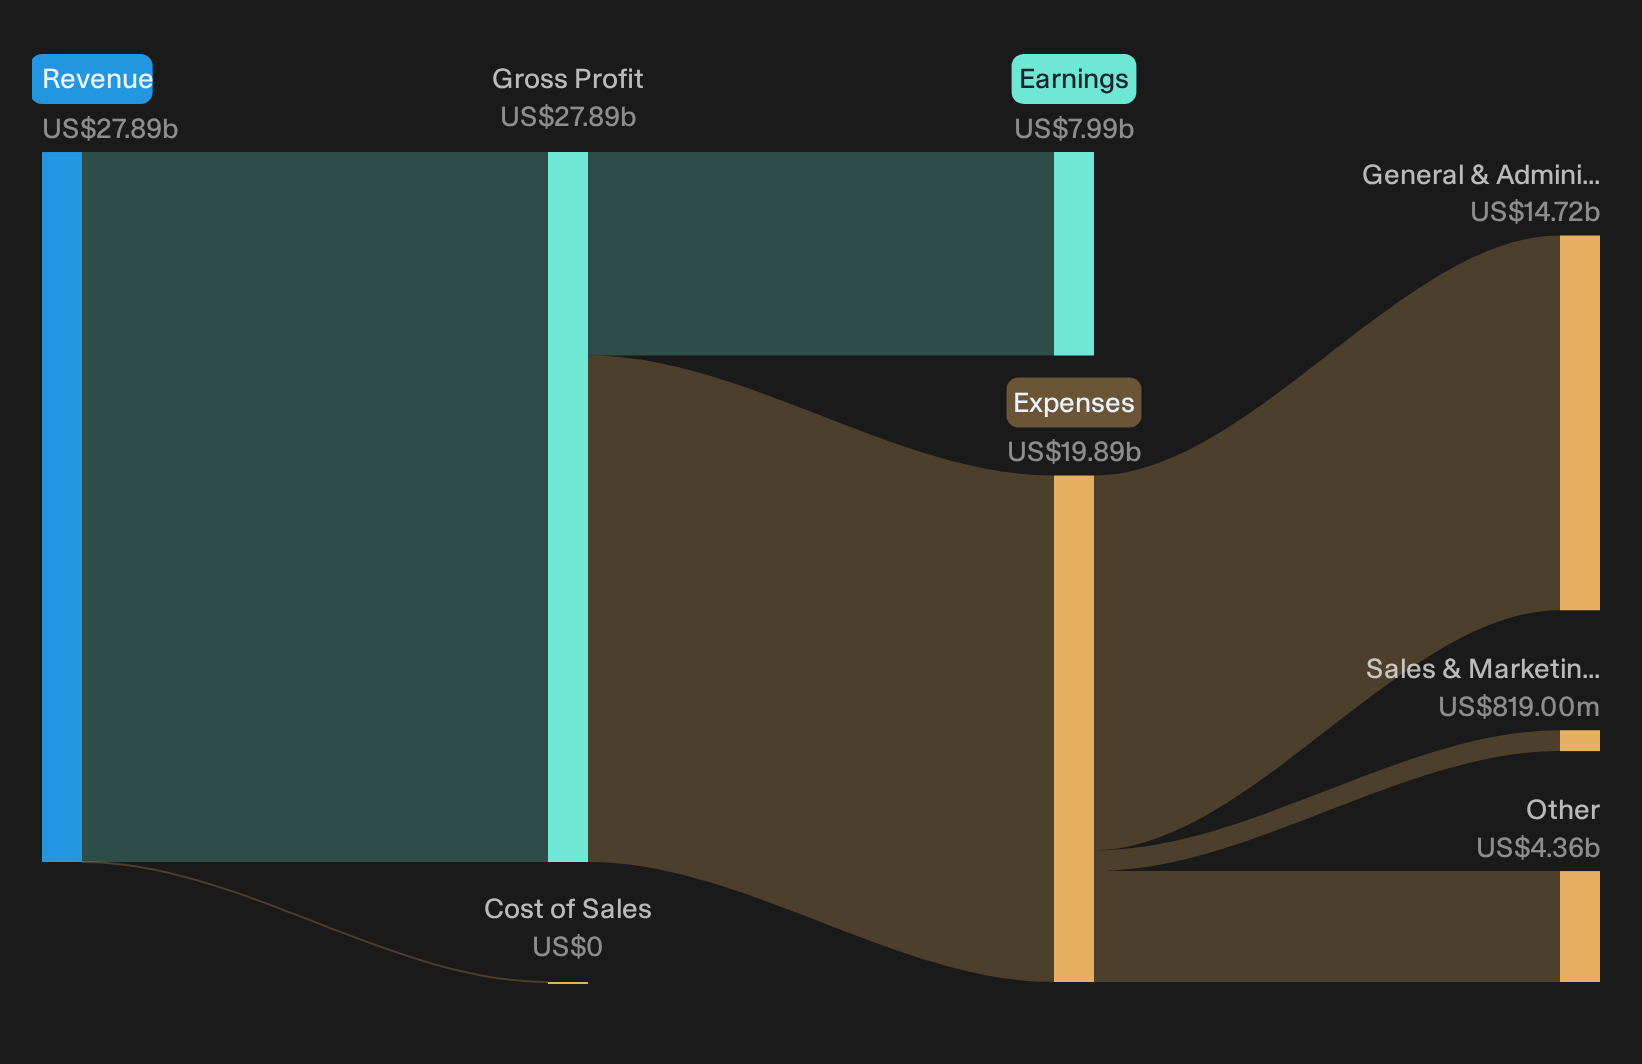
U.S. Bancorp fee engine: progress check
The bullish story says U.S. Bancorp can lean on a richer stream of fees rather than just collect interest spread.
"U.S. Bancorp's earlier focus on payments volumes, trust and investment management fees is now supported by fee income at 44% of total revenue in 2Q26 and low teens fee growth year over year, including about 10% excluding BTIG."
Q3 results keep that idea alive. Fees again sat at 44% of revenue, BTIG delivered about US$226m of quarterly fees, and total payments income grew 6.5% with corporate payments up 19%. Expense growth stayed below revenue growth, so operating leverage improved rather than slipping as fee reliance rose.
Testing U.S. Bancorp’s disruption and credit worries
The bear view flags fintech competition and credit stress as the pressure points that could crack this story.
"The accelerating shift to digital finance and open banking could still allow new fintech and non bank competitors to gain share in payments and everyday banking, which could pressure U.S. Bancorp's fee income and net interest margins if customers move transactions and balances off the platform, potentially weighing on revenue growth and earnings."
Recent numbers do not show that squeeze yet. Payments revenue rose, the Amazon small business card added roughly US$1.7b of period end loans, and NIM ticked up to 2.84%. On the risk side, net charge offs were 51 bps with non performing assets slightly lower, and credit issues were described as concentrated mainly in commercial real estate and muted mortgages rather than broad based deterioration.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Quiet Fundamental Setups
U.S. Bancorp just showed how a single quarter can reshape the conversation around fee strength and credit risk. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 49% below our estimate - uses a digital small business platform and tech-focused lending model to deepen primary banking relationships while managing credit losses and operating costs.
- Company 2 - 32% below our estimate - tightens an industrial equipment portfolio and factory footprint so higher margin aftermarket work and a growing power and nuclear project mix support earnings.
- Company 3 - 39% below our estimate - builds a recommerce platform that channels subsidized device trade ins and refurbishment capacity into higher quality secondhand inventory for cost conscious, sustainability minded consumers.
That is three of the list. See every one of the 33 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com