
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Interactive Brokers Stock And Other Rate Sensitive Cash Plays In Focus
US deficits sitting near $2t have turned short-term interest rates and Treasury bills into the main stage rather than the sideshow. Cash is no longer just a parking bay; it is a source of real yield and policy risk in one package. This article unpacks that trade off and walks through 3 stocks exposed to these fiscal cross currents, so you can judge whether to lean in or step back.
The stocks covered below are just a small sample, and the full screen surfaced 17 more US cash and short-duration yield plays with equally compelling stories that are not unpacked in this article. To go straight to the source and analyze the field to identify your highest conviction ideas, head into the US Cash and Short-Duration Yield Products Benefiting from Persistent Large Deficits screener.
NewtekOne (NEWT)
Overview: NewtekOne is a US bank holding company that provides small and medium businesses with deposits, lending, payments, payroll, insurance and related financial services.
Operations: NewtekOne generates about US$201 million from Banking and US$44 million from Payments in the United States, with smaller adjustments across other segments.
Market Cap: US$306 million
NewtekOne matters for this screener because it pairs small business lending with deposit funded, short-duration interest income that is closely tied to where US short-term rates settle.
"Originating C&I long amortization loans directly in Newtek Bank and funding them with core deposits instead of warehouse lines that were priced around SOFR plus 3.25% reduces reliance on higher cost wholesale funding and can widen net interest spreads and net interest income over time."
What happens if a single assumption around how much small business borrowers ultimately repay shifts against those carefully modelled spreads?
If that repayment risk is front of mind, read the full narrative for NewtekOne to see how NewtekOne’s model could adapt as short rates and credit costs decouple.
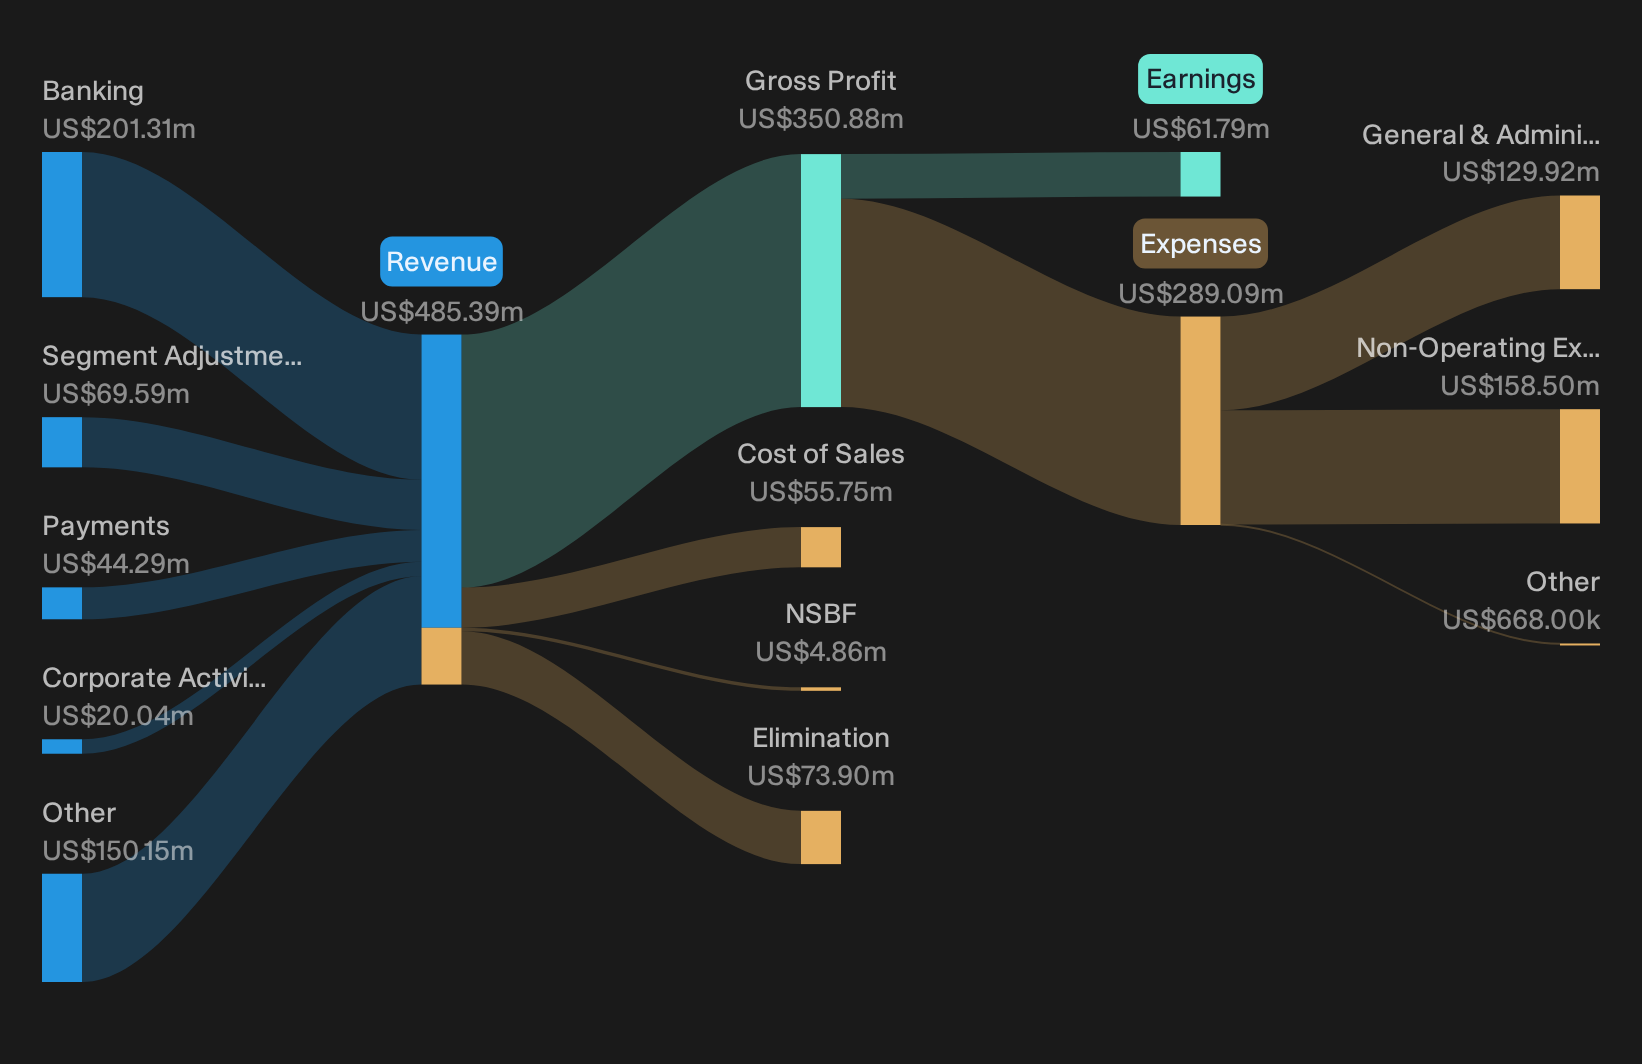
Interactive Brokers Group (IBKR)
Overview: Interactive Brokers Group runs a global electronic brokerage platform where investors and institutions trade multiple asset classes and manage cash balances.
Market Cap: US$146.36 billion
Interactive Brokers Group sits near the bullseye of this screener theme because its business model depends on client cash, sweep programs and short-duration yield choices that respond directly to where short-term rates settle.
"Net interest income climbed 21 percent to $967 million due to higher securities lending, larger client margin loans, and rising interest on credit balances. When interest rates eventually fall, income from margin loans and idle client cash could compress, putting pressure on earnings unless trading activity remains strong."
The real swing factor now is how one quiet shift in client behaviour could reshape the balance between fee income and rate driven cash returns.
That quiet shift in behaviour is exactly what the full story tackles, so read the full narrative for Interactive Brokers Group to see how Interactive Brokers Group could turn it into accelerating opportunity.

Noah Holdings (NOAH)
Overview: Noah Holdings runs a cross-border wealth and asset management platform for high net worth clients, steering capital into funds, insurance and other managed products, including cash-like and short-duration options that link it to the screener’s higher-yield cash-management theme.
Operations: Noah Holdings generates around CN¥722 million from Mainland China Public Securities, CN¥688 million from Mainland China Asset Management and CN¥532 million from International Asset Management, with Mainland China contributing CN¥1.48 billion of total revenue.
Market Cap: US$505 million
Noah Holdings matters here because a China-focused wealth platform that already offers money market funds and overseas cash-like products can become a channel into higher global short-term yields as large US deficits keep T-bills and short duration instruments in the spotlight.
"Although Noah Holdings is leaning on AI enabled servicing, with the Singapore pilot already profitable and most local clients handled through the platform, the 21.9% fall in international net revenue in H1 2026 shows that exiting legacy insurance and referral channels can leave a lasting hole in overseas fee income that AI productivity may not fully replace."
What really matters now is how one unseen shift in client product mix filters through to future fee stability and operating leverage.
That shift in product mix is the real story, and the full narrative for Noah Holdings shows how Noah Holdings could turn it into accelerating fee resilience and overlooked upside.

Seeking Fresh Alternatives Before They Fly
Fresh ideas tend to move first. Slow money can get caught chasing momentum after a breakout, while earlier entries participate in the move before the data goes stale. Stay ahead and consider acting before the crowd.
- Identify cash-rich businesses that may be quietly building momentum before they attract broader attention by reviewing the curated list of solid balance sheet and fundamentals (25 results), which filters for financial strength.
- Follow structural demand for secure transactions and emerging payment rails by scanning the hand picked 18 cryptocurrency and blockchain stocks, which focuses on listed companies involved in blockchain infrastructure and services.
- Monitor copper producers positioned for electrification-related upgrades by using the focused 17 top copper producer stocks so that potential developments in this space remain visible.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com