
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Trinidad Nitrogen Shutdown Could Be A Game Changer For Nutrien Stock (TSX:NTR)
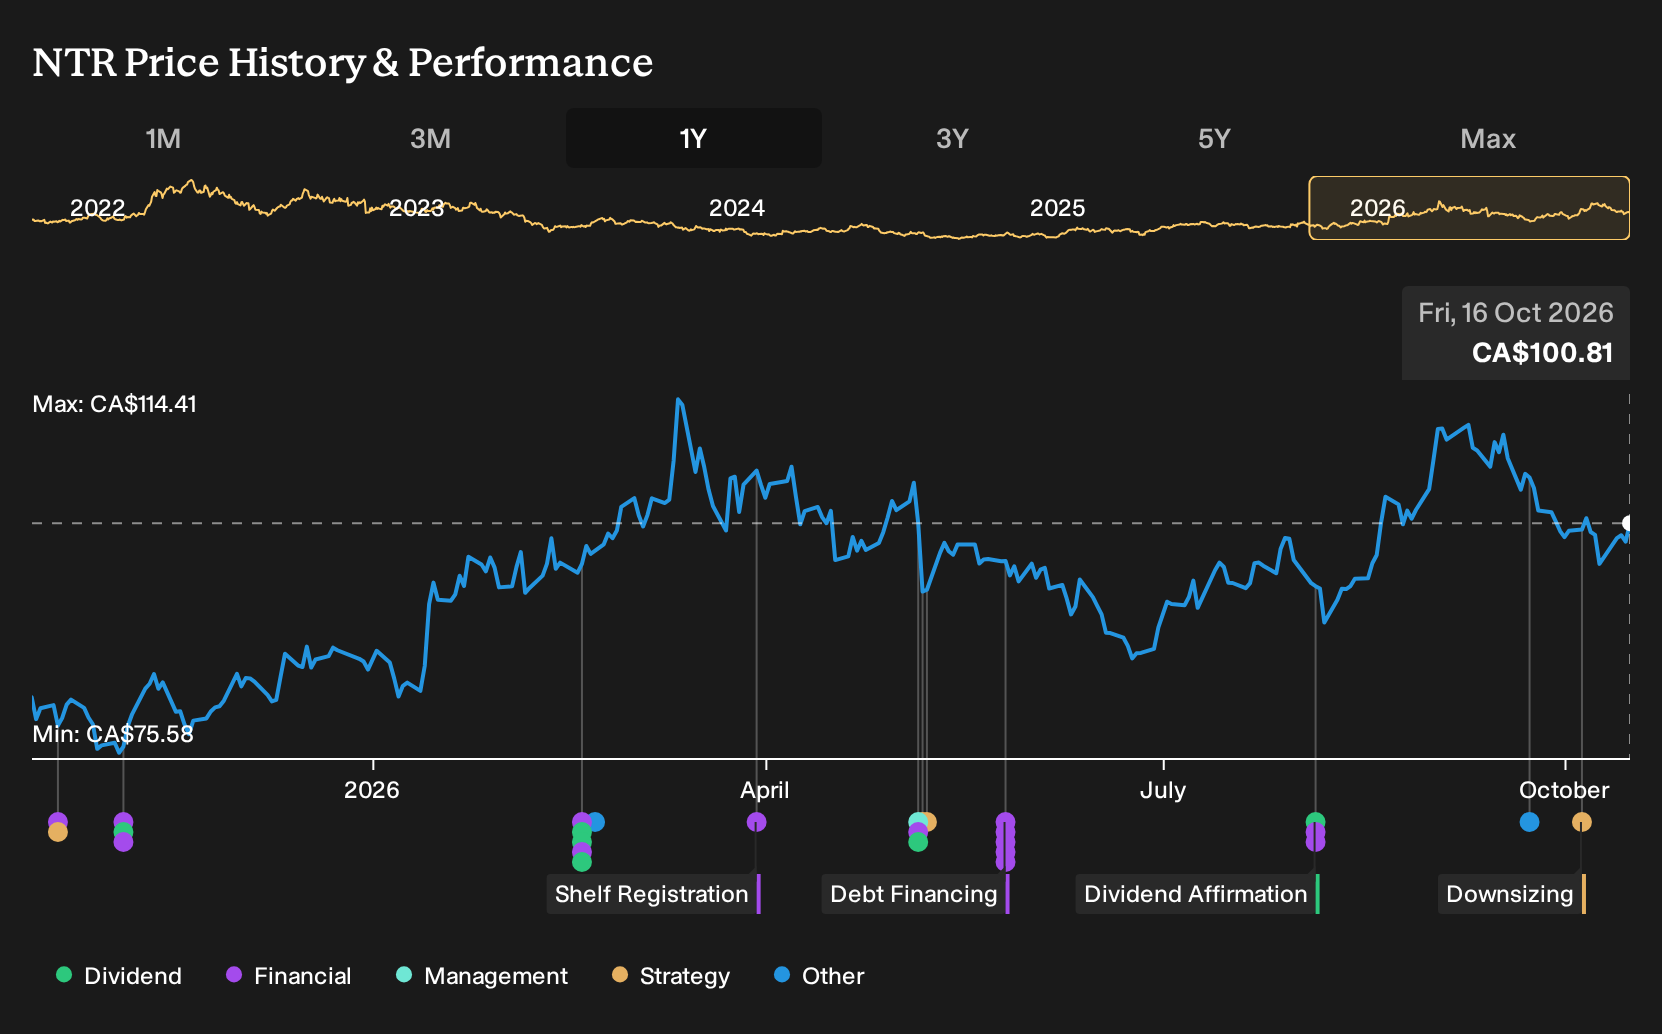
- Nutrien announced in early October 2026 that it will indefinitely shut its Trinidad Nitrogen operations at Point Lisas after prolonged natural gas constraints and an earlier controlled halt in October 2025.
- The move removes a capital intensive, gas constrained asset from the portfolio and signals a tighter focus on free cash flow and return on invested capital, with nitrogen supply shifting toward North American facilities.
- We will examine how Nutrien's investment narrative is reshaped by the Trinidad nitrogen shutdown and the shift toward North American assets.
Scan how Nutrien’s portfolio shift compares with peers by checking out list of solid balance sheet and fundamentals (8 results), which could handle similar operational shocks without stretching their finances.
Nutrien Investment Narrative Recap
To own Nutrien, you need to be comfortable with a fertilizer producer that leans heavily on potash and nitrogen while trying to squeeze more free cash flow from a mature portfolio. The Trinidad shutdown fits that story. It removes a gas constrained site that had been hurting cash generation, while keeping 2026 nitrogen volume guidance intact.
The key short term swing factor remains how efficiently Nutrien runs its North American nitrogen and potash assets and manages input costs, especially natural gas. The biggest operational risk still sits in fertilizer pricing, regulatory pressure, and execution on cost reductions, rather than this specific closure, which is contained.
The upcoming third quarter 2026 results and conference call now matter more, because they will be the first real test of how Nutrien frames the Trinidad decision inside its broader capital allocation plan. Investors get a chance to see how management discusses free cash flow, debt and any redeployment of spending toward North American nitrogen debottleneck projects.
Listen for concrete data on nitrogen production reliability, maintenance spending, and any restructuring or impairment impacts linked to Point Lisas. Those details feed directly into the current catalysts around efficiency gains, balance sheet flexibility and the effort to offset forecast earnings pressure over the next few years.
Nutrien's analyst narrative points to revenues of $27.7b and earnings of $2.1b by 2029. This implies broadly flat revenue assumptions and an earnings decline of $0.3b from $2.4b today.
Uncover why Nutrien's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on retail fertilizer weakness rather than nitrogen outages. The most cautious Nutrien analysts were already modeling revenues of about $26.5b and earnings of $1.8b by 2029, well below consensus. That more pessimistic script might look even harsher after the Point Lisas shutdown, so it is worth comparing both narratives yourself.
Explore 4 other Nutrien fair value estimates, including one that suggests it could be worth just CA$98.51.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Nutrien research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nutrien. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, which makes it easier to evaluate Nutrien's overall financial health at a glance.
Looking for more Nutrien sized investment ideas?
If the Nutrien story has you rethinking portfolio balance, it can help to widen the search and compare it with other businesses with different risk and income profiles.
The Simply Wall St Screener can surface stocks with characteristics that match what you want from your next position, whether that is resilience, yield, or mispriced quality.
- If you want income to play a bigger role, scan for potential higher yielding opportunities through 3 dividend fortresses that meet your own risk and payout comfort levels.
- If capital preservation matters more right now, focus on resilience by filtering for 8 resilient stocks with low risk scores that might handle tough conditions without stretching their finances.
- If you prefer to hunt for mispriced quality, look for 5 high quality undervalued stocks that appear fundamentally solid based on the data.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com