
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TC Energy (TSX:TRP) Could Be 14% Below Fair Value After Coastal GasLink Partnership
TC Energy (TSX:TRP) just closed an agreement with FN CGL Pipeline Limited Partnership, giving five First Nations an economic interest in the Coastal GasLink pipeline and formally advancing Indigenous participation in the project.
For investors watching TC Energy, the agreement lands at a time when momentum has started to cool. The share price is at CA$87.13 after a 1-day share price return of 2.98% and a year to date share price return of 13.38%. However, the 90-day share price return shows a decline of 10.90% and the 3-year total shareholder return of 140.96% points to a very strong longer run, with the latest pipeline partnership likely feeding into how the market weighs future growth prospects against execution and regulatory risks.
Scan how TC Energy compares with other regulated pipeline and energy infrastructure players by running the hand picked 41 power grid technology and infrastructure stocks together with this latest Indigenous partnership news.
After a sharp three year run and a recent pullback, TC Energy now sits in an awkward middle ground. Is the recent Indigenous partnership a fresh source of upside, or has most of the return already been reflected in the price?
Most Popular Narrative: 14% Undervalued
Against TC Energy's last close at CA$87.13, the most followed narrative pins fair value at CA$100.77, framing the recent Indigenous partnership within a broader view that the pullback has gone too far while still flagging structural risks.
Investors may be overestimating TC Energy's long-term revenue and EBITDA growth by assuming that the current surge in North American natural gas demand, driven by LNG export growth, coal-to-gas conversions, data center buildouts, and electrification, will persist at elevated rates, despite mounting global pressures for renewables and potential demand destruction for fossil fuels over the long run.
See why 69 investors see TC Energy as 14% undervalued.
Result: Fair Value of CA$100.77 (UNDERVALUED)
Still, higher leverage and ongoing capital needs, combined with potential contract or regulatory setbacks, could quickly challenge the idea that TC Energy is simply 14% cheap.
Find out about the key risks to this TC Energy narrative.
Another View: TC Energy On Earnings Power
The fair value narrative built on analyst targets leans positive, but the SWS DCF model tells a different story. At a share price of CA$84.61, it estimates TC Energy's future cash flow value at CA$33.23, which points to the stock trading well above that figure. Which lens do you trust more when cash flows and sentiment pull in opposite directions?
Look into how the SWS DCF model arrives at its fair value.
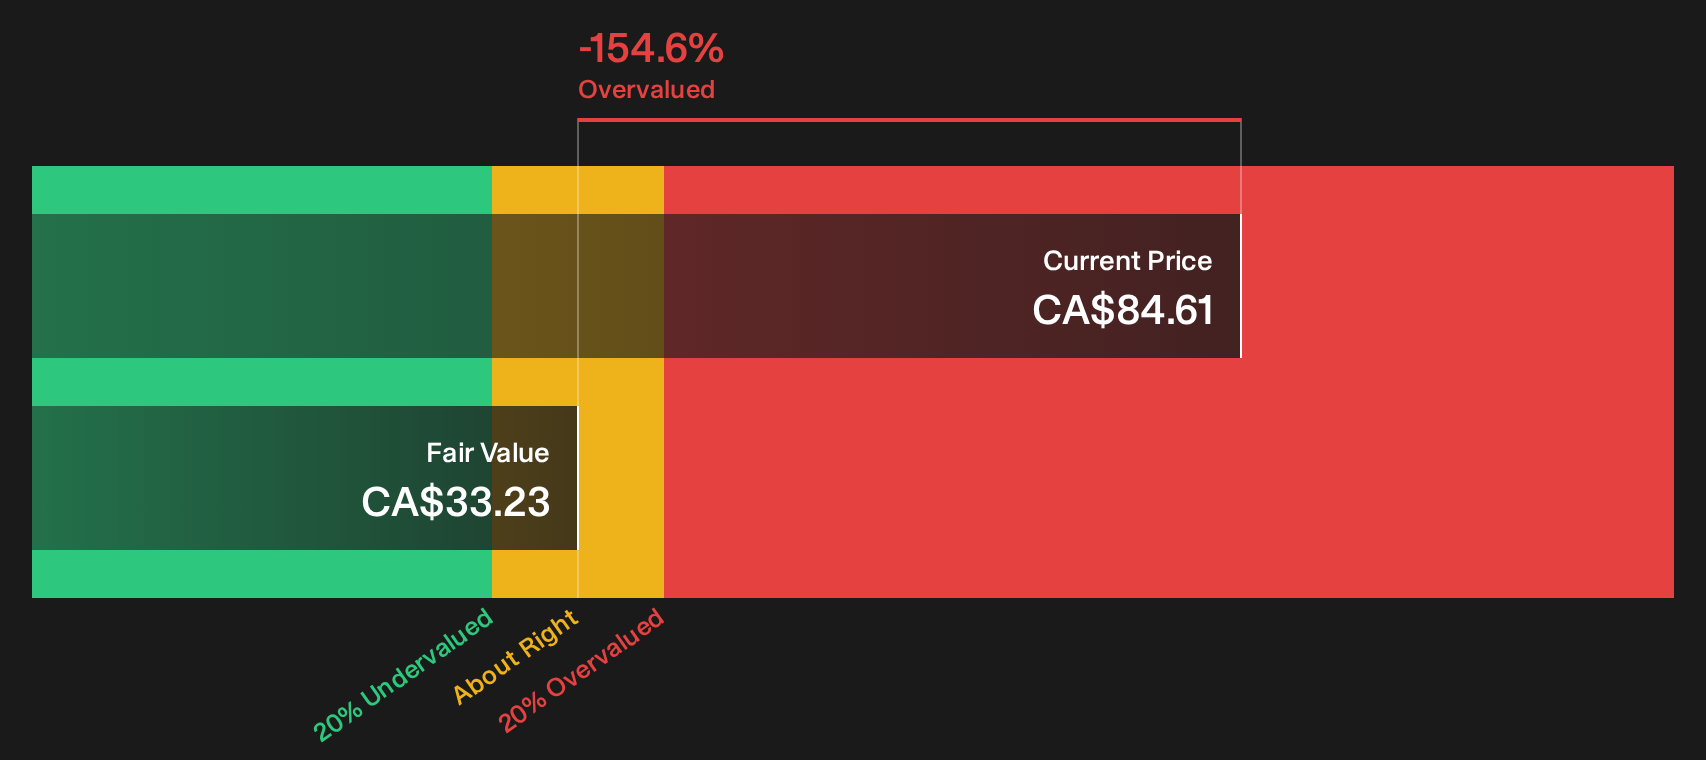
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TC Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on TC Energy is mixed, with both caution and optimism in play. Move quickly, review the data yourself and weigh the 1 key reward and 2 important warning signs.
Looking for more TC Energy investment ideas?
TC Energy is only one piece of your portfolio. Use these targeted screeners to evaluate your thinking and help avoid missing opportunities sitting in plain sight.
- Target potential mispricings by scanning a curated 5 high quality undervalued stocks that combines strong fundamentals with prices that may not fully reflect underlying business quality.
- Strengthen your income stream by reviewing a focused set of 3 dividend fortresses that pair higher yields with an emphasis on resilience.
- Dial down risk by narrowing in on 8 resilient stocks with low risk scores that aim for sturdier balance sheets and more consistent financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com