
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Do Profit And Capital Strains Change The Bull Case For Kemper Stock (KMPR)?
- Kemper Corporation is under scrutiny after recent coverage highlighted multi year declines in net premiums earned, earnings per share, and book value per share, raising concerns about the insurer's underlying profitability and balance sheet strength.
- The discussion zeroes in on Kemper's capital management hurdles, suggesting that the way the business allocates and protects capital has become just as important as its ability to write policies in the first place.
- The focus now turns to how Kemper's profitability pressures and capital management questions may reshape the broader investment narrative around the insurer.
Refocus your watchlist by contrasting Kemper's pressures with insurers and financials that score well on balance sheet strength using our hand picked list of solid balance sheet and fundamentals (25 results)
What Is Kemper's Investment Narrative?
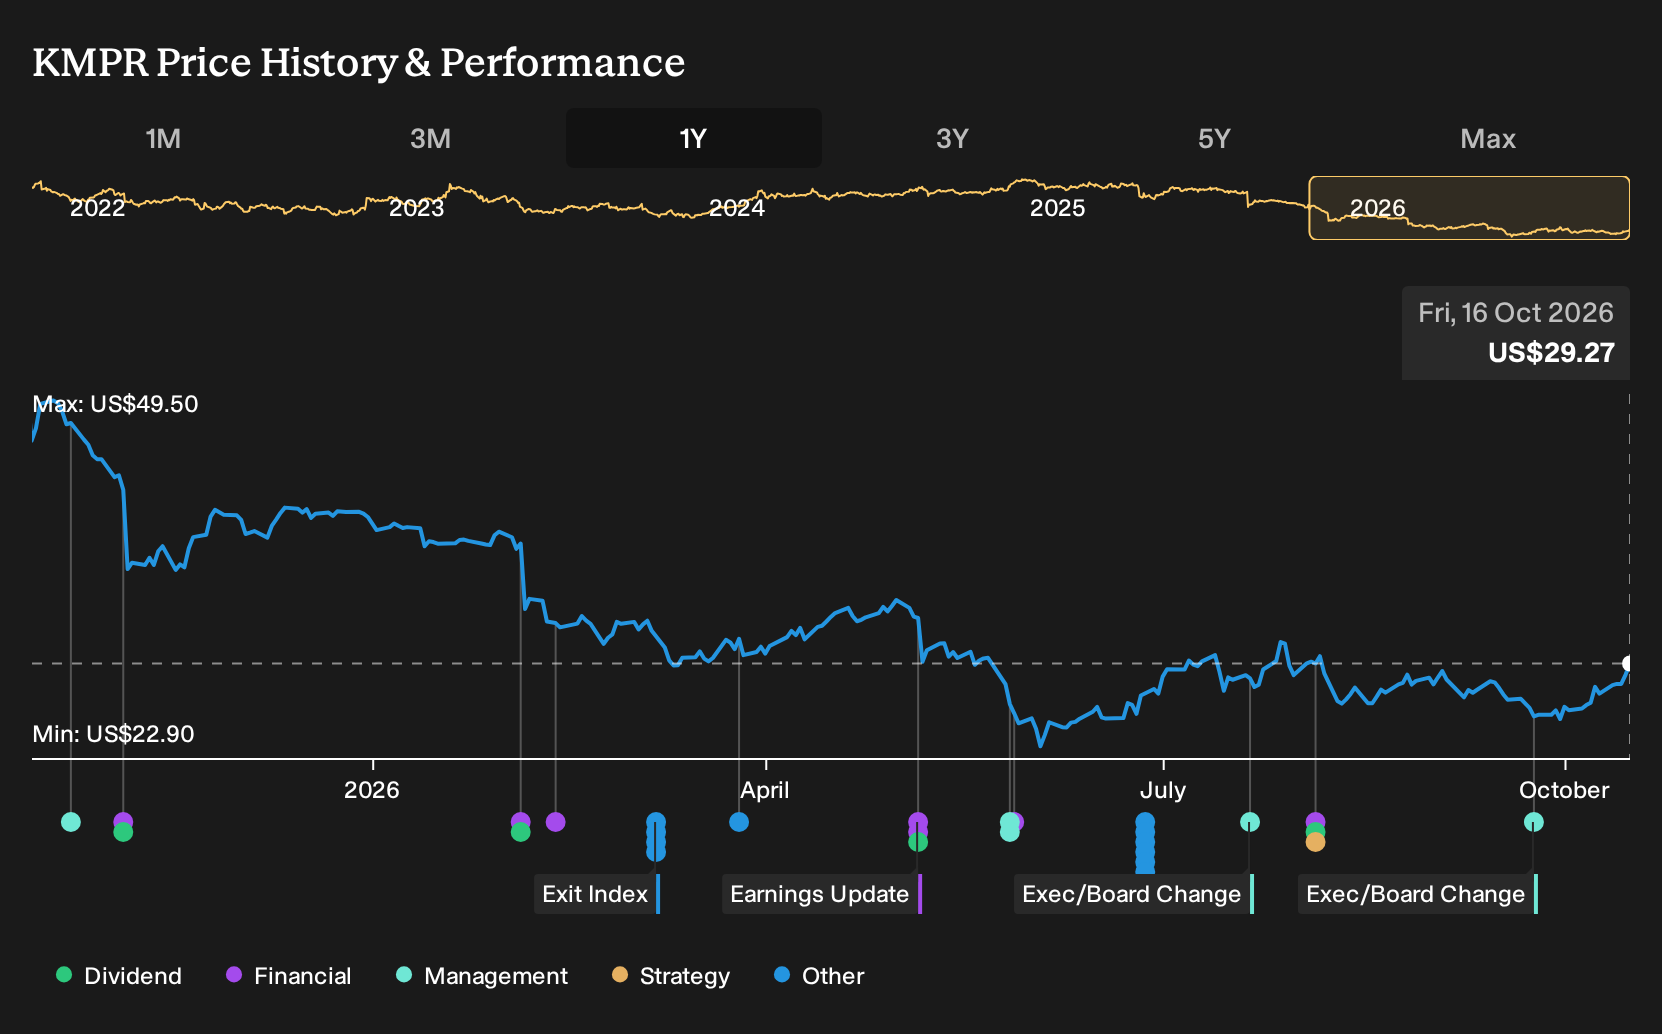
For anyone considering Kemper, the core belief is that a cleaner, more disciplined insurance operation can emerge from a tough stretch. The group is centered on specialty auto and life coverage, which are capital heavy and sensitive to pricing, underwriting discipline, and claims trends. Recent commentary about multi year declines in net premiums earned, earnings per share, and book value per share fits directly into this. It reinforces that the near term story is less about growth and more about Kemper proving it can underwrite profitably and protect its balance sheet.
In the short term, the key swing factors are execution on rate and risk selection in specialty auto, expense control, and access to funding on acceptable terms given that interest payments are not well covered by earnings. The dividend, which is not well covered by current profits, also hangs over capital planning. Recent criticism does not necessarily change these catalysts. It does push them into sharper focus, because any stumble on underwriting or capital management now feeds a narrative that the business is still struggling to earn its cost of capital.
Yet there is a complication sitting in the background that could matter far more if conditions shift even slightly.
There's only one way to know the right time to buy, sell or hold Kemper. Head to Simply Wall St's company report for the latest analysis of Kemper's Fair Value.
Exploring Other Perspectives
One alternate view puts catastrophe losses at the center of the Kemper story. The most pessimistic analysts were still modeling revenue of about $4.8b and earnings near $414.7m by 2029, yet they attached a low P/E of 3.5x. That gap shows how sharply opinions can diverge. Use this news to test which storyline you find more convincing.
Explore 3 other Kemper fair value estimates, including one that suggests as much as 18% downside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kemper research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kemper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kemper's overall financial health at a glance.
Looking For More Ideas Beyond Kemper?
If the Kemper story has you reassessing risk, income, or value, broaden your watchlist with a few focused screens that surface companies by the traits you care about most.
- For investors who want potential upside with strict attention to fundamentals, filter for companies that look attractively priced yet financially robust using our 33 high quality undervalued stocks.
- If resilience matters more than excitement, narrow your search to businesses that score well on stability and risk using the 32 resilient stocks with low risk scores.
- For those hunting for lesser known opportunities with solid underpinnings, scan through our 20 high quality undiscovered gems to see which stocks make the cut.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com