
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Norwegian Cruise Line Holdings (NCLH) Dropped, What Is Behind The Fresh Attention?
What triggered the latest focus on Norwegian Cruise Line Holdings
Norwegian Cruise Line Holdings (NCLH) has landed back on investor screens after receiving a Zacks Rank 5 Strong Sell rating and facing lower earnings estimates, just as its new Great Tides Waterpark opens in The Bahamas.
Against that backdrop, Norwegian Cruise Line Holdings has seen pressure build on the chart, with the share price down 2.21% over the past day and 3.34% over the past week. This has contributed to a 90 day share price return that is lower by 22.66% and a year to date share price decline of 33.93%. Over a 1 year period, total shareholder return is lower by 34.39%, while the 3 year total shareholder return is positive at 10.82%. Taken together, these figures suggest that short term momentum is fading even as longer term investors have seen mixed outcomes.
Compare Norwegian Cruise Line Holdings with a hand picked group of travel and leisure businesses that also screen as potentially mispriced on earnings using our 33 high quality undervalued stocks
Norwegian Cruise Line Holdings now trades well below its recent levels, even as it adds new attractions like Great Tides Waterpark. Do you treat this pullback as an entry point, or wait for a cheaper ticket?
Most Popular Narrative: 46% Undervalued
Norwegian Cruise Line Holdings last closed at $15.05, while the most followed narrative pegs fair value nearer to $28.05. This puts the focus firmly on whether balance sheet repair and fleet upgrades can eventually close that gap.
The nearly US$20b fleet modernization program, including the retirement of five older ships and introduction of 16 new vessels through 2037, gives Norwegian Cruise Line Holdings substantial room to reallocate capacity toward products and itineraries with better ticket and onboard economics, which can support higher revenue per capacity day and improved operating margins.
See why 3 investors see Norwegian Cruise Line Holdings as 46% undervalued.
Result: Fair Value of $28.05 (UNDERVALUED)
Still, the bullish Norwegian Cruise Line Holdings story faces two clear hurdles: high leverage near six times EBITDA and management guidance for weaker net yields through early 2027.
Find out about the key risks to this Norwegian Cruise Line Holdings narrative.
Another View on Norwegian Cruise Line Holdings’ Valuation
The bullish narrative leans on future earnings and a higher fair value for Norwegian Cruise Line Holdings. A different lens comes from Simply Wall St's DCF model, which puts the value of future cash flows at $3.96 per share versus a recent price around $15.39. That points to a stock the model views as trading richly rather than cheaply, and it raises a simple question for you: Which matters more for your thesis, modeled cash generation or the earnings multiple story?
Look into how the SWS DCF model arrives at its fair value.
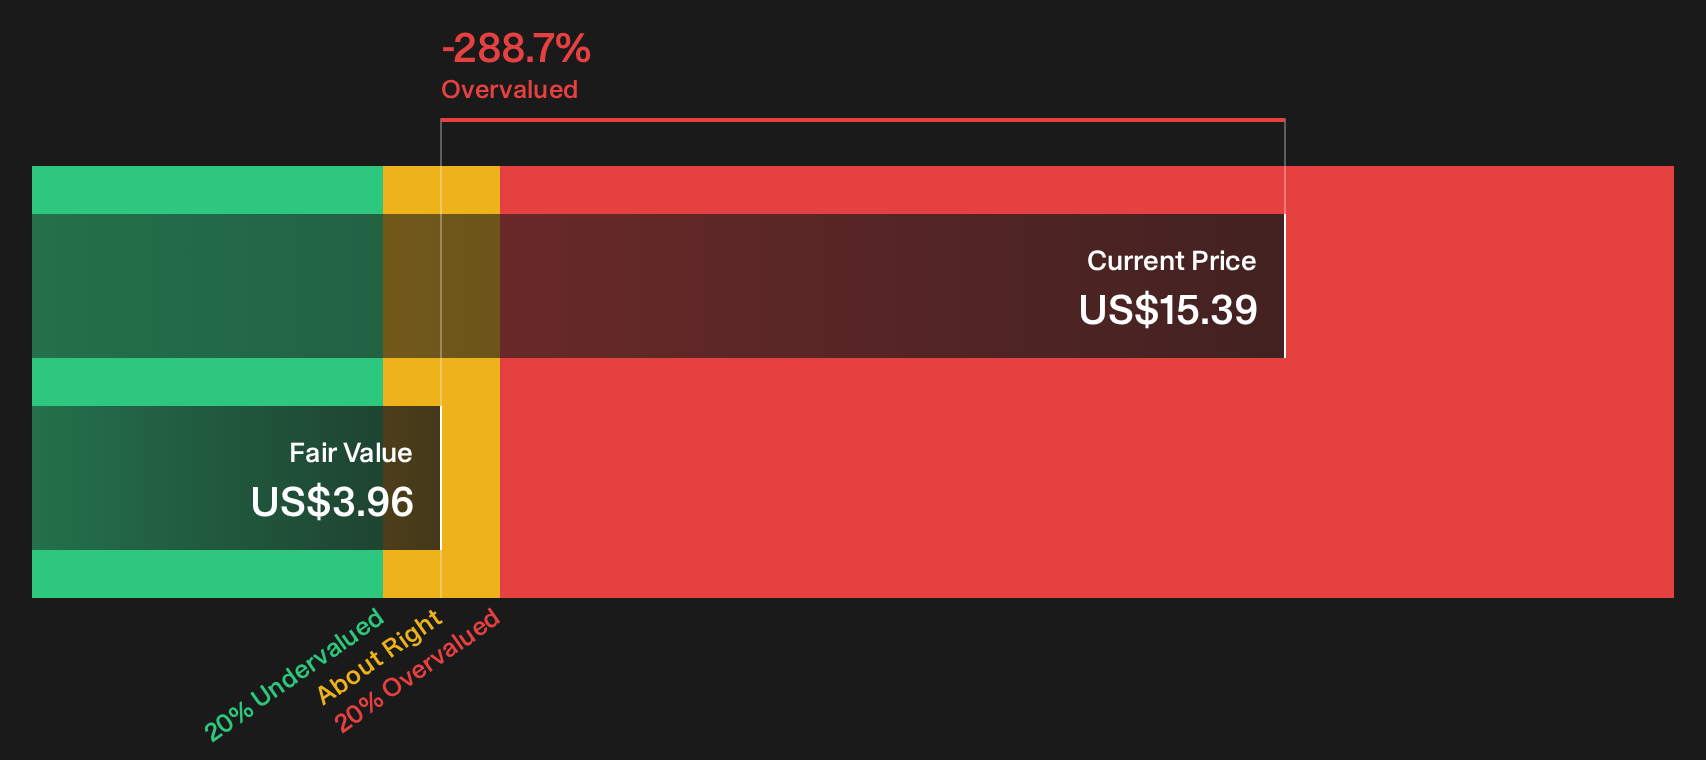
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Norwegian Cruise Line Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals keep circling Norwegian Cruise Line Holdings, which means the real work now is on you to weigh the upside against the risk. If you want a clearer view before acting, start with the balance of 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Norwegian Cruise Line Holdings?
You have weighed Norwegian Cruise Line Holdings. Now give yourself a broader watchlist with a few focused idea lists that can surface opportunities you might otherwise skip.
- Target dependable income streams by reviewing dividend payers screened as potential high yield fortresses through 7 dividend fortresses.
- Hunt for mispriced quality by scanning companies flagged as potential bargains on fundamentals using 33 high quality undervalued stocks.
- Prioritize resilience by checking businesses filtered for stronger balance sheets and healthier financial profiles in list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com