
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Slower US Same Store Sales Require Action From Domino's Stock Investors?
- Domino's Pizza reported Q3 2026 revenue of US$1,185.6 million and net income of US$152.18 million, with diluted EPS from continuing operations of US$4.60. The company also detailed nine month results, announced a US$1.99 quarterly dividend for December, and reported progress on a multiyear share repurchase program.
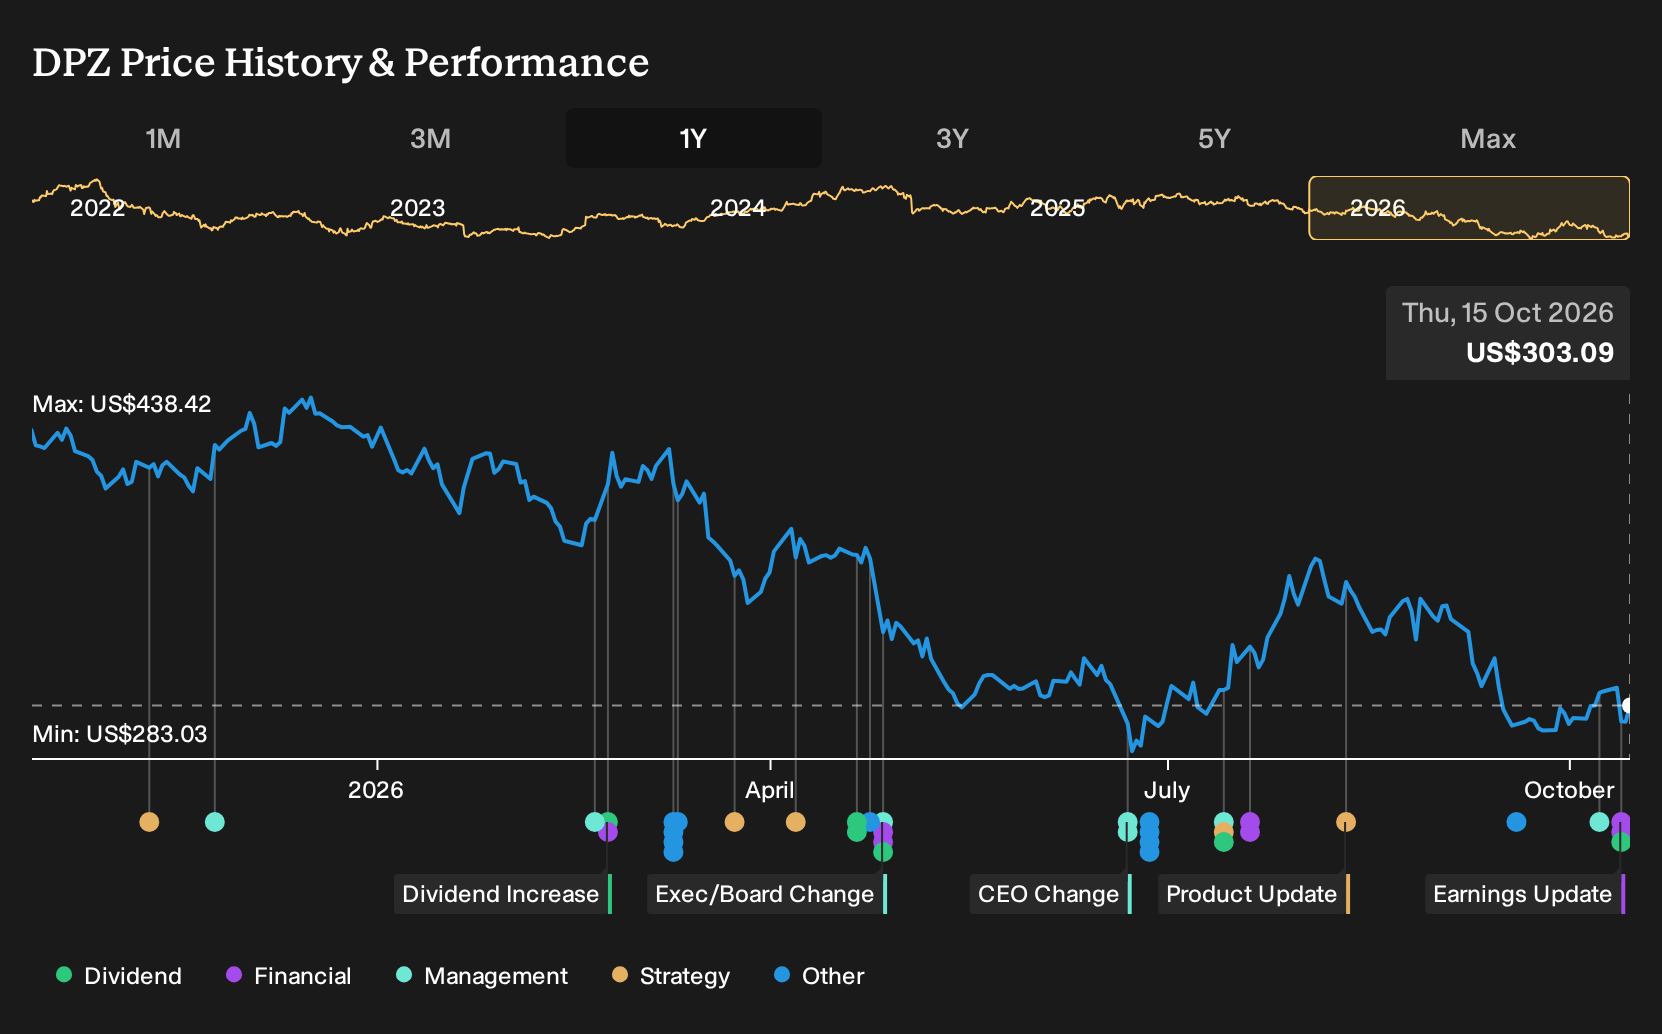
- Beneath the headline earnings beat, U.S. same store sales growth of 0.3%, trimmed domestic unit opening targets, and pressure on franchisee profitability point to a business leaning heavily on efficiency, digital reach, and capital returns, while demand and store level economics face meaningful strain.
- This analysis will examine how Domino's Pizza's investment narrative around digital reach and capital returns is being tested by softer U.S. same store sales.
Contrast Domino's Pizza's slower U.S. same store sales with other consumer stocks showing stronger momentum by scanning our hand picked 33 high quality undervalued stocks for ideas with sturdy demand and fundamentals.
Domino's Pizza Investment Narrative Recap
To own Domino's Pizza, you need to believe its digital reach, delivery focus, and dense store network can keep orders flowing even as value conscious customers trim baskets. The near term swing factor is whether U.S. same store sales can move off the recent 0.3% growth without eroding franchisee profits, which management says are under pressure.
The biggest risk sits at the store level. Franchise economics look tight, and guidance already reflects softer U.S. unit openings and low single digit comp expectations. If traffic stays skewed to smaller tickets while food and labor costs stay sticky, that mix can test both future expansion and margins.
The quarterly dividend affirmation of US$1.99 per share for December matters here because it signals Domino's Pizza is still committing cash to shareholders while franchisees work through weaker profitability. For income focused investors, that payout can be part of the appeal, provided it remains supported by earnings and cash generation.
At the same time, Domino's is running an active share repurchase program, with about 2,062,628 shares bought for roughly US$845.4 million under the 2024 authorization. Buybacks can soften per share earnings volatility and support P/E optics, but they also compete with other uses of capital, such as international expansion and supply chain investment.
Domino's Pizza's current earnings of US$596.5 million are projected by analysts to reach US$726.8 million by 2029. This implies about a 22% increase, supported by a forecast 3.4% yearly revenue growth rate and an outlook that envisions roughly US$5.6 billion in revenue and US$726.8 million in earnings in 2029.
Uncover why Domino's Pizza's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate storyline focuses less on Domino's Pizza’s digital reach and more on possible saturation. The most cautious analysts were modeling only 2.3% annual revenue growth and about US$5.4b of sales by 2029 before this report landed. That is a far more restrained view. Use this quarter’s numbers as a prompt to compare both narratives yourself.
Explore 5 other Domino's Pizza fair value estimates, including one that suggests as much as 8% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Domino's Pizza research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Domino's Pizza. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Domino's Pizza's overall financial health at a glance.
Looking For More Investment Ideas Beyond Domino's Pizza?
If this Domino's Pizza update has sharpened your view on the stock and its trade offs, you can use that same framework to assess other opportunities with cleaner balance sheets, steadier payouts, or different risk profiles.
- For investors who want businesses with room to grow but still trading at what could be appealing valuations, take a look at 20 high quality undiscovered gems that combine quality fundamentals with less crowded ownership.
- If capital preservation sits high on your list, focus on resilience first and growth second by scanning a curated 32 resilient stocks with low risk scores that screens for sturdier balance sheets and lower overall risk scores.
- For readers who prefer a middle ground between stability and potential upside, consider using a list of solid balance sheet and fundamentals (25 results) as a starting universe and then layering on your own views about earnings power and valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com