
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Oil Stocks In Focus As Hormuz Risk Puts Integrated Producers Under Pressure
Oil just ripped back into triple digits and shipping risks around the Strait of Hormuz are rattling supply routes, which puts global integrated producers right in the spotlight again. Price spikes, refinery threats and shrinking inventories are reshaping where money could be made or lost. This article explains how that shock feeds through the value chain and highlights 3 integrated oil and gas companies that appear particularly exposed to this turmoil.
The three integrated oil and gas stocks below are only a starting sample, and the full screen surfaced 43 more large producers with equally detailed stories that are not covered here.
If you want to identify, compare and analyze potential high conviction opportunities across the full peer group, go straight to the Global Integrated Oil & Gas Producers screener.
Kosmos Energy (KOS)
Overview: Kosmos Energy is a US headquartered deepwater explorer and producer that taps offshore oil and gas fields across West Africa and the Gulf of America, giving investors direct upstream exposure to global crude prices.
Operations: Kosmos generates about $1.6b a year from exploration, development and production of oil and gas, with Ghana contributing roughly $835 million and further revenue from the Gulf of America, Mauritania/Senegal and Equatorial Guinea.
Market Cap: $1.6b
Within this integrated oil and gas peer group, Kosmos Energy is positioned as a high torque upstream play. Its deepwater barrels are linked closely to global benchmarks at a moment when supply disruptions and triple digit crude put pure producers under a brighter spotlight.
"Kosmos reported record Q1 2026 production, cut net debt by about 7% versus year-end 2025, raised its 2026 debt-reduction target to ~20%, and kept full-year capex discipline intact at about $350 million."
The real swing factor now is how one pressure point on its balance sheet shapes future pricing power and cash generation potential.
That balance sheet pressure point is exactly what the full narrative for Kosmos Energy unpacks, showing where Kosmos Energy could accelerate or stall as crude volatility bites.
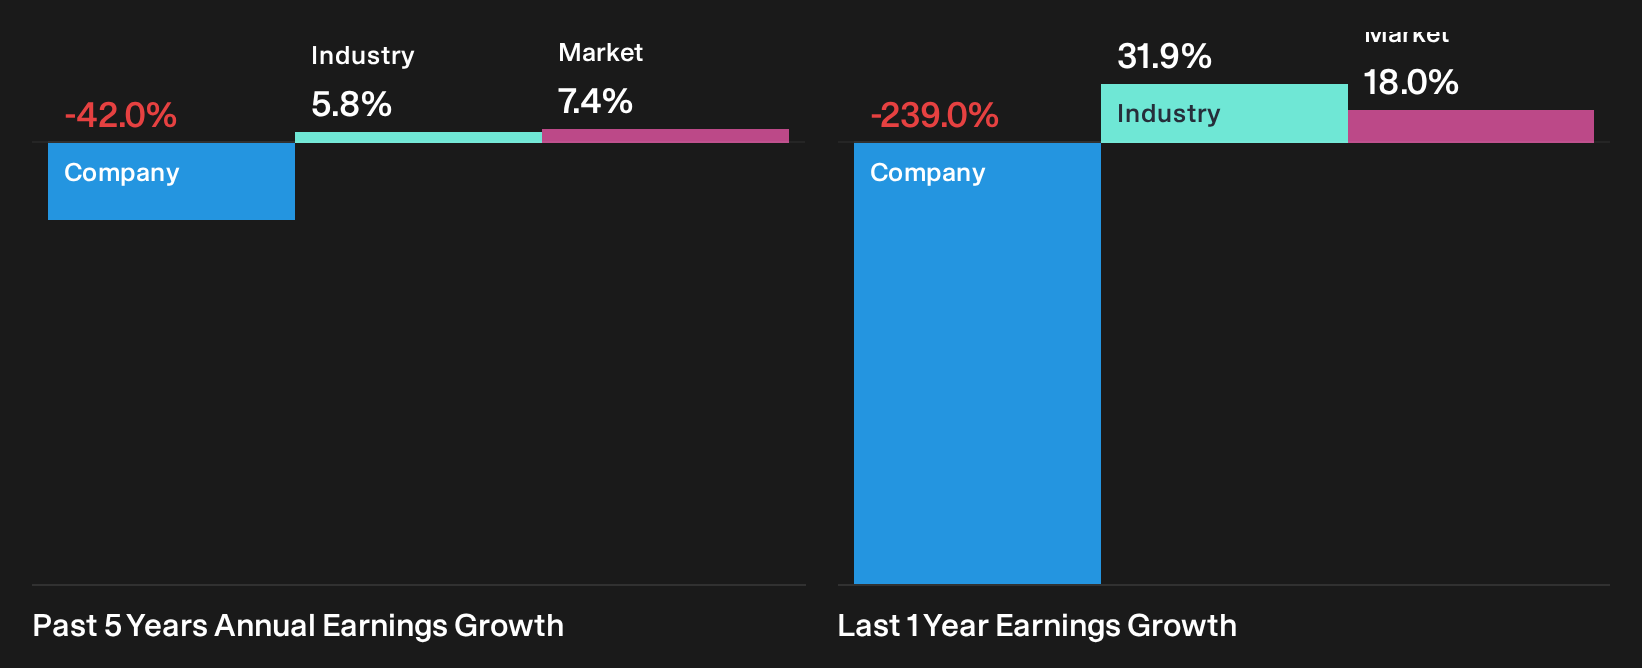
China Petroleum & Chemical (SEHK:386)
Overview: China Petroleum & Chemical runs a large, vertically integrated energy and chemicals platform in Mainland China, spanning exploration, refining, fuel retailing and petrochemicals.
Operations: The group records trillions of yuan in segment sales, with refining, marketing and distribution and corporate and others leading activity, mainly in Mainland China.
Market Cap: HK$735.9b
For an integrated oil and gas screen built around scale and full value chain reach, China Petroleum & Chemical provides that mix, tying crude production, fuel refining and consumer-facing stations together alongside a chemicals arm that reacts directly to shifts in global energy pricing.
"Rapid build out of sustainable aviation fuel projects, combined with direct airport access through the aviation fuel network, positions China Petroleum & Chemical to supply low carbon jet fuel that can become a higher margin product mix and support long term net margins."
What matters now is how a quiet change in where future demand comes from shapes the profit pool across this integrated system.
That profit pool shift is exactly what the full narrative for China Petroleum & Chemical unpacks, revealing how China Petroleum & Chemical could turn refining scale and new fuels into increasing cash generation potential.

Vista Energy. de (BMV:VISTA A)
Overview: Vista Energy. de is a Latin American oil and gas producer focused on developing shale resources in Argentina’s Vaca Muerta. This gives investors relatively pure upstream exposure to global crude prices.
Operations: Vista Energy. de generates about $3.5b in revenue from exploration and production of crude oil, natural gas and LPG.
Market Cap: MX$144.2b
Vista Energy. de brings the Global Integrated Oil & Gas Producers screen closer to the wellhead. It provides a focused way to think about how higher Brent pricing might filter through to upstream cash flow at a time when most headlines are about refining outages and shipping choke points.
"Expansion of well connections in core areas like Bajada del Palo Oeste and La Amarga Chica, supported by a ready-to-drill inventory and recent acceleration in Q4 activity, points to a production profile that can support higher revenue and operating cash flow if commodity prices and well performance remain favorable."
What really moves the needle now is how a single cost and funding pressure point interacts with that volume growth when oil volatility is at its most intense.
If that funding pressure is on your mind, go straight to the full narrative for Vista Energy. de to see how Vista Energy. de balances cost risk with accelerating volume potential.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds, entry points shrink while the crowd chases what you spotted early. Scan these curated lists while it still matters and look for opportunities before they attract wider attention.
- Look for cash-generating outliers that balance growth with resilience by running the 33 high quality undervalued stocks before they are widely noticed by momentum-focused traders.
- Track infrastructure suppliers involved in AI buildouts through the 55 AI infrastructure stocks while they remain less widely followed and before expectations change.
- Identify miners that could be affected if demand changes by screening the 17 top copper producer stocks and evaluating them before more capital flows into the theme.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com