
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Floor And Decor Holdings (FND) Stock Looks Above Fair Value Today
Floor & Decor Holdings has seen its share price fall sharply in recent years, which naturally puts the spotlight on whether the current valuation is still supported by its earnings power. With the stock under pressure, the key issue is how much of the business performance, and any future profitability, is already reflected in the price.
- Over the past 5 years the share price has declined 66.1%, which raises the question of how the market is weighing Floor & Decor Holdings' earnings against longer term expectations.
- The business model relies heavily on converting sales into consistent profits and cash flows, so any shift in store level profitability or capital spending plans can influence how sustainable its earnings base looks today.
- The analysts covering Floor & Decor Holdings have run their own numbers. See what analysts think Floor & Decor Holdings's shares could be worth.
The issue now is whether the current share price is justified by the earnings that Floor & Decor Holdings is generating and is expected to generate.
If you are weighing Floor & Decor Holdings against other opportunities that focus on valuation and quality, it helps to compare it with 33 high quality undervalued stocks.
Has Floor & Decor Holdings Run Too Far on Earnings?
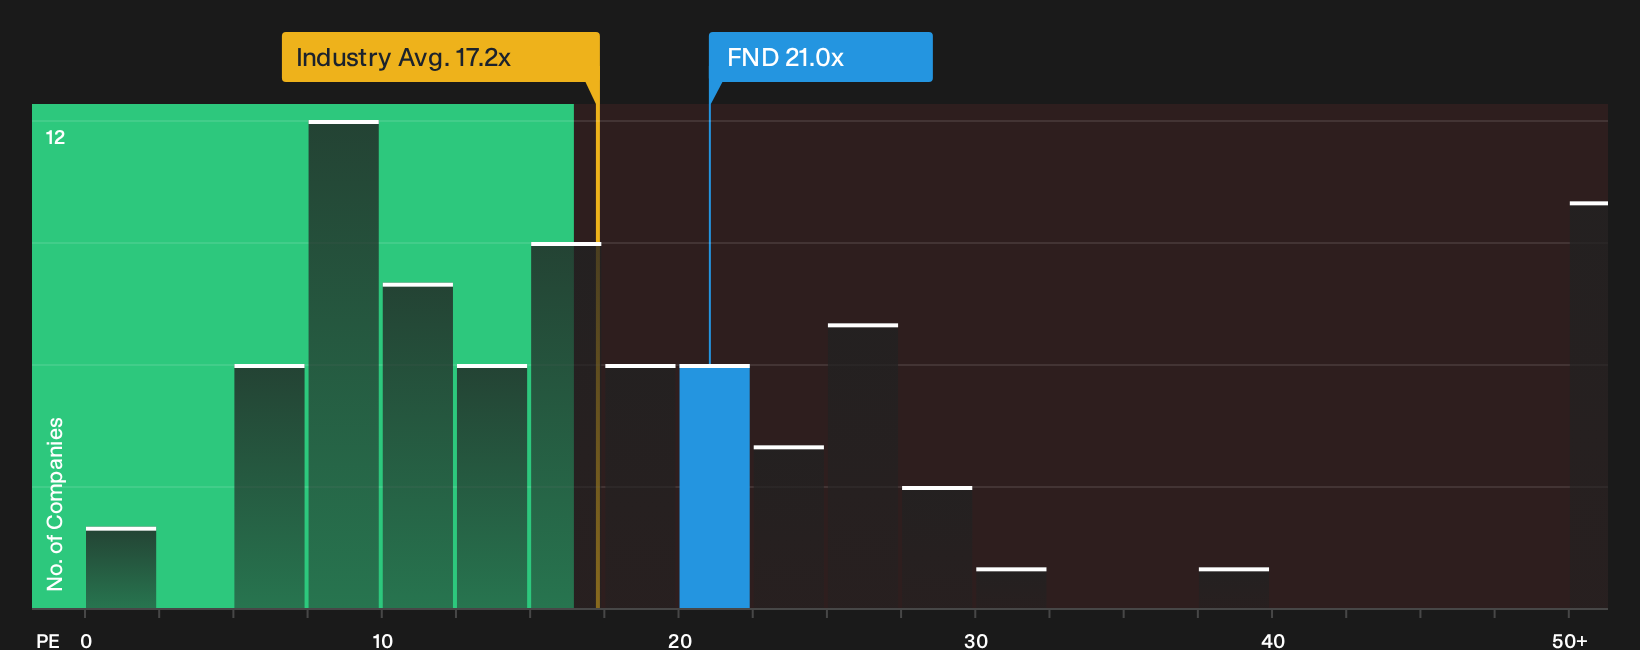
The P/E ratio suits Floor & Decor Holdings because earnings are a key hook for how investors value a retailer that reinvests heavily in its store base. On this metric, the stock trades on a P/E of about 21.0x, which is higher than the Specialty Retail industry average of roughly 17.2x and above similar peers near 11.4x. That gap indicates the market is willing to attach a richer tag to each dollar of current earnings than it does for many competitors.
A fair value framework that blends the company’s growth profile, margins, size and risk points to a lower multiple than where the shares change hands today. On this lens, the current P/E screens as overvalued. For anyone assessing Floor & Decor Holdings, the key question is whether its earnings quality and long term store economics justify paying this premium multiple, or whether it makes more sense to look for a closer fit to the implied fair level. Explore the numbers behind Floor & Decor Holdings's P/E valuation.
The Floor & Decor Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Floor & Decor Holdings pick up where the valuation puzzle leaves off. They spell out which earnings, margin and growth paths would need to hold for the shares to look meaningfully cheaper or more expensive than today. Each scenario frames Floor & Decor Holdings' implied worth as a specific thesis about how the business might progress, which investors can track over time to see whether it still fits the facts.
Community views on Floor & Decor Holdings split around how much value is left once the store rollout, Pro focus and digital spend are all factored in.
Bull case: 22% undervalued
"The evolution toward a more capital efficient footprint, with average new store costs declining from roughly US$11.7 million in 2023 to about US$10.2 million for the 2025 class and an expected US$7.5 to 8.0 million in 2026, together with infill locations in denser markets, creates room for higher returns on invested capital and more free cash flow…"
Discover why this Narrative puts Floor & Decor Holdings at 22% undervalued.
Bear case: 13% overvalued
"New distribution centers in Seattle and Baltimore are expected to weigh on gross margin by about 70 to 100 basis points in FY25 and FY26 as they ramp…"
Explore why this Narrative puts Floor & Decor Holdings at 13% overvalued.
One more Floor & Decor Holdings check that belongs beside the share price
Price tags and earnings multiples only tell part of the story, because the people deciding where to invest each dollar and how they are rewarded can tilt long term outcomes in subtle but powerful ways. See who runs Floor & Decor Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com