
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Top Growth Stocks With Earnings Growth Over 18%
Gas prices jumped 9.1% in a single month and pushed US inflation to 3.7%. That kind of move reminds investors how quickly costs can bite into household and business budgets. Companies that can still grow profits in a tougher backdrop and keep their finances in reasonable shape start to look scarce. This article breaks down three such high growth candidates from our screener and explains why they deserve a closer look now.
The three stocks highlighted here offer a compelling starting point if you want exposure to healthy high growth potential businesses that still keep their finances in check. However, if you want the absolute best, these 488 best high growth potential stocks are the cream of the crop.
Kingboard Laminates Holdings (SEHK:1888)
Overview: Kingboard Laminates Holdings produces glass epoxy and paper laminates, plus key upstream materials, for global printed circuit board and electronics manufacturers.
Operations: Around HK$25.5b of revenue comes from laminates, while rental properties and investments contribute roughly HK$82 million and HK$130 million respectively.
Market Cap: HK$124.4b
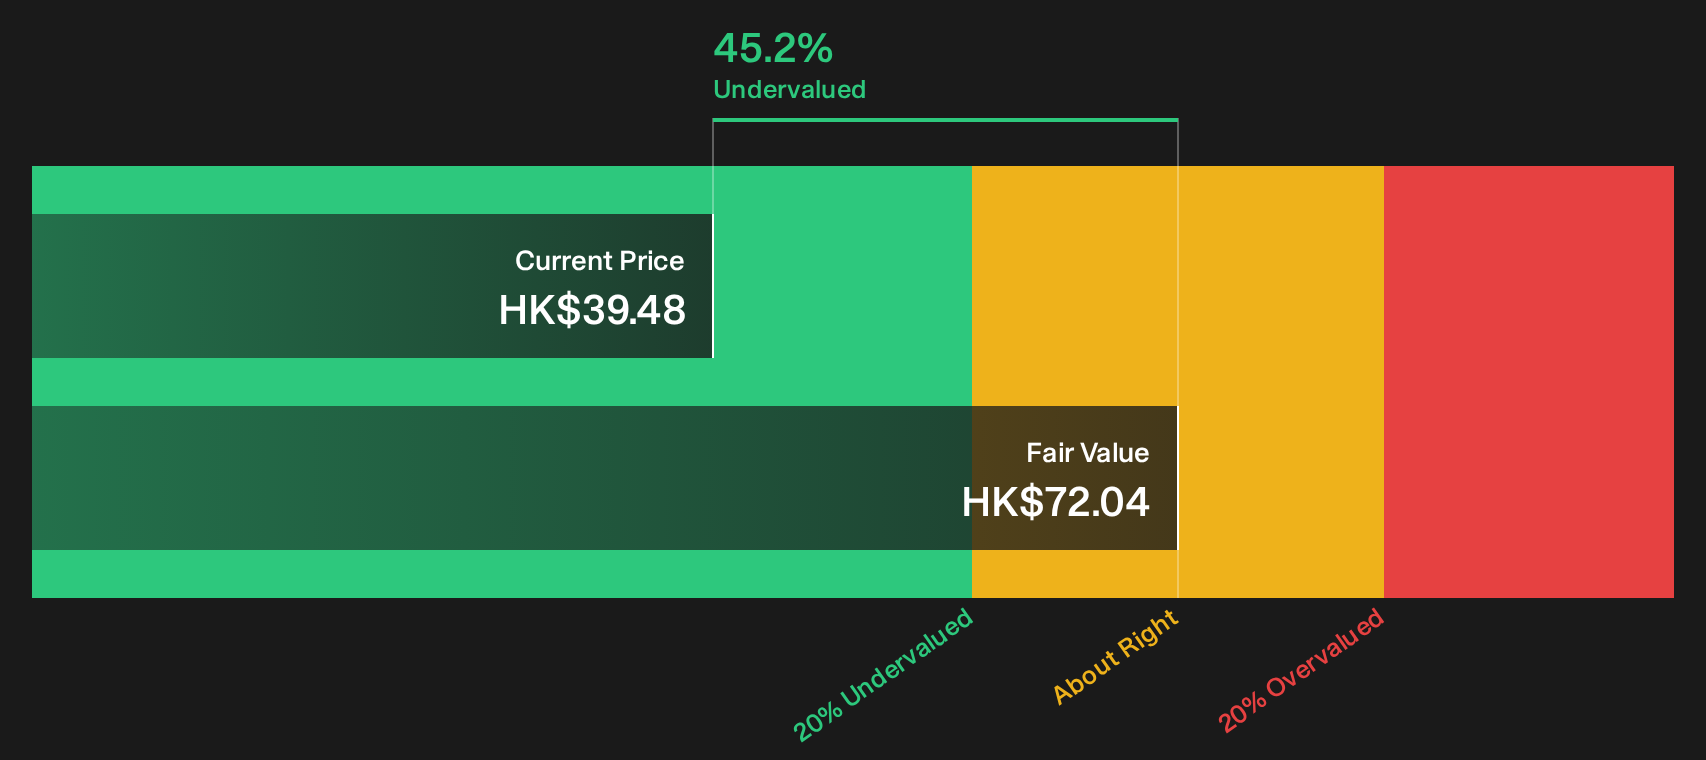
Kingboard Laminates links tightly to the Healthy high growth potential theme because its laminates and electronic materials are used directly in PCB and electronics demand. The share price sits below some fair value estimates, which depends on how one currently unseen pressure develops.
If you want to see how that pressure is priced in, start with the 3 key rewards and 2 important warning signs (1 is major!) while sentiment still seems to underappreciate the full story
Sandisk (SNDK)
Overview: Sandisk develops flash based SSDs and embedded NAND storage that power data centers, cloud services, and connected devices worldwide.
Operations: Sandisk generates about $20.2b from developing, manufacturing, marketing, and selling data storage devices and NAND based solutions globally.
Market Cap: $205.5b
What really links Sandisk to the Healthy high growth potential theme is how its flash storage supports rising AI, cloud, and edge workloads that demand reliable, high capacity NAND.
"Rapid AI and cloud workload expansion is driving data center NAND exabyte growth at a pace well above overall supply. This positions Sandisk's enterprise SSD portfolio and deepening hyperscaler engagements to support sustained revenue acceleration and structurally higher pricing power."
The key question now is how long that tight supply backdrop can stretch before it starts to reshape pricing, margins, and growth expectations.
That turning point is exactly what the full narrative for Sandisk unpacks, revealing how accelerating demand, supply swings, and capital intensity could reshape Sandisk's risk reward profile.

Technoprobe (BIT:TPRO)
Overview: Technoprobe designs and manufactures probe cards and electronic test interfaces that help chip makers check advanced semiconductors for high growth markets.
Operations: Technoprobe generates about €766.6 million from semiconductor equipment and services, with revenue concentrated in Asia and America.
Market Cap: €17.9b
Technoprobe matters for the Healthy high growth potential theme because its chip testing hardware sits directly in the path of rising semiconductor complexity and the ongoing build out of AI, 5G, and data center infrastructure.
"Although Technoprobe is expanding capacity toward an annual run rate of about €1.6b by early 2027, a scenario where customer ramps normalize more slowly could leave parts of this enlarged footprint underutilized and pressure EBITDA margins."
What really shapes the Technoprobe story now is how a single shift in demand intensity could feed straight through to profitability and growth expectations.
That profit sensitivity cuts both ways, and the full narrative for Technoprobe shows how Technoprobe could turn capacity risk into accelerating upside if demand snaps back harder than the market expects.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities do not sit still. Breakout stories gain momentum, under the radar for now, then get caught quickly once the crowd arrives. Scan these curated ideas and consider your options early.
- Spot income workhorses with reliable payouts by reviewing carefully filtered 212 dividend fortresses before yields compress and prices move away from ideal entry ranges.
- Target future-facing infrastructure by scanning the curated 55 AI infrastructure stocks while investor attention is still dropping the ball on these behind the scenes beneficiaries.
- Track real asset resilience by assessing hand picked 36 elite gold producer stocks before renewed momentum pulls these producers higher and the easy diversification benefit fades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com