
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Earnings Mix Just Shift Cohen & Steers (CNS) Investment Narrative?
- Cohen & Steers reported Q3 2026 revenue of US$157.43 million and net income of US$42.24 million, with basic EPS from continuing operations at US$0.82.
- The firm delivered stronger revenue than analysts expected, while adjusted EPS slightly trailed forecasts, highlighting tension between top line momentum and earnings efficiency.
- We will now look at how Cohen & Steers' strong revenue but softer earnings per share shapes the broader investment narrative.
Compare Cohen & Steers' latest earnings rhythm with a hand-picked group of high quality peers using our 33 high quality undervalued stocks built for investors who care about both fundamentals and price.
Cohen & Steers Investment Narrative Recap
Cohen & Steers appeals to investors who believe real assets can keep attracting capital and that a focused specialist can convert that interest into steady fees. The Q3 2026 update showed solid revenue and net income alongside only modest movement in earnings per share, so the short term story still hinges on funding its institutional pipeline and keeping flows positive.
The biggest swing factor remains whether client inflows can offset any reallocations away from real estate and other real assets. On the risk side, expenses tied to product expansion and distribution remain important to watch. This quarter’s results do not materially change that balance between flow momentum and cost discipline.
The Manchester Village acquisition through Cohen & Steers Income Opportunities REIT is the announcement that ties closest to the wider earnings story. It illustrates how the group is trying to grow fee bearing assets in income oriented, necessity retail properties, which fits the broader push into listed and private real estate solutions.
For shareholders, the operational question is execution. Management needs these new properties and joint ventures to contribute stable cash flows without inflating operating costs in a way that compresses margins. In that context, the REIT expansion supports the real assets catalyst while also adding another asset level project that investors should monitor for leasing, occupancy and funding outcomes.
Cohen & Steers Forecasts and Valuation Setup
Cohen & Steers sits in a spot where analyst expectations are clear on paper, even if execution risk remains real. Forecasts point to revenue rising at 6.1% per year over the next three years, with profit margins moving from 28.8% today to 31.3% by 2029 if things track to plan. That margin shift underpins the move in forecast earnings from US$168.3 million now to a consensus of US$218.4 million and a P/E assumption of 23.2x on those later profits, compared with 21.5x today.
Cohen & Steers' narrative projects US$698.4 million revenue and US$218.4 million earnings by 2029. This assumes 6.1% yearly revenue growth and about US$50 million earnings increase from current earnings of US$168.3 million.
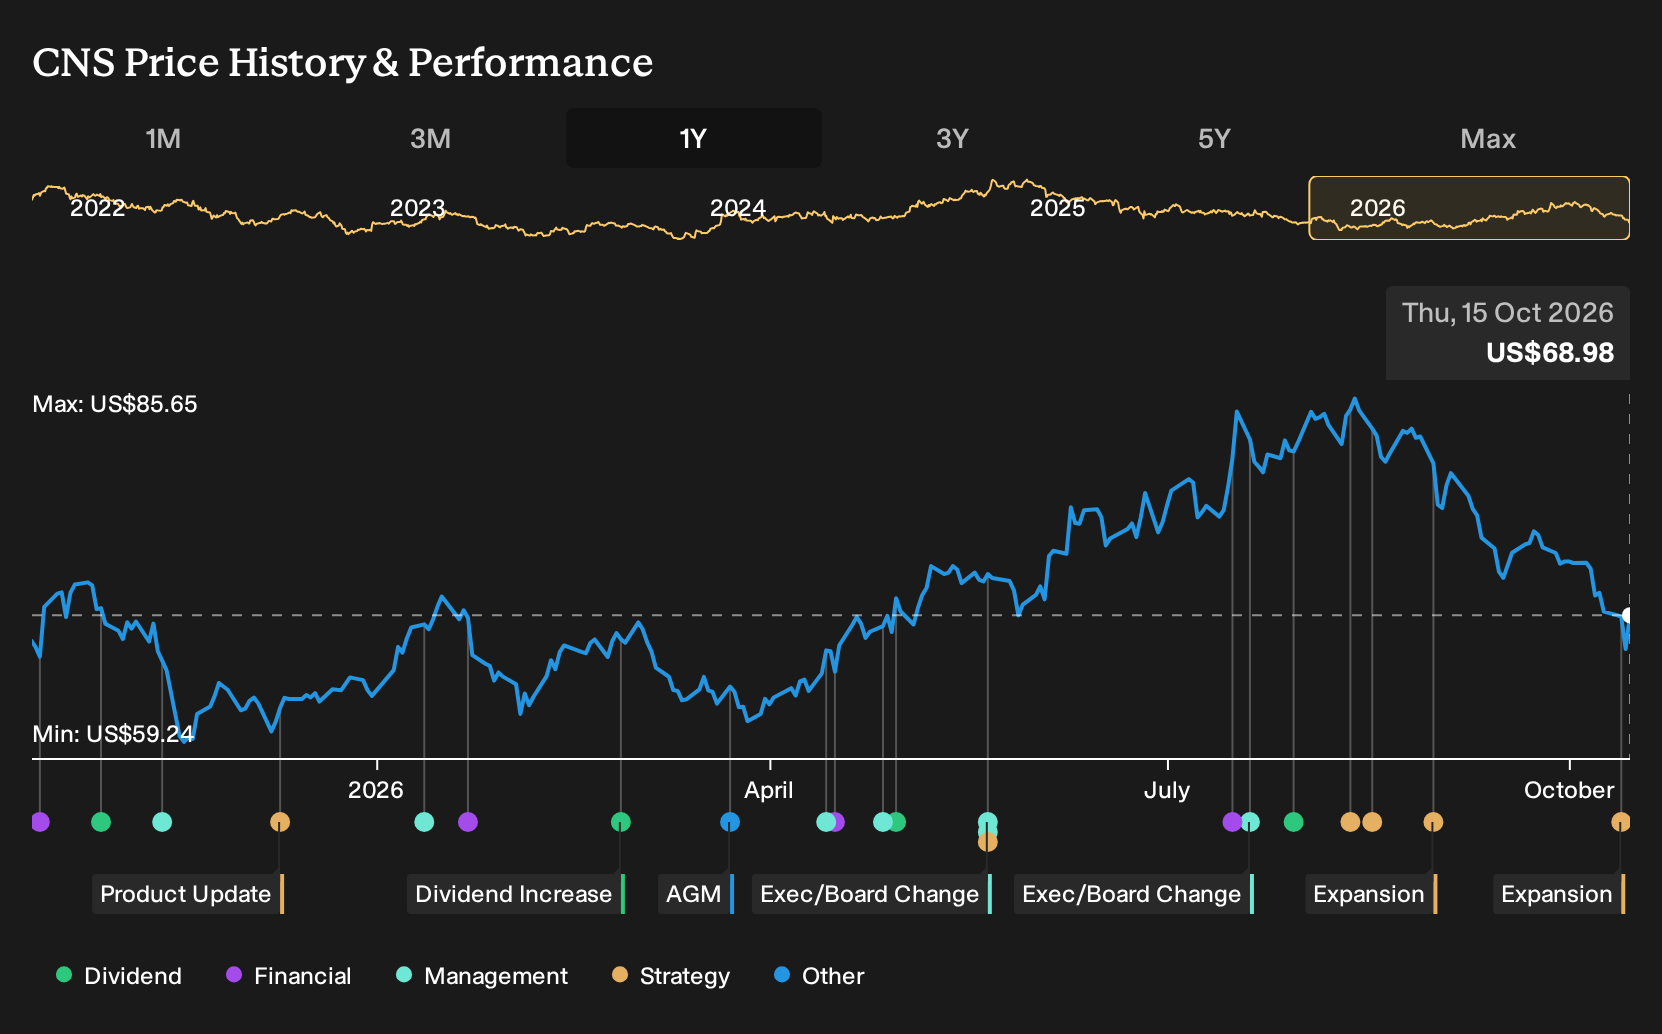
Uncover why Cohen & Steers' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate narrative focuses on the unfunded institutional pipeline as the real swing factor. The most optimistic Cohen & Steers analysts were modeling roughly US$707.1 million in 2029 revenue and US$223.1 million in earnings before this Q3 report. You can read this quarter’s revenue beat and softer EPS and decide whether that pipeline now looks more or less convincing.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Cohen & Steers research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cohen & Steers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cohen & Steers' overall financial health at a glance.
Looking for more investment ideas beyond Cohen & Steers?
If Cohen & Steers has sharpened your thinking about income, risk and valuation, now is a good time to scan a wider opportunity set and see how other businesses stack up on the same fundamentals.
- If your priority is resilient balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that filters for financial strength and staying power.
- For readers hunting for mispriced quality, use our value focused tool built around 33 high quality undervalued stocks that pairs business strength with more modest valuations.
- Income focused investors can zero in on higher yielding candidates by running the 7 dividend fortresses, which keeps the spotlight on payout potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com