
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Has Metro Bank Holdings (LSE:MTRO) Run Ahead Of Profitability And Balance Sheet Strength?
Metro Bank Holdings (LSE:MTRO) has drawn fresh attention after analysts questioned whether its recent financial performance supports the current share price, putting the bank’s profitability and balance sheet quality under closer scrutiny.
Recent trading in Metro Bank Holdings has been choppy, with the share price giving up 6.7% over the past month, even after a 7.9% gain over the last week. Yet the year-to-date share price return of 40.0% and a 1-year total shareholder return of 52.0% point to momentum that is still intact over a longer stretch and reflect how investors have been reassessing both earnings power and perceived risk.
Compare Metro Bank Holdings with a curated group of peers that combine momentum with balance sheet strength by scanning the 4 resilient stocks with low risk scores alongside this latest move in the share price.
After a 40.0% year-to-date climb and a share price sitting close to analyst targets, the big tension around Metro Bank Holdings now is simple: Is meaningful upside still on the table, or has most of the rerating already played out?
Most Popular Narrative: 2% Undervalued
Metro Bank Holdings last closed at £1.67, which sits slightly below the most followed fair value estimate of £1.70 that uses an 8.7% discount rate to bring future earnings back to today. That small gap keeps the focus on whether the profitability story that underpins this narrative truly holds together.
The bank's ongoing asset rotation strategy, shifting runoff from low-yield residential mortgages toward higher yielding commercial and specialist lending with strong risk-adjusted returns and large addressable markets (SME/commercial, specialist mortgages), creates potential for sustainable top-line revenue growth and higher net interest margin.
Metro Bank's scalable, omni-channel platform and recent regional expansion, particularly outside London and into underserved urban centers, places it in a position to potentially benefit from urbanization and population trends in UK cities. This broadens the customer base and may increase deposit and lending volumes, supporting long-term revenue and loan book growth.
See why 14 investors see Metro Bank Holdings as 2% undervalued.
Result: Fair Value of £1.70 (ABOUT RIGHT)
Still, the Metro Bank Holdings story can change quickly if higher cost technology investment erodes margins or if riskier specialist lending hurts asset quality.
Find out about the key risks to this Metro Bank Holdings narrative.
Another View On Metro Bank Holdings: Earnings Multiple Risk
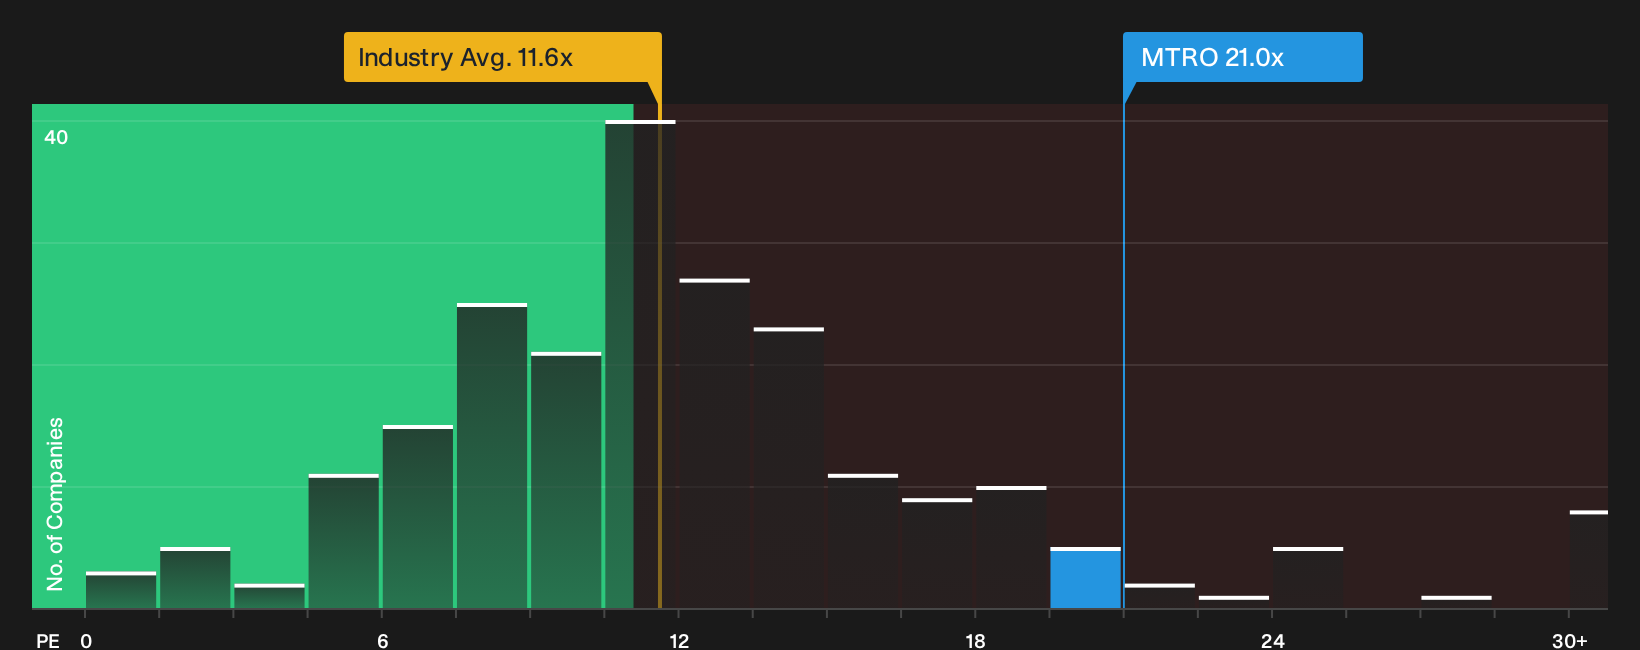
The earlier fair value of £1.70 paints Metro Bank Holdings as roughly in line with consensus expectations. A different lens tells a tougher story. The current P/E of 21x is far richer than the European banks average of 11.6x, a peer mark of 6.7x and even the fair ratio of 11.8x. That gap points to meaningful valuation risk if sentiment cools or forecasts are revised.
Investors who want to stress test this richer pricing against the underlying numbers can use the valuation breakdown as a cross check See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Metro Bank Holdings can make it hard to know what matters most, so move quickly, pull up the numbers, and decide where you stand using the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Metro Bank Holdings?
If Metro Bank Holdings has your attention, do not stop here. Use fresh watchlist ideas from the screener and give yourself more options.
- Target stability first by scanning a list of solid balance sheet and fundamentals (9 results) that can help you avoid fragile balance sheets that may affect long term returns.
- Hunt for mispriced opportunities through a 5 high quality undiscovered gems that highlights quality businesses the wider market may not be watching yet.
- Put income at the center of your plan by reviewing a 2 dividend fortresses that focuses on higher yielding companies with resilient payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com