
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Pinnacle West Capital (PNW) Nears Q3 Earnings, Is It Fully Priced?
Pinnacle West Capital (PNW) is back in focus as investors look ahead to its Q3 2026 earnings release on November 3, with analysts expecting $3.31 per share and updated full-year guidance already on the table.
Recent trading has been choppy for Pinnacle West Capital, with the share price down 5.71% over the past 90 days, but recording a 7.04% 1 month share price return and a 15.25% year to date share price return at US$101.58. The 5 year total shareholder return of 87.74% points to stronger longer term momentum.
Compare where Pinnacle West Capital sits today against a curated list of regulated utilities with resilient balance sheets and cash flows using our 32 resilient stocks with low risk scores.
The recent rebound in Pinnacle West Capital after a choppy quarter raises a simple tension. Are investors pricing in the regulated utility’s fundamentals, or just rotating sentiment ahead of earnings and a richer valuation check next?
Most Popular Narrative: 1% Undervalued
Pinnacle West Capital last closed at $101.58, compared with a widely followed fair value estimate of about $102.79 per share using a 7.24% discount rate. That small gap keeps attention on whether Arizona growth, capital spending plans and regulatory decisions are enough to support the current valuation range.
The multi year capital program of about US$7.95b for 2026 to 2028, including higher transmission spend and new gas capacity like Redhawk expansion, Agave, Ironwood, Sundance and the planned Cholla gas conversion, is set to increase the regulated asset base and future revenue.
Growing transmission investment, including the potential multi hundred mile Four Corners to Cholla line that could approach US$1b and is recovered through a FERC formula rate with annual true ups, creates an additional earnings stream that can support both revenue and net margins over time.
See why 11 investors see Pinnacle West Capital as 1% undervalued.
Result: Fair Value of $102.79 (ABOUT RIGHT)
Still, the narrative can quickly weaken if Arizona regulators take a tougher line on cost recovery or if heavier debt funding reduces returns from that US$7.95b capital plan.
Find out about the key risks to this Pinnacle West Capital narrative.
Another View: Cash Flow Says Something Different
The fair value story looks less comfortable when switching from earnings based estimates to the SWS DCF model. On this cash flow view, Pinnacle West Capital at $101.58 trades above an estimated future cash flow value of $89.39 per share, which frames the stock as overvalued on this particular metric.
For investors, that gap highlights a simple question: Are earnings based targets giving too much credit to Arizona growth and the capital plan, or is the cash flow model being too strict on future returns and funding costs?
Look into how the SWS DCF model arrives at its fair value.
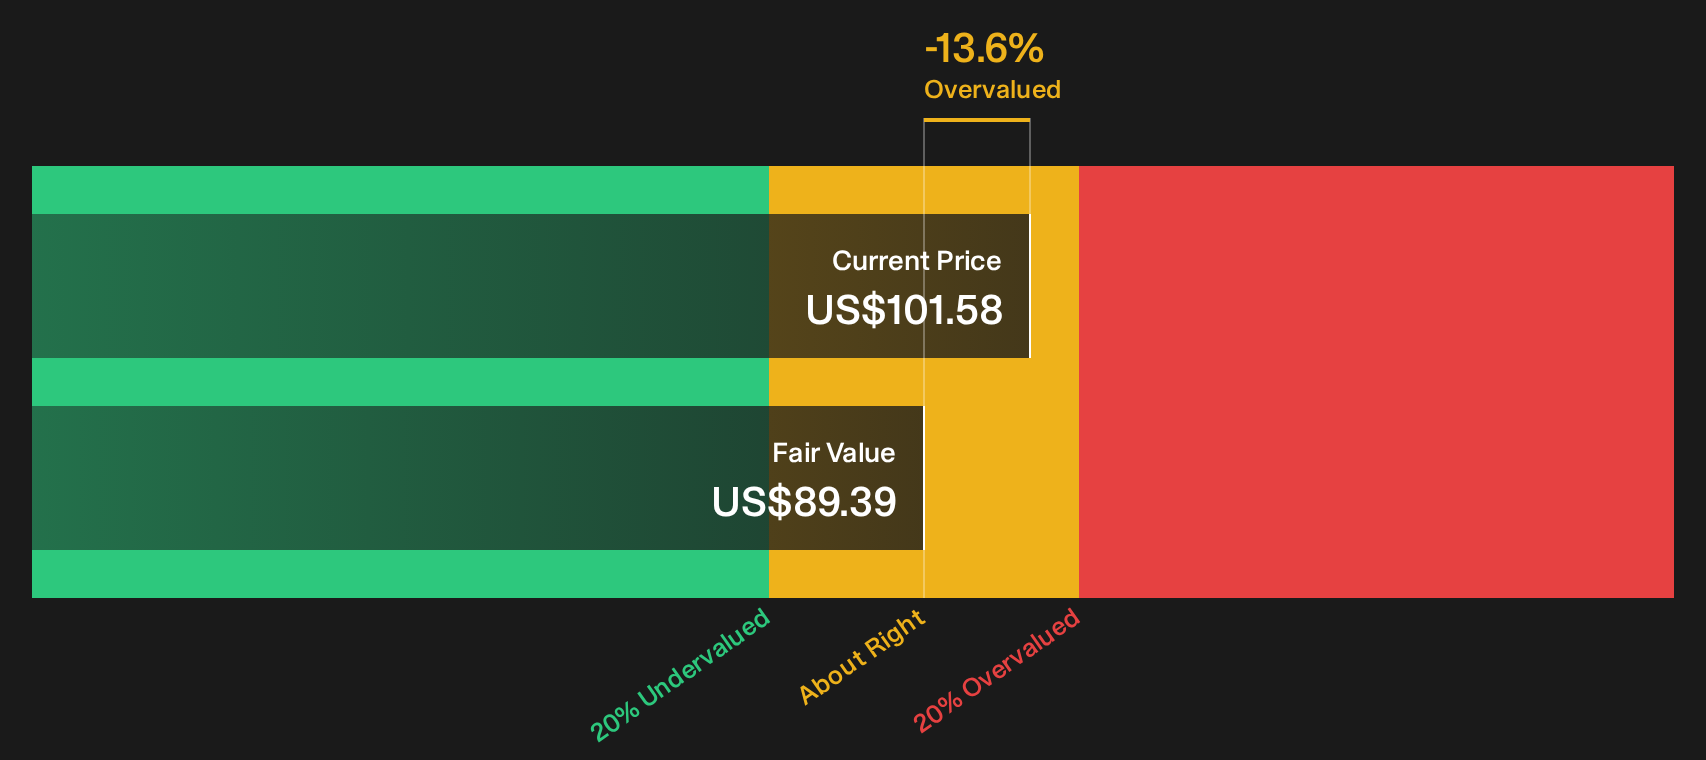
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pinnacle West Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Pinnacle West Capital so far. If you want to move quickly and rely on your own homework, start by weighing the 4 key rewards and 2 important warning signs.
Looking for more Pinnacle West Capital sized ideas?
If Pinnacle West Capital has you thinking more broadly about where to put fresh capital to work, do not stop with just one ticker on your list.
- Target dependable compounding by scanning our 7 dividend fortresses that focus on steady income potential backed by robust underlying businesses.
- Hunt for mispriced opportunities using the 20 high quality undiscovered gems, where strong fundamentals have not yet attracted wide market attention.
- Prioritise resilience first and filter for strength with a curated list of solid balance sheet and fundamentals (25 results) before committing your next dollar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com