
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Japanese Small Cap Stocks With ROE Up To 31%
Oil prices have been on edge after repeated attacks on tankers near the Strait of Hormuz, and that kind of supply scare often pushes big investors back toward familiar global giants. Smaller Japanese companies with solid finances can quietly get overlooked in the rush. That gap in attention is the opening. This article highlights three high quality Japan small caps from our research screen that fit this under the radar theme.
The three stocks below are just a sample from this theme. The broader screen surfaced 70 more small caps with similarly strong fundamentals and under followed stories that are not covered here.
If you want to identify your own potential leaders before they hit the upgrade lists, head straight to the High-Quality Undiscovered Gems screener to filter, analyze, and target the highest conviction ideas in this space.
Taiyo Holdings (TSE:4626)
Taiyo Holdings is a Tokyo based materials specialist best known for its electronics segment, which produces niche printed circuit board and functional film materials used by component makers. Electronics brings in about ¥101.1b of revenue, ahead of medical and pharmaceuticals at roughly ¥36.3b and other activities at ¥6.8b, giving a total scale backed by a market value of about ¥528b.
For this High Quality Undiscovered Gems theme, Taiyo Holdings hooks directly into small cap electronics through its specialty PCB and photoimageable materials, paired with a recent 148.7% earnings jump and 18.7% net margins. Interest grows when a premium 19.6x P/E and the potential for strong returns both hinge on how one unseen pressure resolves for those earnings.
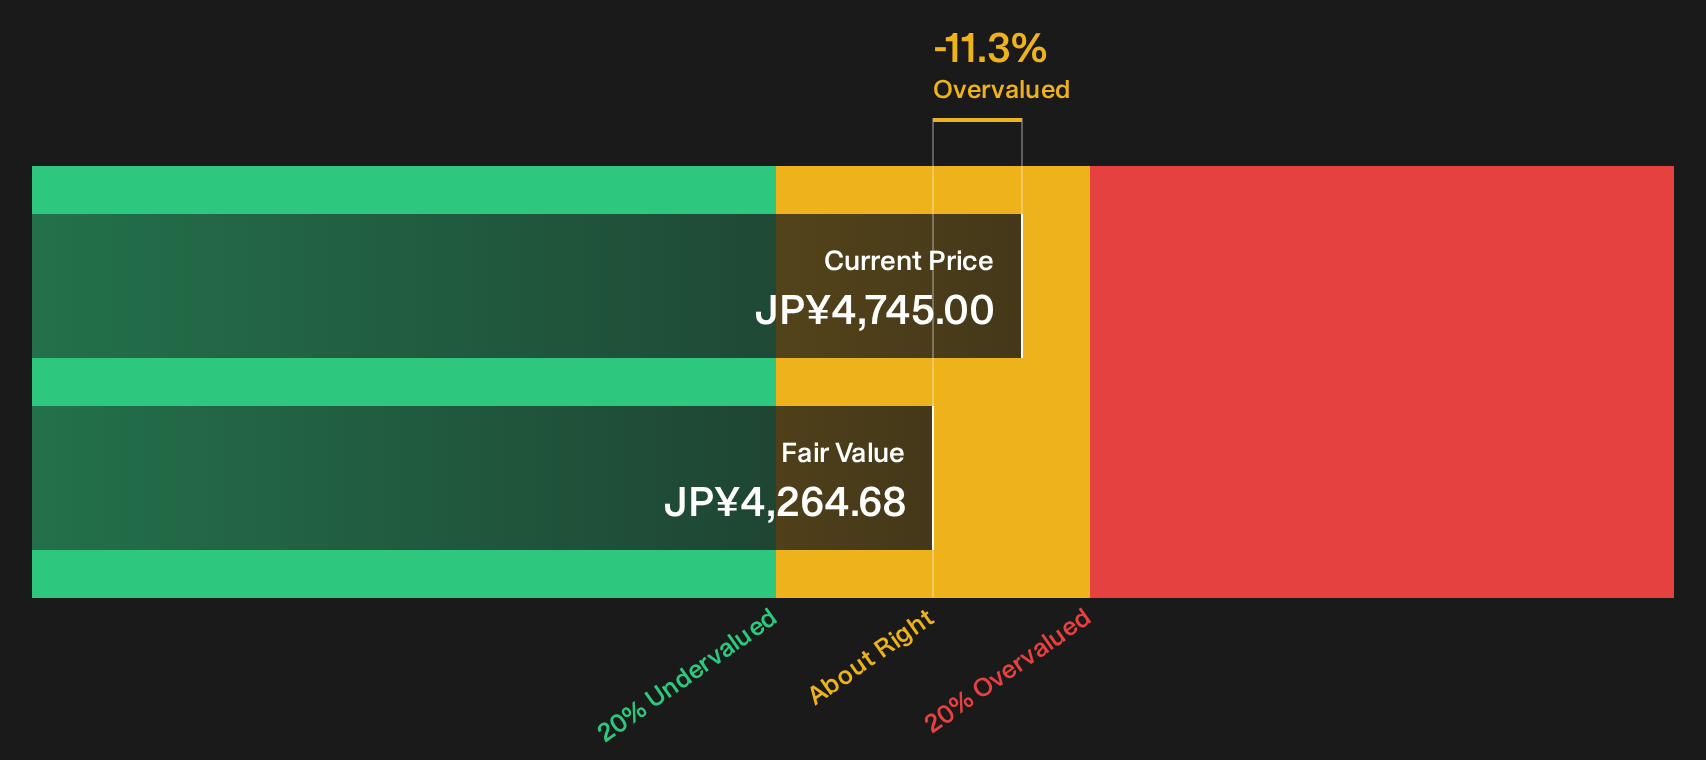
That pressure point is exactly what you can stress test in the DCF valuation analysis for Taiyo Holdings to see how much of Taiyo Holdings' earnings strength is already priced in.
Tsugami (TSE:6101)
Tsugami builds CNC precision lathes and machining centers that help electronics and telecom suppliers produce tiny, high precision parts. This is the direct link to this High Quality Undiscovered Gems theme. Most operating revenue comes from China at about ¥122.2b, with Japan contributing around ¥29.8b, and the business is valued at roughly ¥242.6b.
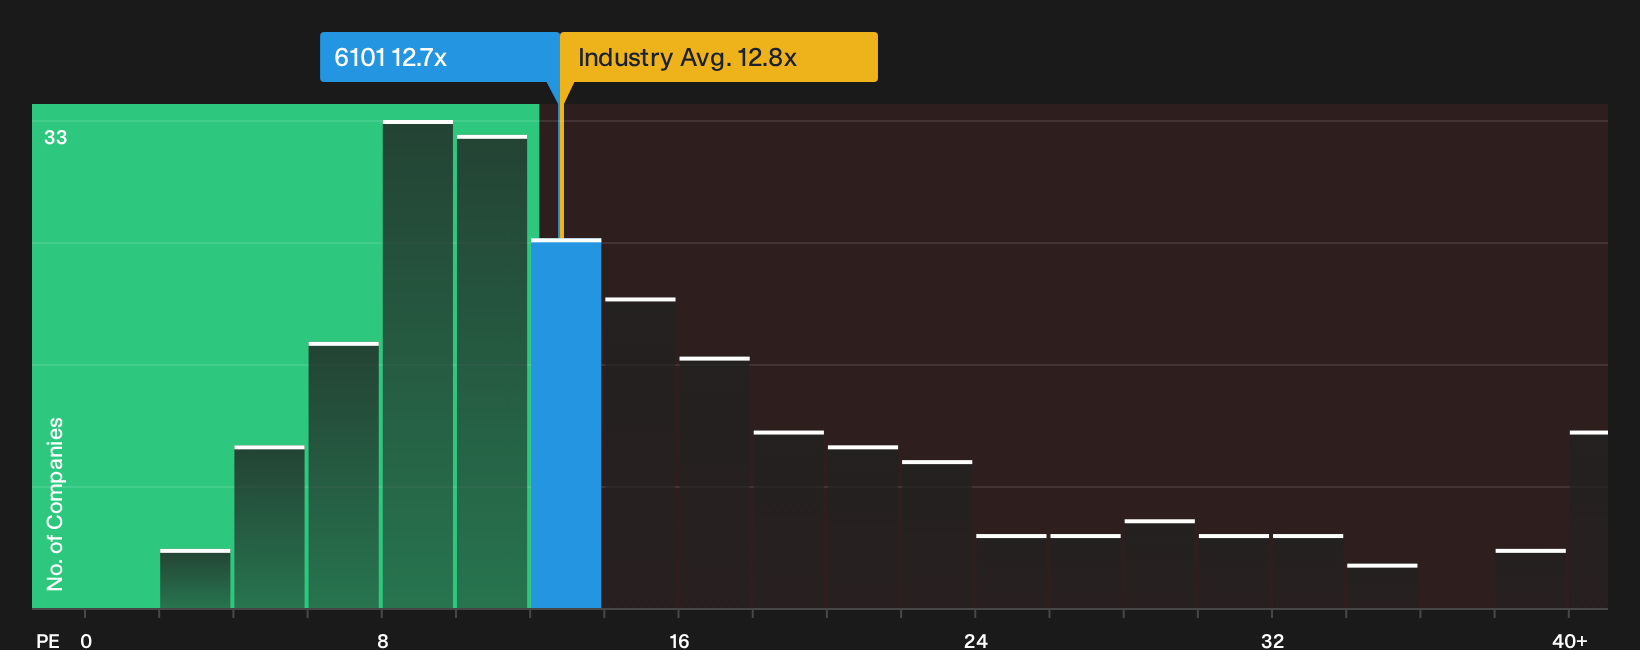
Tsugami aligns with this theme because its machine tools are core equipment for compact electronics and telecom components. The stock trades on a 12.7x P/E, carries 53.6% earnings growth and a 23.2% ROE, and offers a 1.87% dividend, while everything depends on how one shift in demand plays out.
That demand shift is exactly where the 3 key rewards and 1 important warning sign could reveal whether Tsugami's setup is quietly compounding strength or masking a fragile cycle.
santec Holdings (TSE:6777)
santec Holdings develops optical measuring instruments and components for fiber networks and sensing, with optical instruments bringing in about ¥25,276 million, components about ¥6,461 million, and other products ¥2,939 million. This small cap, valued near ¥242.5 billion, fits the High Quality Undiscovered Gems theme through its telecom focused optics.
santec Holdings lines up with this screener because it couples 85.5% earnings growth and a 31.2% ROE with telecom grade optics that big funds can easily skim past. The 27x P/E multiple reflects expectations that the current earnings trend and margins will be sustained, while also highlighting the impact that changes in underlying pressures on the business could have on profitability.
Those pressure points matter for santec Holdings, so head to the 2 key rewards and 1 important major warning sign to see whether current expectations are masking fragility or underappreciated strength.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first, and slow research often gets caught chasing breakouts after momentum is already flying. Check new screens under the radar for now and act now.
- Track cash rich compounders before the crowd filters for safety and upside through the list of solid balance sheet and fundamentals (21 results) while the best entries are not yet crowded.
- Ride potential income momentum by reviewing the 29 dividend fortresses so you spot high yield payers while prices are steady and yields have not dropped.
- Position ahead of the next infrastructure breakout by scanning 41 power grid technology and infrastructure stocks while these grid and electrification plays are still flying under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com