
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Weak Broadband Demand Will Impact Comcast (CMCSA) Investors
- Comcast expanded Xfinity and Comcast Business high speed internet to nearly 2,000 locations in Hardee County, Florida, bringing multi gigabit fiber, mobile, TV, and security services to more than 1,300 homes and businesses that previously lacked broadband access.
- The buildout highlights Comcast’s push to invest in new fiber coverage, even as the broader broadband unit faces weak demand, rising competitive pressure, and a projected squeeze on free cash flow margins.
- The next question for investors is how Comcast’s investment narrative will incorporate these fiber expansions while managing soft broadband demand and intensifying rivalry.
Comcast Investment Narrative Recap
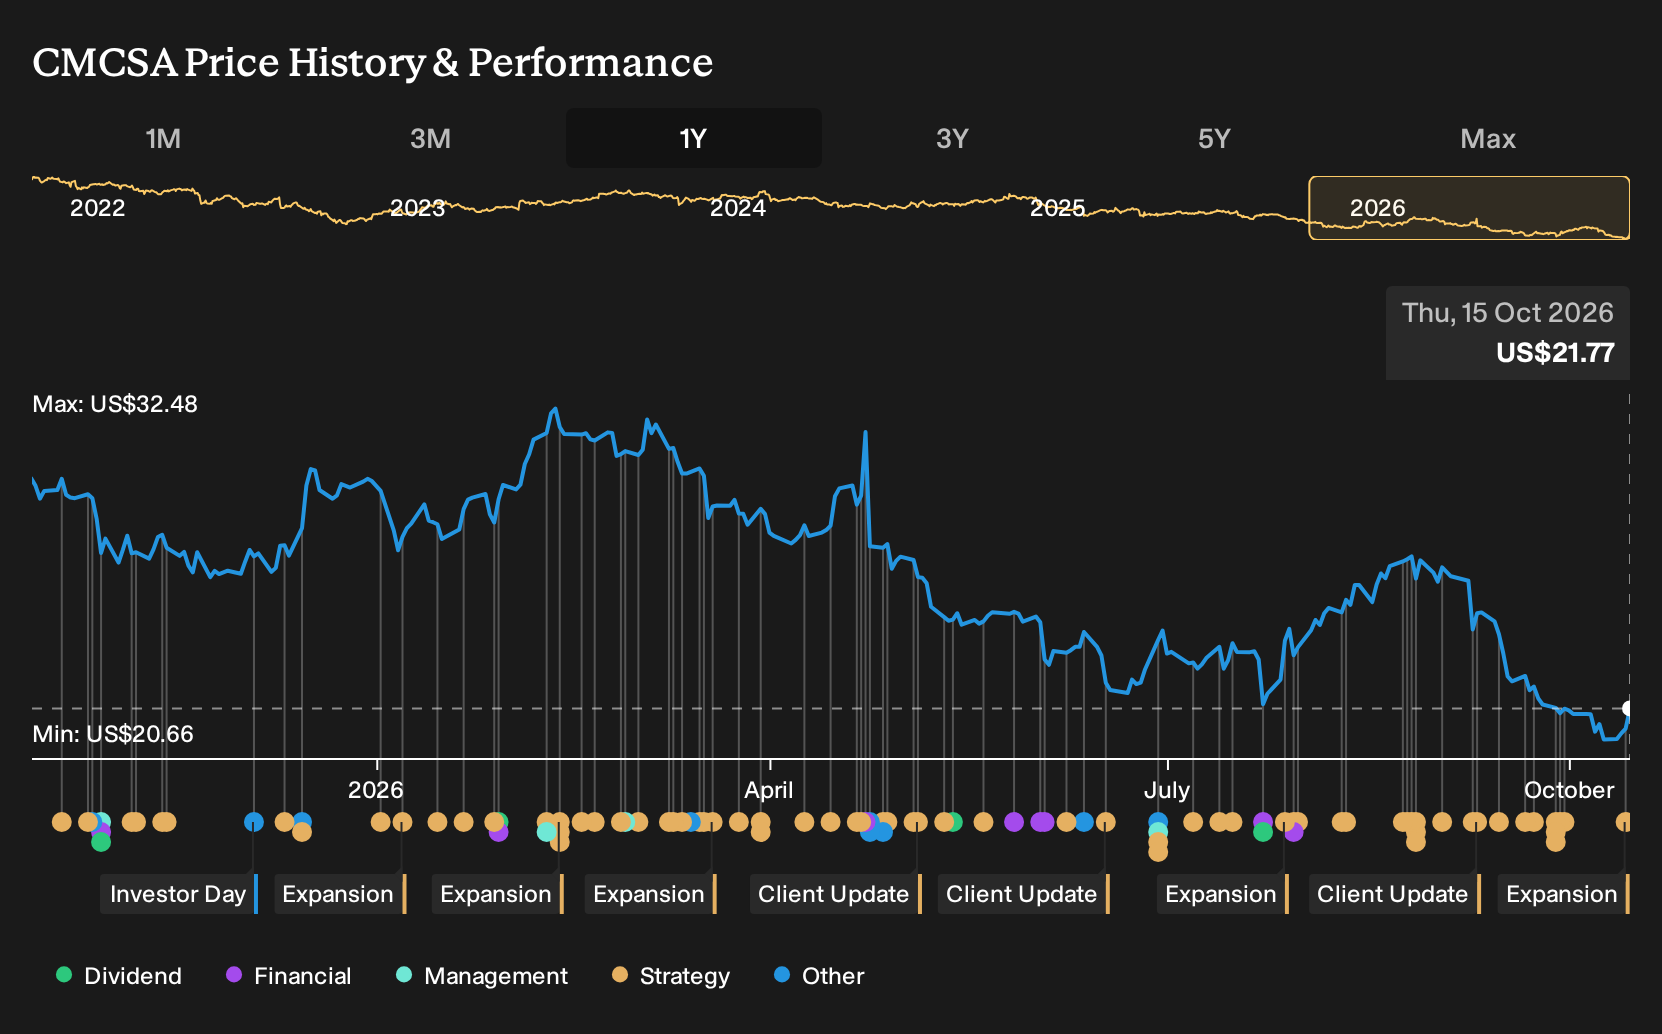
For Comcast, the core belief is that connectivity, wireless, streaming and parks can still generate solid cash over time, even while broadband growth is sluggish and competition is heavy. The near term story is tougher. Domestic broadband demand is soft, returns on capital have eroded and higher network spending is expected to compress free cash flow margins.
The key short term catalyst is how the next earnings reports frame this heavier spend against weaker broadband trends and rising rival offers. Hardee County is small in group terms, so the Florida expansion does not materially change near term risk, which still sits with broadband pressure and theme park softness.
The Hardee County buildout fits into Comcast’s wider push on DOCSIS 4.0, multi gig speeds and converged bundles. These projects keep the network competitive against fiber, fixed wireless and satellite providers that are putting real pressure on broadband pricing and ARPU. Investors are watching whether this spending helps stabilise subscriber trends.
Another closely watched catalyst sits in Experiences. Epic Universe and the broader Universal pipeline offer longer term capacity upside, but near term park earnings remain exposed to weaker Chinese visitation and softer Orlando trends. In that context, each new capex heavy project, such as the Florida connectivity rollout, sharpens the execution test on returns and balance sheet discipline.
Comcast's narrative projects US$120.6b revenue and US$11.4b earnings by 2029. This implies a 1.2% yearly revenue decline and an earnings increase of about US$0.2b from US$11.2b today.
Uncover why Comcast's fair value indicates a 32% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Hardee County puts a spotlight on one big disagreement. Bearish analysts worry that rural and small market builds could lock Comcast into weaker broadband economics, supporting their call for revenue of about US$116.6b and earnings of US$9.8b by 2029. You might see this differently, so explore several viewpoints before the narrative shifts following the news.
Explore 5 other Comcast fair value estimates, including one that suggests as much as 22% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Comcast research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Comcast. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comcast's overall financial health at a glance.
Looking for more investment ideas beyond Comcast?
Once you have a view on Comcast, it helps to widen the lens and compare it with other businesses that match the type of opportunity you want to focus on next.
- If you want potential growth with a small starting base, scan through 13 elite penny stocks with strong financials that already carry stronger balance sheets and financial profiles than most tiny companies.
- For investors who care most about resilient business quality at a reasonable entry point, review the 33 high quality undervalued stocks to see which stocks currently line up with that profile.
- When capital protection and steady fundamentals are your first filter, start with the list of solid balance sheet and fundamentals (25 results) and narrow down from a universe of companies built on stronger financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com