
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Orica (ASX:ORI) Hits 15,000 AXIS Units, Is The Stock Still A Bargain?
Orica (ASX:ORI) is back on investor radars after its Digital Solutions arm produced the 15,000th AXIS Champ Ori unit, a core orientation tool that mining clients are adopting worldwide.
Recent trading tells a mixed story. Orica’s share price is at A$22.80, with a 1 day share price return of 1.56% and a 30 day share price return of 2.29%. However, the year to date share price return is down 6.48%, while longer term total shareholder returns of 8.67% over 1 year and 71.20% over 5 years point to momentum that has built over time rather than in the latest stretch.
Scan beyond Orica and this drilling milestone by reviewing a hand picked 92 robotics and automation stocks that are reshaping how heavy industry uses automation and precision hardware.
Bulls point to Orica’s AXIS milestone, rising earnings and a discount to analyst targets, while bears flag the recent share price slide and low value score. Which story does the current valuation support?
Most Popular Narrative: 12% Undervalued
Orica is trading at A$22.80 against a widely followed fair value estimate of A$25.91, so the current share price sits below that narrative view while still reflecting mixed short term returns.
The main factor that needs to go right is continued execution on cost reduction, capital discipline and portfolio tilt toward gold, copper and specialty mining chemicals, while managing supply incidents and thermal coal volume headwinds.
The current valuation implies the share price does not fully reflect the view that Orica is undervalued and that higher quality earnings from digital solutions, specialty chemicals and lower emissions assets are becoming a larger share of the business.
See why 26 investors see Orica as 12% undervalued.
Result: Fair Value of A$25.91 (UNDERVALUED)
Still, the Orica story could be knocked off course if sodium cyanide supply bottlenecks persist or if recent acquisitions such as Nelson Brothers and Cyanco underdeliver on EBIT.
Find out about the key risks to this Orica narrative.
Another View: Orica Through The P/E Lens
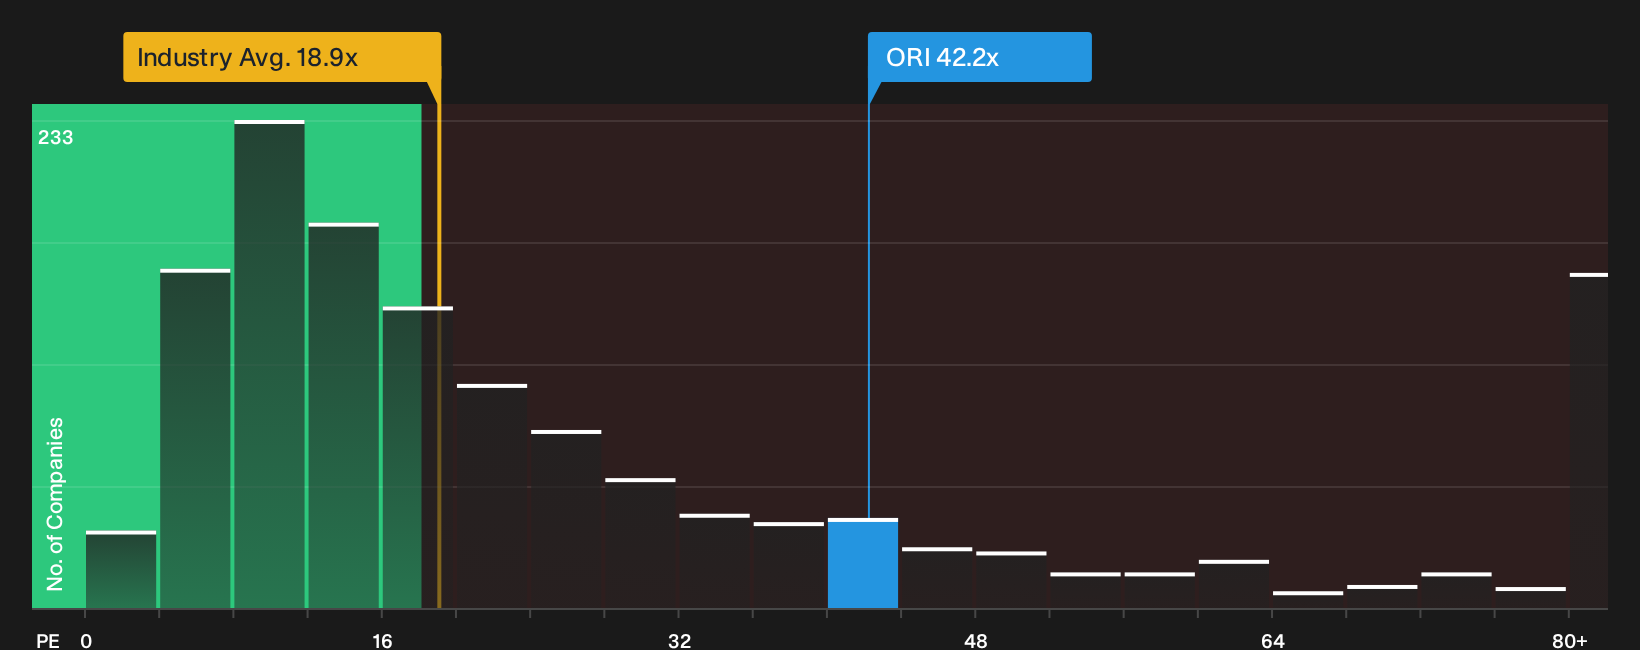
The first narrative presents Orica as undervalued relative to its A$25.91 fair value estimate, yet the P/E picture tells a more cautious story. At 42.2x earnings, the stock trades well above the Chemicals industry average of 18.9x, the peer average of 25.8x, and a fair ratio of 19.1x that the market could move toward over time. That gap suggests valuation risk if earnings or sentiment slip, so it raises the question of how much weight to place on the growth story compared with the current multiple.
For a deeper look at how this pricing gap compares with earnings power, review the detailed multiple breakdown and See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Orica sounds familiar, consider your options while the numbers and narratives are still fresh in mind, then review the full 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Orica?
Orica might fit part of your watchlist, but the market is full of other opportunities. Do not leave fresh ideas on the table when a few targeted screens could surface companies that better match your goals and risk comfort.
- Target potential upside by scanning a 15 high quality undiscovered gems that many investors have not yet focused on but already show strong underlying fundamentals.
- Zero in on resilience by reviewing a 6 resilient stocks with low risk scores that aim for steadier performance and fewer unpleasant surprises when conditions get choppy.
- Strengthen your core holdings by checking a list of solid balance sheet and fundamentals (12 results) so you are not relying on fragile finances when the cycle turns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com