
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Analyst Upgrades Change Swire Pacific's (SEHK:19) Narrative
- Swire Pacific has recently attracted stronger analyst support, with positive earnings estimate revisions and top-tier ratings pointing to growing confidence in its diversified property, aviation, and beverages operations.
- An interesting angle is how these upgraded expectations cluster around Swire Pacific's core cash engines, particularly its premium property portfolio and Asian beverages footprint, rather than short term trading factors.
- We will now explore how Swire Pacific's upgraded earnings expectations could interact with its existing investment narrative built around property and beverages.
Scan other analyst-backed opportunities moving on upgraded expectations by reviewing the 618 high quality undiscovered gems alongside Swire Pacific's renewed broker enthusiasm.
Swire Pacific Investment Narrative Recap
To own Swire Pacific, you broadly need to believe its mix of premium Mainland China property, Asian beverages and aviation interests can produce steady enough cash flows to justify the group structure. The most important near term swing factor is how quickly office and retail demand in Hong Kong and the Chinese Mainland can absorb existing and new space without eroding rents or occupancy.
The biggest current risk sits in that same property exposure, along with aviation volatility and higher funding costs that could pressure valuations and interest expense. The recent wave of positive estimate revisions mainly reinforces confidence already tied to operations rather than changing those underlying catalysts or risks in a material way.
With no fresh operational announcements alongside the rating upgrades, the most relevant context is the recent earnings profile that analysts are working from. Swire Pacific reported HK$94,139.0m of revenue and HK$8,892.0m of net income, with net profit margins described as higher than the prior year and earnings growth over the past year far above its 5 year average.
Those figures frame what the upgraded expectations are really keyed to. The short term watchpoints stay the same for you as a shareholder, mainly execution on the Mainland China property pipeline, resilience in beverages across Asia and how its aviation interests handle sector swings.
Swire Pacific Forecast Assumptions and Valuation Anchors
Analyst models around Swire Pacific are fairly explicit. The consensus view links its property and beverages story to concrete revenue and earnings targets rather than loosely defined optimism.
On the top line, forecasts point to revenue expanding by 5.0% per year over the next few years. That pace underpins a projection for profit margins to move from 9.4% today to 13.8% within roughly three years. If achieved, that shift would reshape how much cash the group can generate from each Hong Kong dollar of sales.
Earnings today are quoted at about HK$8.9b. The same analyst group expects that figure to reach HK$15.0b by around 2029, with earnings per share of HK$11.26. That upgrade path, if followed, would reflect a sizeable step up in profitability tied to the same mix of Mainland China property, Asian beverages and aviation stakes seen today.
On these projections, Swire Pacific would be trading on a P/E of 12.3x those 2029 earnings, down from 15.8x today and above the current 6.4x P/E cited for the wider Hong Kong industrials peer set. That gap matters because it suggests analysts are incorporating a premium for the group structure and asset mix, not a discount.
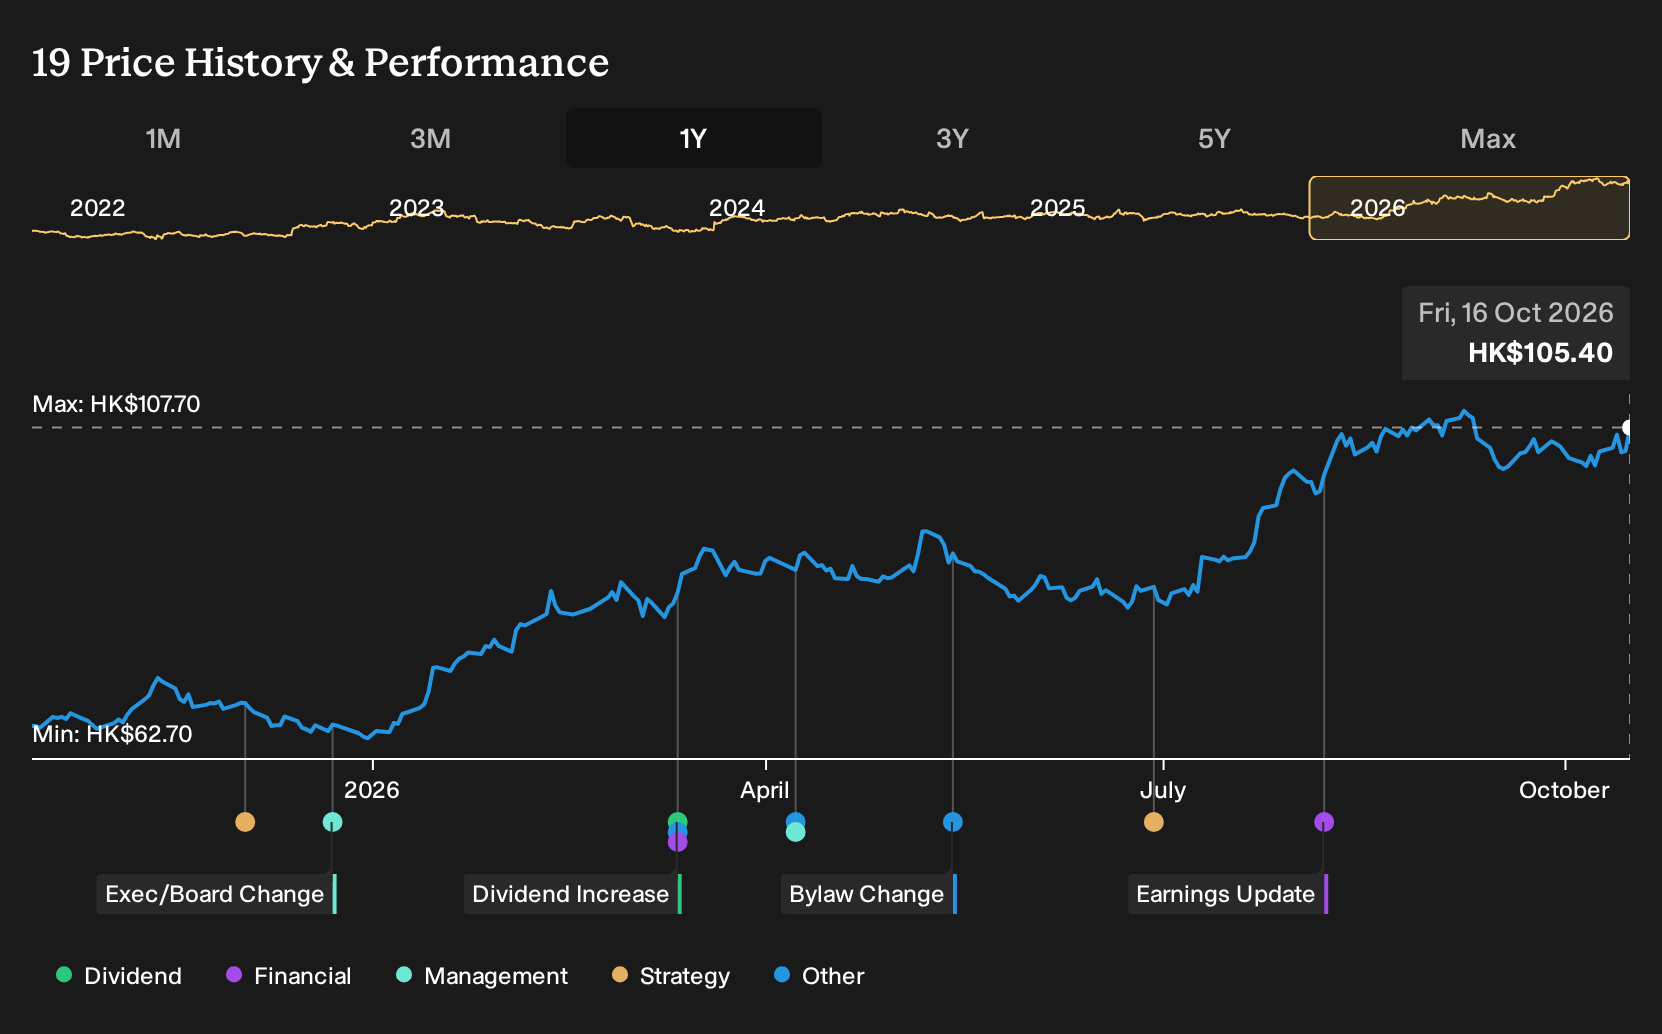
Consensus fair value work then pulls this into a single reference point. The group of covering analysts has a shared price target of HK$105.46, compared with a current share price reference of HK$104.30. The most optimistic forecast sits at HK$118.0 and the most cautious at HK$92.0, which gives a sense of the spread in views even when the earnings line converges around HK$15.0b.
The implied revenue backdrop in that framework is HK$108.9b by 2029, with earnings again at HK$15.0b, discounted using rates of about 9.1% or 9.06% in the underlying models. Those inputs do not guarantee any outcome for shareholders, but they do provide a clear checklist to compare against individual expectations for rents, beverage volumes and aviation cash flows.
One practical takeaway for readers is the relatively small 1.1% gap between the current share price and the consensus target. This signals that, on average, analysts see Swire Pacific as roughly aligned with their fair value estimates rather than obviously mispriced in either direction.
Swire Pacific's narrative projects HK$108.9b revenue and HK$15.0b earnings by 2029. That path assumes 5.0% yearly revenue growth and an earnings increase of about HK$6.1b from current earnings of HK$8.9b.
Uncover why Swire Pacific's fair value is assessed as being in line with its current price.
Exploring Other Perspectives
One alternative take focuses squarely on aviation risk. The most bearish analysts were working off slower revenue growth assumptions of around 3% a year and 2029 earnings nearer HK$14.5b, compared with the HK$15.0b consensus. Those pre news forecasts paint a more cautious story. You can use them as a prompt to stress test your own view, especially if this latest optimism around Swire Pacific leads to further estimate changes.
Explore another Swire Pacific fair value estimate, including one that suggests it could be worth just HK$105.46.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Swire Pacific research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Swire Pacific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Swire Pacific's overall financial health at a glance.
Looking for more investment ideas beyond Swire Pacific?
If you want to pressure test your view on Swire Pacific against a wider opportunity set, the Simply Wall St Screener can help you quickly sort companies by quality, valuation and risk so you are not relying on a single stock to carry your thesis.
- For readers who care most about resilient balance sheets and solid fundamentals, start with this curated list of solid balance sheet and fundamentals (203 results) to see which businesses match that profile.
- If you prefer to focus on potential mispricing, use the screener highlighting 193 high quality undervalued stocks that pair strong fundamentals with valuations that analysts regard as undemanding.
- Income focused investors can scan for reliability by filtering for 212 dividend fortresses that combine higher yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com