
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Mongolian Mining (SEHK:975) Faces A 62% Fair Value Gap As Production Improves
Mongolian Mining (SEHK:975) released unaudited production figures for the quarter to 30 September 2026, highlighting higher run of mine coal mined, coking coal processed, and washed coking coal produced compared with a year earlier.
Despite the stronger production update, Mongolian Mining’s recent share price performance has been weak, with a 30 day share price return down 14.73% and a year to date share price return down 26.10%. However, the 3 year total shareholder return of 113.17% and 5 year total shareholder return of 244.78% still point to a stronger long run journey for investors.
Scan for other coal and resources plays moving on fresh production news by reviewing the hand picked 17 top copper producer stocks alongside Mongolian Mining.
Bulls point to Mongolian Mining’s stronger production figures, while bears focus on the share price slide and low value score. As you weigh the next move, which side does the current valuation actually support?
Preferred P/E of 8.8x: Is it justified?
Mongolian Mining closed at HK$7.93, and on a P/E of 8.8x it trades on a lower earnings multiple than both the Hong Kong market and its peer group, even after the recent share price drop.
The P/E ratio compares the current share price with earnings per share. For a coal producer like Mongolian Mining, it gives a quick sense of how much investors are paying for each dollar of profit in a sector where earnings can swing with commodity prices and contract terms.
A headline P/E of 8.8x looks modest when set against 975's track record of 25.1% yearly earnings growth over the past 5 years and a net profit margin of 11.1%. This is especially the case with profit growth over the last year running at 43.8%. The discounted multiple sits beside a low value score of 2 out of 6 and a Return on Equity of 9.3%. This suggests the market may be cautious about how durable those profits are, particularly with all funding reported as higher risk borrowing and no analyst growth forecasts to lean on.
Relative to the Hong Kong Metals and Mining industry average P/E of 9.1x and a peer average of 16.7x, Mongolian Mining trades at a clear earnings discount. The gap to the broader peer set is wide. This signals that investors are currently pricing 975's earnings materially lower than many comparable miners, even though its earnings have grown and its margins have improved compared with last year.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 8.8x (UNDERVALUED).
Still, Mongolian Mining faces clear risks around higher risk borrowing and the recent 1 year share price decline of 40.87% that could challenge any value story.
Find out about the key risks to this Mongolian Mining narrative.
Another View: SWS DCF model flags overvaluation
A second lens tells a very different story. Mongolian Mining trades at HK$7.93, while our DCF model points to a future cash flow value of about HK$3 per share. On that basis the stock screens as overvalued, which pushes you to ask how much faith to place in those cash flow assumptions.
Before leaning on the DCF alone, it helps to see how the mechanics work in practice and where the key sensitivities sit in the cash flow path and discount rate inputs. Look into how the SWS DCF model arrives at its fair value.
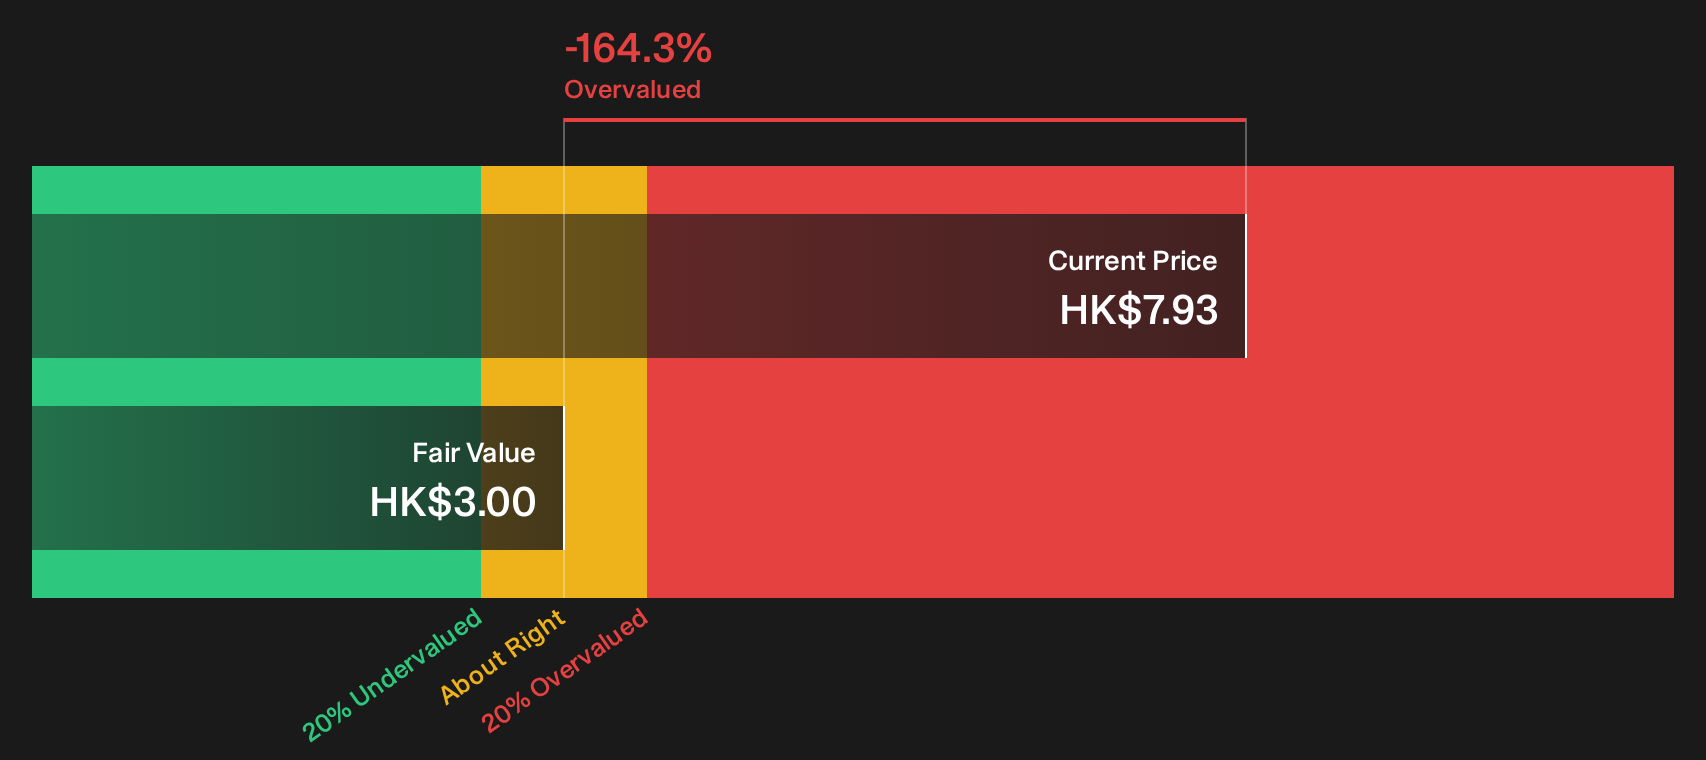
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mongolian Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Mongolian Mining can be confusing, so it helps to pull up the charts, recheck the data, and decide where you land. To see what optimistic investors are focusing on, take a closer look at the 2 key rewards
Looking for more Mongolian Mining investment ideas?
Do not stop your research with Mongolian Mining. The market rarely hands out second chances to those who ignore fresh ideas backed by hard numbers.
- Tap into potential mispricing by checking companies that show up in the 193 high quality undervalued stocks and see which ones deserve a closer look.
- Protect your downside by focusing on resilient balance sheets through the list of solid balance sheet and fundamentals (203 results) so weak finances do not catch you off guard.
- Hunt for potential future leaders early with the 618 high quality undiscovered gems before attention and capital crowd in and narrow your opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com