
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Buyback Expansion Change The Bull Case For Talen Energy Stock (TLN)?
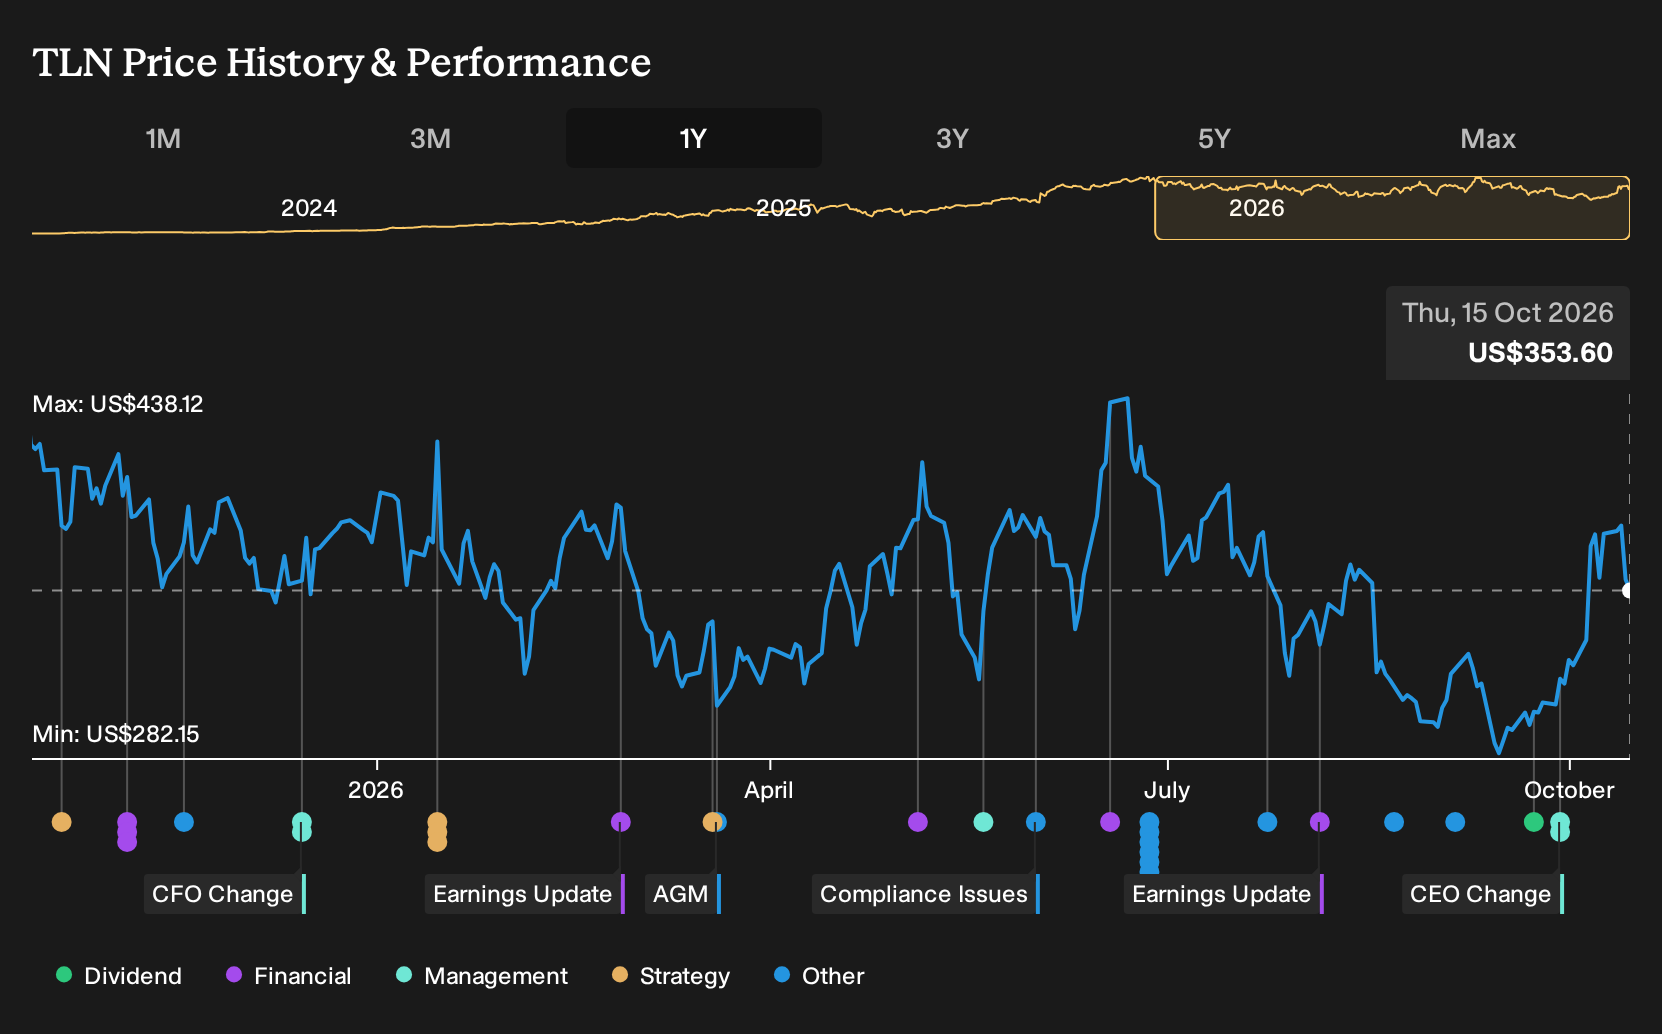
- Talen Energy expanded its share repurchase authorization to US$3b, including a US$1.5b accelerated program, after a Pennsylvania executive order on data center development affected its business.
- The enlarged buyback, which is sizeable relative to Talen Energy’s market value, signals management’s preference to deploy capital into its own equity while the data center related regulatory backdrop in Pennsylvania introduces new operating constraints.
- We will look at how Talen Energy’s investment narrative is reshaped by this large buyback response to the Pennsylvania data center order.
Scan how Talen Energy’s buyback move compares by reviewing other power and infrastructure stocks on our hand picked 41 power grid technology and infrastructure stocks.
Talen Energy Investment Narrative Recap
To own Talen Energy, you need to believe the PJM focused generation fleet and long term contracts can convert into meaningful adjusted free cash flow even while GAAP earnings stay volatile. The immediate swing factor is still execution on existing PPAs and generation assets, rather than the Pennsylvania data center setback, which touches only part of the story.
The order heightens an already present risk around data center politics, on top of softer PPL power pricing and PJM market reforms that could weigh on revenue and margins. At this stage, the biggest operational watchpoint is whether weaker zonal prices and the wider spread to PJM West Hub persist or ease over coming quarters.
The expanded US$3b repurchase authorization, including the US$1.5b accelerated program, is the announcement most closely tied to this news. Management is leaning harder into buybacks while the data center regulatory picture in Pennsylvania becomes more complicated. This places even more weight on future cash generation and liquidity discipline.
For you as a shareholder, that makes execution risk around free cash flow and balance sheet health more important. Interest payments are not well covered by current earnings, GAAP results recently showed a US$2 per share loss in Q2 2026, and any prolonged weakness in PPL pricing or delays in new PPAs would matter more with such a large capital return plan in motion.
Talen Energy's narrative projects US$5.8b revenue and US$1.6b earnings by 2029. This assumes revenue grows at 15.6% per year and earnings rise by about US$1.8b from the current loss of US$185.0m.
Discover how Talen Energy's fair value indicates a 30% potential upside to its current price that could close faster than many expect.
Exploring Other Perspectives
The alternate view on Talen Energy leans heavily on regulatory risk. The most cautious analysts worried that PJM reforms and data center policies could slow contract wins, so they were only penciling in about US$4.8b of revenue and US$1.4b of earnings by 2029. That is a more muted story than consensus, and the Pennsylvania order plus the enlarged buyback could lead those narratives, whether optimistic or pessimistic, to shift. Use this spread in opinions as a cue to explore several angles before you decide how comfortable you are with the risk profile.
Explore 4 other Talen Energy fair value estimates, including one that suggests as much as 7% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider performing your own analysis and going with your instincts.
- A great starting point for your Talen Energy research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Talen Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Talen Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Talen Energy?
If this Talen Energy story has sharpened your view on risk, return, and capital allocation, use that same lens to scan a broader watchlist. The Simply Wall St Screener can help you quickly surface companies that better match your income needs, quality bias, or risk tolerance.
- If you want income resilience to anchor your portfolio, start with our selection of 7 dividend fortresses that focus on stronger yield profiles and more durable payouts.
- For investors who care most about financial strength and staying power, filter for sturdier balance sheets and cleaner fundamentals through the list of solid balance sheet and fundamentals (25 results).
- When you are hunting for future portfolio candidates before they get crowded, use the 20 high quality undiscovered gems to surface companies with solid under-the-radar fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com