
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Cummins Stock Appeal Means For Shareholders
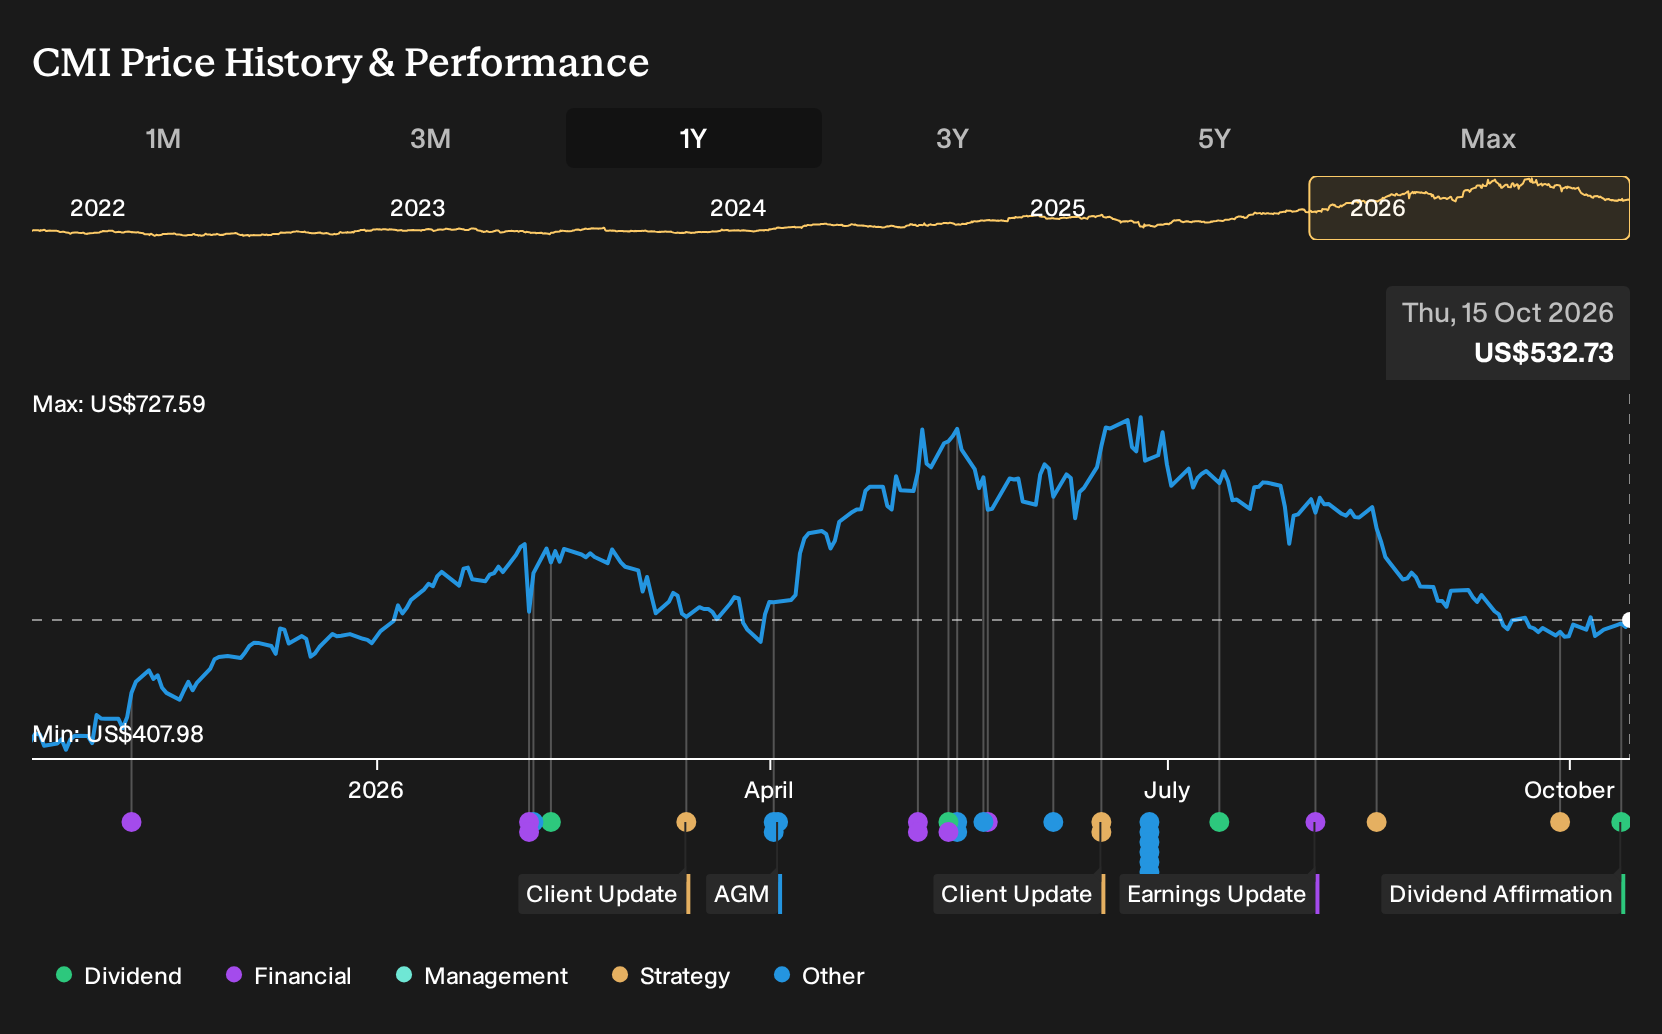
- Cummins declared a quarterly cash dividend of US$2.20 per share in October 2026, payable on December 3, 2026 to shareholders of record on November 20, 2026.
- The confirmed payout coincides with fresh attention on Cummins' engine and powertrain operations and its role in backup power and storage for data centers, highlighting how its traditional manufacturing base intersects with growing energy infrastructure demand.
- The focus now turns to how Cummins' confirmed dividend and exposure to data center power solutions fit into the broader investment narrative.
Scan beyond Cummins and this dividend story to compare it with hand-picked peers tied to data center power and grid demand through our 41 power grid technology and infrastructure stocks
What Is Cummins' Investment Narrative?
The Cummins story is ultimately about whether you believe a 100 year old industrial manufacturer can keep converting heavy capital spending into solid returns. The business leans on long running engine, components and distribution operations that feed into data center backup power and grid related projects, all of which require ongoing investment in plants, inventory and product development. The affirmed US$2.20 dividend fits that picture as a sign that management is comfortable committing cash while still funding those needs, but by itself it does not change the near term demand, pricing or execution drivers.
In the short term, the more important swing factors are how data center power projects translate into actual orders, how quickly higher value components and service work show up in earnings, and whether Cummins can keep returns on equity near current high levels while margins have recently softened. Analysts see potential upside with the stock trading below their price targets and their cash flow value estimates, which speaks to expectations rather than guarantees, and the confirmed dividend simply reinforces Cummins' identity as a capital intensive, income paying industrial rather than a hyper growth story.
That said, there is a less comfortable angle to this income and data center power story that hinges on ...
There's only one way to know the right time to buy, sell or hold Cummins. Head to Simply Wall St's company report for the latest analysis of Cummins's Fair Value.
Exploring Other Perspectives
One alternate view focuses on the risk that Cummins overbuilds high horsepower capacity for data centers. The most cautious analysts were already assuming revenue of about US$43.2b and earnings near US$4.5b by 2029 before this dividend news. Their stance is far less upbeat than consensus, which shows how widely views can differ. Use this dividend affirmation as a prompt to compare those scenarios and decide which story you find more convincing.
Explore 3 other Cummins fair value estimates, including one that suggests it could be worth just $721.14!
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Cummins research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cummins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cummins' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cummins?
Once you have a view on Cummins, it can help to compare that against other opportunities using the Simply Wall St Screener and see what else fits your return and risk preferences.
- If you want income with some resilience, start by scanning companies that look like potential dividend fortresses through the 8 dividend fortresses.
- If value is your main filter, compare Cummins with a broader set of companies that appear high quality yet potentially mispriced using the 33 high quality undervalued stocks.
- If capital preservation matters most, narrow your watchlist to businesses that currently show lower risk scores through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com