
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
New Hope (ASX:NHC) Shares Moved, So What Is Driving Attention Today?
New Hope (ASX:NHC) just reported H2 2026 figures that show higher revenue and net income than the same period in 2025, putting fresh attention on how the coal producer handles persistent ESG and demand questions.
New Hope’s share price has slipped around 10% over the past month but is still up about 12% over 90 days and has a 44.2% year to date share price return. The 1 year total shareholder return of 56.54% and very large 5 year total shareholder return suggest longer term holders have seen strong gains as the market reassesses both its cash generation and coal related risks.
Compare New Hope’s performance and ESG exposure with a curated group of resource producers in our 6 resilient stocks with low risk scores to see which businesses pair resilience with lower risk scores.
After a sharp run over 12 months and a recent pullback, New Hope now sits at an interesting crossroads for fresh capital. Do current cash flows and risks still justify paying this price?
Most Popular Narrative: 3% Overvalued
New Hope last closed at A$5.84 while the most followed narrative pegs fair value at about A$5.68, so the current price sits slightly above that estimate and puts the focus on whether long term thermal coal headwinds outweigh its production and cash flow profile.
The global shift towards decarbonization and accelerating policy pressure to reduce coal consumption is expected to suppress long-term demand for thermal coal, creating sustained downward pressure on New Hope's revenues and potentially curbing export volume growth in the coming years. Rapid adoption and cost competitiveness of renewable energy sources and advances in energy storage technologies are likely to undermine the attractiveness of coal-powered electricity, eroding New Hope's addressable market and putting structural pressure on revenue and earnings.
See why 48 investors see New Hope as 3% overvalued.
Result: Fair Value of A$5.68 (OVERVALUED)
Still, higher saleable production and a sizeable cash balance give New Hope optionality if coal pricing, export demand, or approvals play out more favourably than feared.
Find out about the key risks to this New Hope narrative.
Another View: New Hope Looked At Through Earnings Multiples
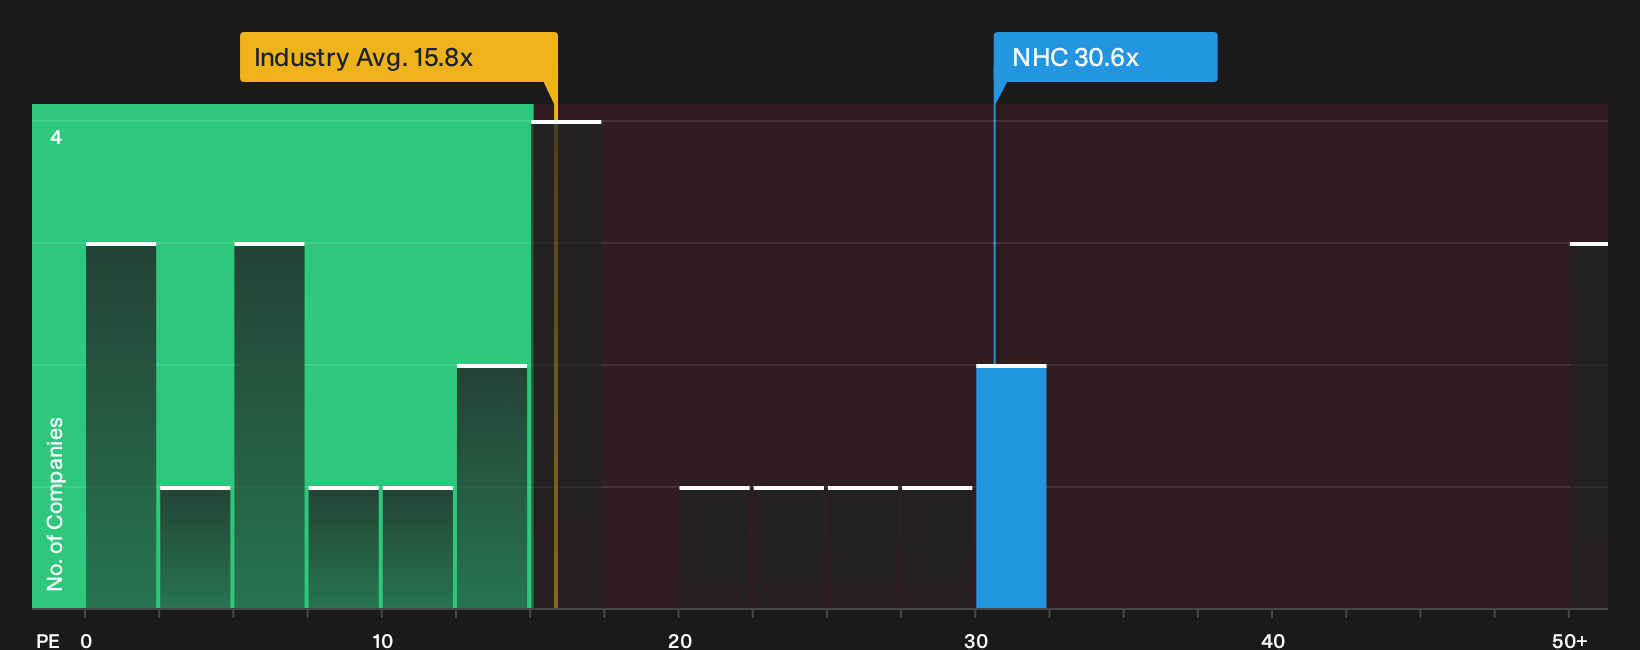
The first narrative leans on analyst targets to argue New Hope is slightly overvalued at A$5.84 versus a A$5.68 fair value. The P/E picture tells a sharper story. The stock trades on 30.6x earnings, while the Australian Oil and Gas group sits at 15.8x and the fair ratio sits at 19.2x.
That gap means buyers today are paying a much higher price for each dollar of profit than both peers and the level our fair ratio suggests the market could move toward. The question is simple. Are you comfortable paying that premium if sector sentiment cools or earnings only grow in line with current forecasts?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on New Hope leaves you on the fence, move quickly, test the numbers for yourself, and weigh both sides. To frame that judgment with context on the key trade offs, check out the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond New Hope?
If New Hope leaves you unsure about adding fresh money, broaden the opportunity set and let data driven shortlists surface alternatives that better match your checklist.
- Target resilient compounding by scanning a 4 high quality undervalued stocks that blends strong fundamentals with prices that sit below many investors’ radar.
- Prioritise staying power and financial strength by filtering companies through a list of solid balance sheet and fundamentals (12 results) that focuses on healthier leverage and liquidity profiles.
- Hunt for future leaders early by reviewing a 15 high quality undiscovered gems packed with quality metrics that many market participants may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com