
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Citizens Financial Group (CFG) Stock May Be 45% Undervalued On Excess Returns
Citizens Financial Group has delivered a powerful share price run in recent years, which naturally puts the focus on whether the bank’s returns on capital are doing the heavy lifting behind that move. With the stock coming off a softer recent patch, the key issue is whether the current valuation still lines up with what the business is actually earning on the money it puts to work.
- Over the past 3 years, Citizens Financial Group has returned 187.6%, which raises the question of how much of that gain is supported by the returns it earns on its capital.
- The group’s performance will hinge on how efficiently it can keep recycling customer deposits and its own equity into interest earning assets, since that engine drives both earnings power and the value investors place on each dollar of capital inside the bank.
- If you'd rather focus on earnings, this one's for you. See what Citizens Financial Group's 13.5x P/E says about the price.
The issue now is whether Citizens Financial Group’s share price is appropriately aligned with the returns it is currently generating on its capital base.
If you are weighing Citizens Financial Group against other banks on how well they put capital to work, it can help to line it up beside 33 high quality undervalued stocks.
Is Citizens Financial Group a Bargain on Excess Returns?
The Excess Returns model looks at how well Citizens Financial Group turns shareholder equity into profits above its own cost of capital. Citizens Financial Group is modeled with book value of $56.95 per share and an average return on equity of 10.31%, which translates into a stable earnings power of about $6.48 per share. Against a cost of equity of $4.59 per share, the framework implies an excess return of $1.88 per share on a stable basis.
That gap between what the bank is estimated to earn on its equity and what it needs to earn to cover its capital charge is what drives the valuation output, together with a projected stable book value of $62.82 per share. The Excess Returns projections put Citizens Financial Group's estimated intrinsic value substantially above the current share price of $63.43, which suggests the market is assigning a lower value to those modeled excess earnings than the framework implies. Find out what Citizens Financial Group could be worth using our Excess Returns estimate.
The Citizens Financial Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Citizens Financial Group leaves off and spell out which paths for growth, profitability and earnings would need to play out for the stock to be worth a lot more or a lot less than today’s price on the Community page. Each one links its number to a concrete view on how Citizens Financial Group's growth, margins and risks might shift, giving you something specific to test as fresh information comes through.
One of the top community narratives on Citizens Financial Group: 20% undervalued
"The main thing that has to go right is execution on scaling the high‑ROE Private Bank and wealth platform, while continuing to grow capital markets, payments, and fee income without allowing rising deposit costs to erode returns…"
Discover why this Narrative puts Citizens Financial Group at 20% undervalued.
One more Citizens Financial Group signal worth checking before you move on
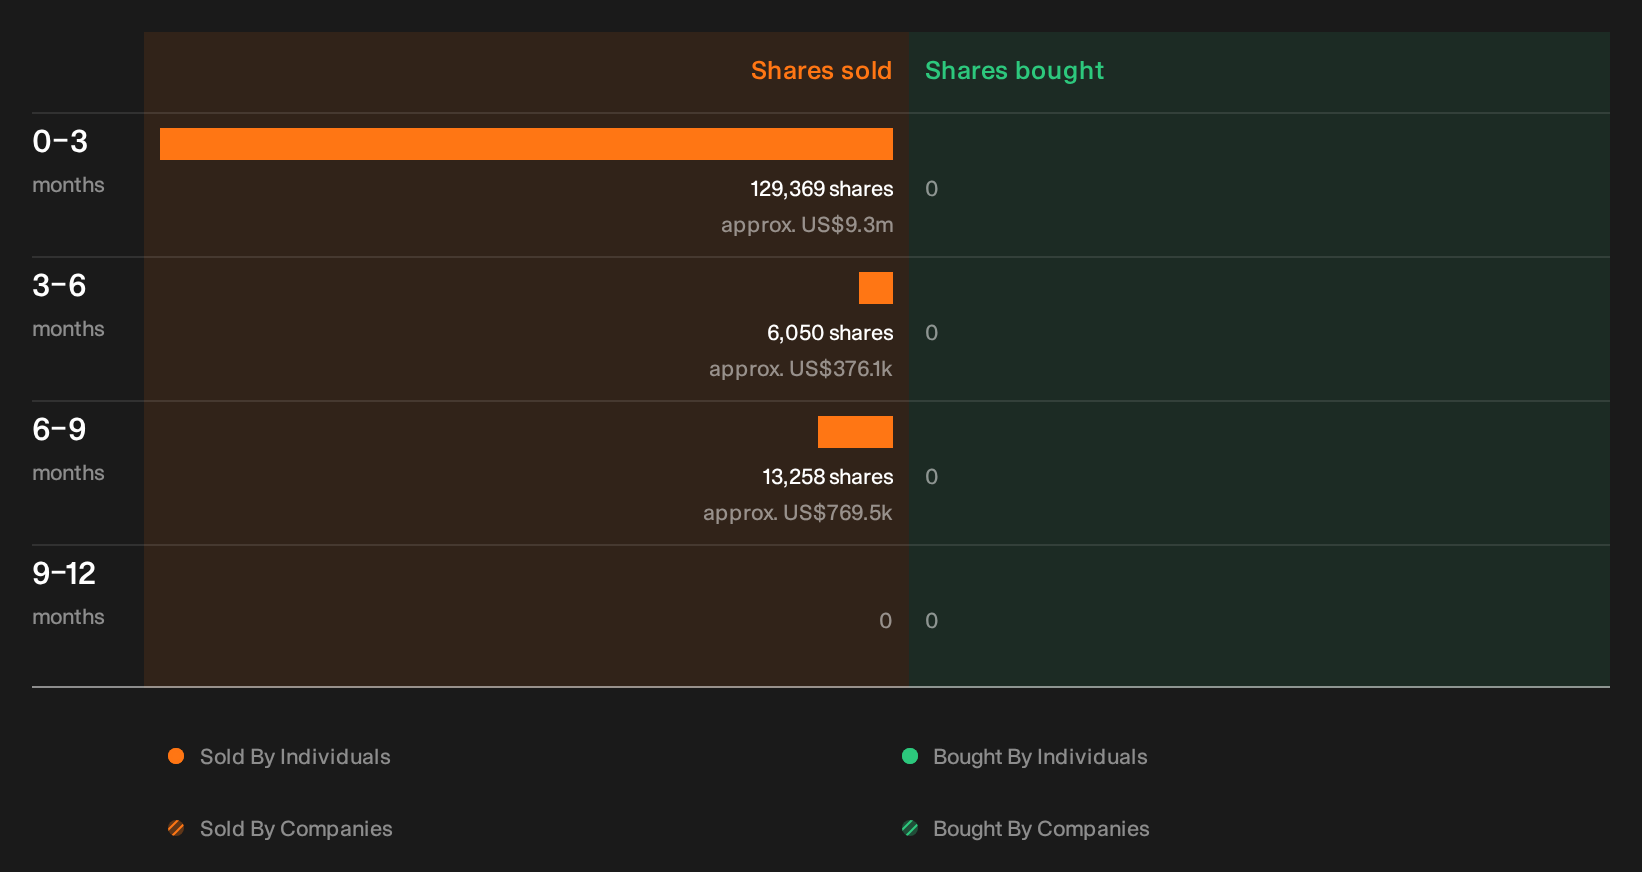
Valuation is only one piece of the story for Citizens Financial Group, because recent transactions by company insiders surfaced in our checks and the people involved, the sizes, and what they might hint at are still for you to review. See the recent insider selling flagged for Citizens Financial Group.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com