
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did CEO Succession Just Shift General Dynamics (GD) Investment Narrative?
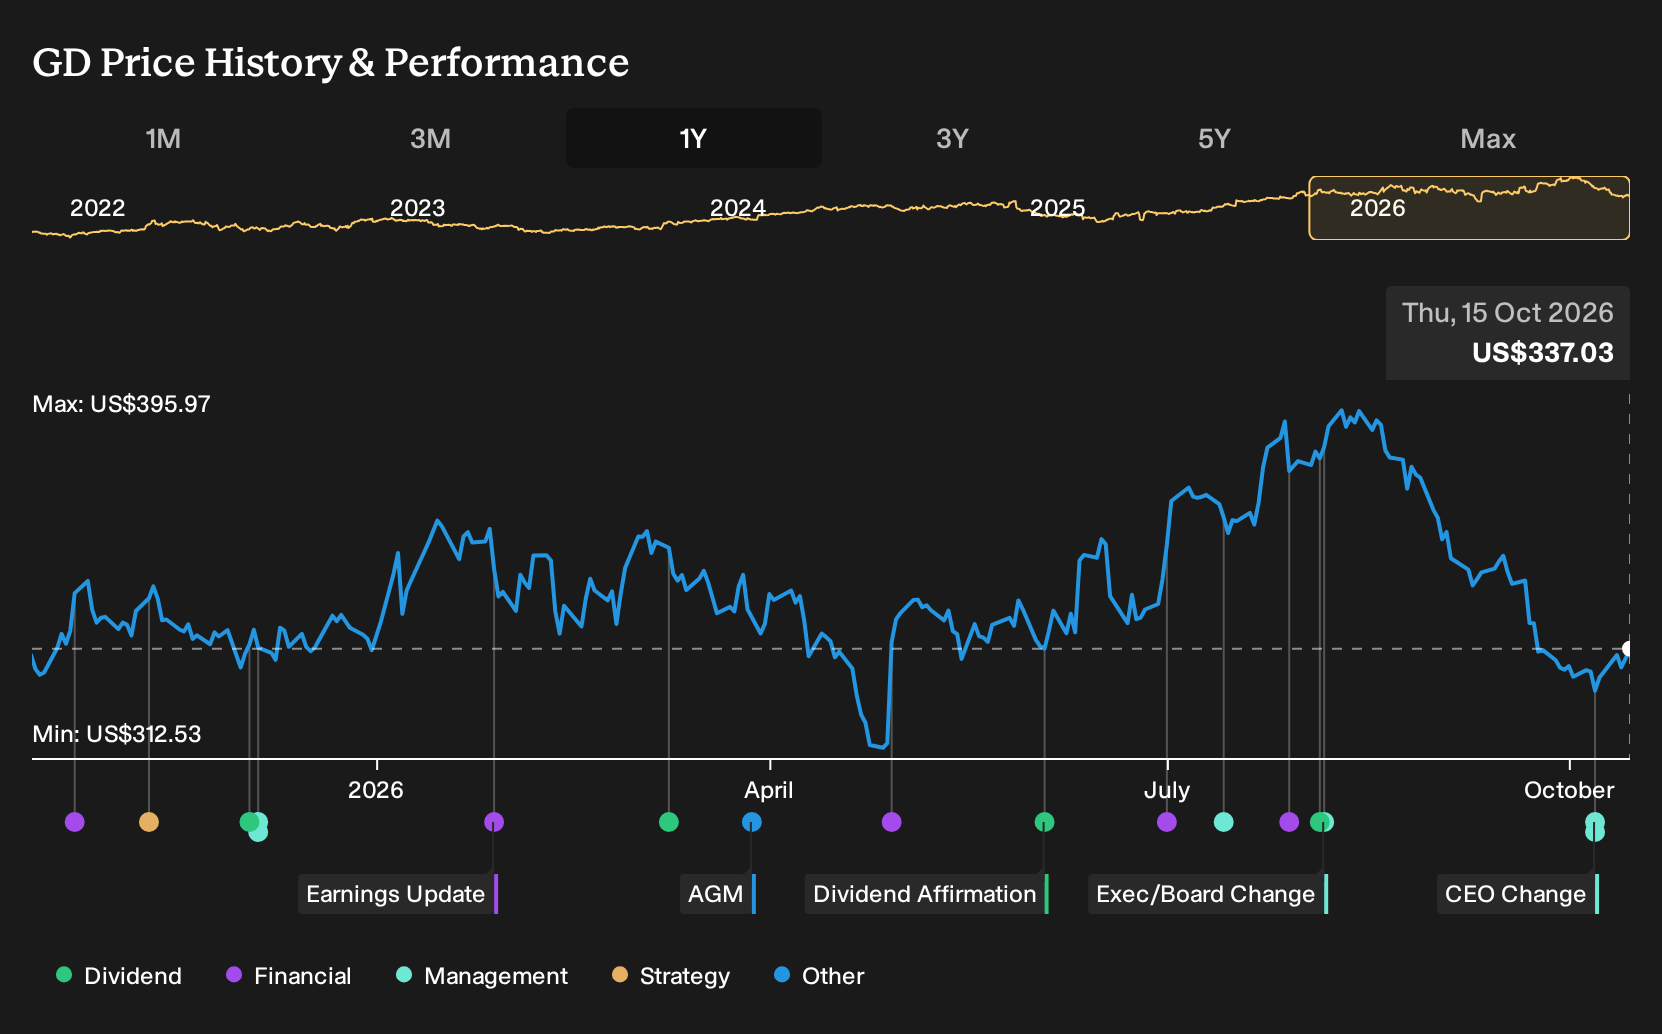
- General Dynamics reported that long time CEO Phebe Novakovic, who has led the company since 2013, moved to the role of executive chairman, while current president Danny Deep, a 25 year veteran with experience across operations and combat systems, was elected CEO effective January 1, 2027.
- This handover concentrates day to day control with an internal operator who has run Global Operations and Combat Systems, while keeping Novakovic involved at board level. This is relevant for how General Dynamics manages its large backlog, cost base, and execution on long term defense and aerospace programs.
- We will now see how General Dynamics' investment narrative could be influenced by Danny Deep's appointment as the next CEO.
Scan how other defense contractors are repositioning leadership and capital with curated lists such as list of solid balance sheet and fundamentals (25 results) as potential peers to General Dynamics in your research.
General Dynamics Investment Narrative Recap
To own General Dynamics, you need to be comfortable with a long pipeline of defense, aerospace, and technology programs that depend on consistent execution rather than rapid top line expansion. The key near term swing factor is how efficiently that US$136.5b backlog and US$186.9b in total estimated contract value are converted into revenue and cash.
Danny Deep stepping in as CEO while Phebe Novakovic becomes executive chairman does not fundamentally alter that thesis. The biggest near term risk still sits in execution on complex programs, including issues like the Mesquite artillery shell plant, where delays or cost overruns could pressure margins even if demand and contract wins stay supportive.
The most relevant recent development to this leadership handover is the continued ramp of long cycle programs, particularly the approximately US$76.6b multiyear award at Electric Boat for Virginia and Columbia class submarines. These contracts frame the operational agenda Deep inherits, with throughput, productivity, and schedule discipline all highly visible for investors watching Marine Systems.
General Dynamics also has important catalysts in Gulfstream, where newer aircraft such as the G800 and record quarterly deliveries give management another execution test, and in Combat Systems and Technologies where strong book to bill and wins like the up to US$1.3b ENOCS contract add to the workload. The leadership transition sits on top of these drivers rather than replacing them, so the focus stays on delivery, quality, and cost control.
What The New General Dynamics CEO Is Inheriting On The Numbers
General Dynamics' narrative, including the incoming Deep leadership, now sits on top of a consensus model that is fairly explicit about what needs to line up over the next few years.
Analysts currently build in revenue growth of 4.4% a year over the next three years, which implies a measured expansion of the top line rather than a rapid surge. Profitability assumptions also point to gradual progress, with margins expected to move from 8.2% today to 9.1% in three years if execution on key programs improves.
On earnings, forecasts call for profit to reach US$5.7b by 2029 compared with US$4.5b today. That is an increase of about US$1.2b in absolute terms, with earnings per share projected at US$20.91 if the share count creeps higher by roughly 0.16% annually.
To line up with these projections, the market narrative around General Dynamics also assumes that by 2029 the business is generating US$62.5b in revenue, converting that into the US$5.7b profit pool, and trading on a P/E multiple of 25.1x instead of 19.9x today. The move in the multiple is tied to expectations that improved margins and steadier long term cash generation justify a richer price tag than the one the stock currently carries, while still sitting below the 34.6x P/E cited for the broader US Aerospace & Defense industry.
For you as an investor, the key question is not whether each of these numbers is precise. The more practical question is whether the combination of low single digit revenue growth, a modest uplift in margins, and roughly US$1.2b of extra earnings by 2029 feels realistic at the same time General Dynamics is working through submarine ramp ups, Gulfstream deliveries, and munitions plant fixes under a new chief executive.
General Dynamics' current analyst framework points to forecast revenue of US$62.5b and expected earnings of US$5.7b in 2029, based on revenue rising 4.4% per year and an earnings increase of about US$1.2b from US$4.5b today.
Uncover why General Dynamics' fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Only two fair value views from the Simply Wall St Community currently cluster tightly between about US$413 and US$427 per share. As a result, you are seeing early but concentrated conviction on General Dynamics. Those figures do not reflect the CEO transition or risks around execution issues and potential share dilution, so exploring more community viewpoints can help you judge how durable this leadership driven thesis might be.
Explore another General Dynamics fair value estimate, including one that suggests as much as 27% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your General Dynamics research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for General Dynamics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate General Dynamics' overall financial health at a glance.
Looking For More Investment Ideas Beyond General Dynamics?
If you want to stress test your view on General Dynamics, it helps to set it alongside other opportunities with different risk and income profiles. The Simply Wall St Screener can surface a range of listed businesses that match the kind of balance sheet strength, valuation, or payout profile you are looking for.
- For steadier balance sheets and fundamentals, line General Dynamics up against a list of solid balance sheet and fundamentals (25 results) that can help you benchmark financial resilience across your watchlist.
- If value is your priority, compare General Dynamics with a 33 high quality undervalued stocks that flags companies where quality metrics and pricing may look more attractive.
- Income focused investors can weigh General Dynamics against a 8 dividend fortresses designed to spotlight stocks offering higher yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com