
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Syndax Pharmaceuticals (SNDX) Stock May Be Fully Priced After Trial Setback
Syndax Pharmaceuticals has seen its share price come under pressure this year, and the latest clinical setback has only sharpened the question of what investors are really paying for in terms of sales. With sentiment shaken, the key issue is whether the current market value lines up with what the business actually generates on the top line.
- Year to date, Syndax Pharmaceuticals stock has fallen 35.9%, which puts fresh focus on how much investors are now paying for each dollar of the company’s sales.
- The failure of axatilimab in the Phase 2 IPF trial removes one potential future revenue stream, which can shift how investors think about the durability and scale of sales from the rest of the pipeline.
- There is a second opinion on Syndax Pharmaceuticals worth weighing. See what analysts think Syndax Pharmaceuticals's shares could be worth.
The issue now is whether Syndax Pharmaceuticals' current share price is justified by its sales when set against the Fair Ratio benchmark.
If you want to pressure test whether Syndax Pharmaceuticals' sales based valuation question shows up in other corners of the market, compare it with 33 high quality undervalued stocks.
Has Syndax Pharmaceuticals Run Too Far on Sales?
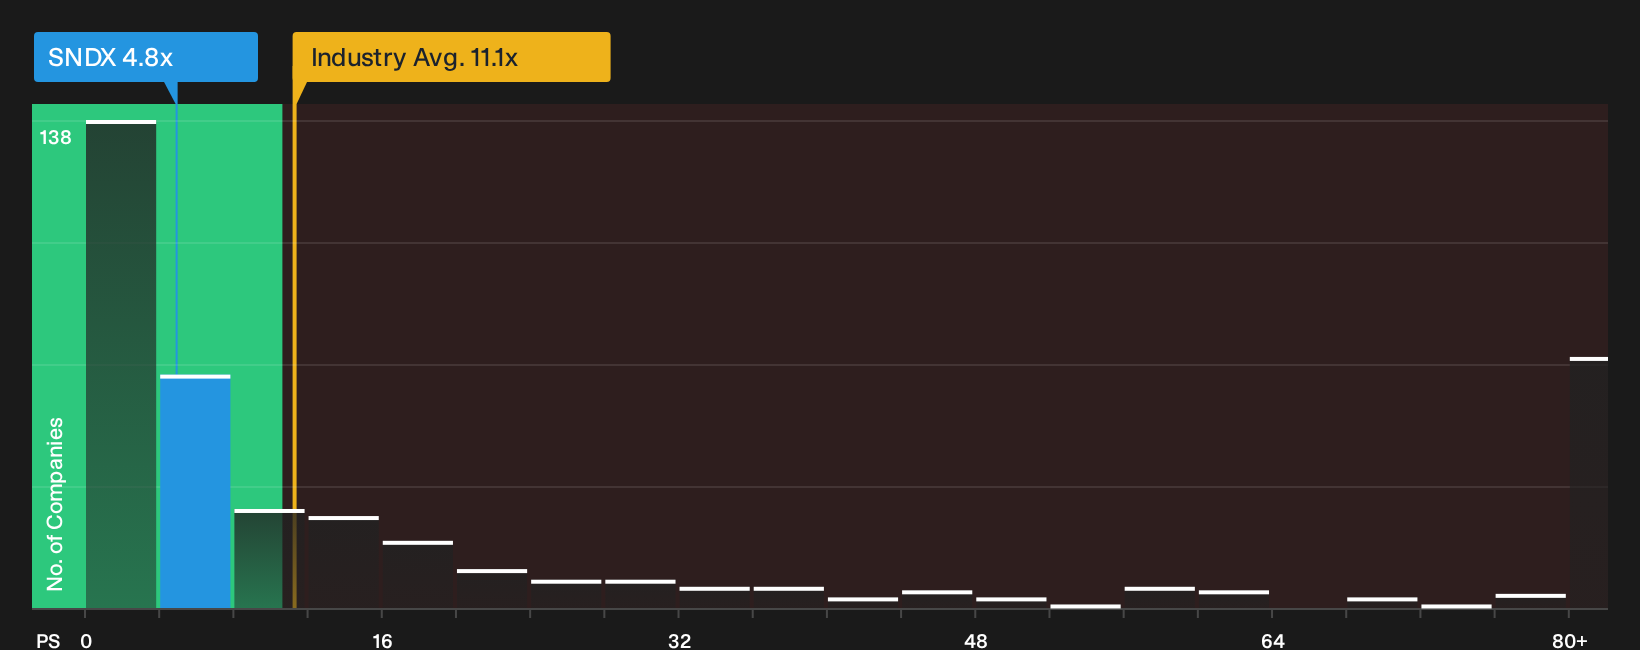
P/S is usually a cleaner yardstick for a biotech like Syndax Pharmaceuticals where earnings and free cash flow are still deep in the red. On this measure, the stock trades on a P/S of 4.8x, which is below the broader biotech industry average of 11.1x and also below the peer group average of 22.4x for similar companies.
The Fair Ratio framework, which looks at Syndax Pharmaceuticals' growth assumptions, margins, size and risk profile, points to a lower sales multiple than where the shares currently change hands. Because the latest axatilimab IPF trial failure removes one potential future revenue stream, the current P/S can still leave limited room for disappointment if the remaining pipeline underdelivers. For anyone weighing the stock, the gap between the live P/S and the Fair Ratio benchmark is the key question to test. Explore the numbers behind Syndax Pharmaceuticals's P/S valuation.
The Syndax Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives for Syndax Pharmaceuticals pick up where the Fair Ratio leaves off and explain which future paths for growth, margins and earnings would need to occur for the current share price to appear meaningfully higher or lower. Rather than offering a single output from a ratio or model, they outline the underlying assumptions behind those figures so you can monitor how the real business progresses against that storyline over time on Simply Wall St's Community page.
One of the top community narratives on Syndax Pharmaceuticals: 48% undervalued
"The main thing that has to go right is that Revuforj and Niktimvo continue to scale across additional AML, GVHD, and fibrosis indications..."
Discover why this Narrative puts Syndax Pharmaceuticals at 48% undervalued.
One more Syndax Pharmaceuticals check before you put the story down
Price tags and sales multiples only tell part of the story, because the people making the key calls and how they are rewarded can tilt the whole outcome for shareholders. See who runs Syndax Pharmaceuticals and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com