
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
The AI Debt Burden Is Spooking Wall Street. Here’s Why CoreWeave Is at the Center of the Storm.
The AI boom has a debt problem, and investors are not taking it lightly. CoreWeave (CRWV), one of the most aggressive borrowers in the AI infrastructure race, is now sitting at the center of the storm.
CoreWeave has been a market darling amid the AI infrastructure boom. To meet soaring demand for high-performance computing, the company aggressively expanded its infrastructure and took on substantial debt to keep pace. Now, investors are concerned about higher financing costs and whether the company can handle its debt. CRWV stock has dropped about 25% in the last five days and 48% over the past six months.
No doubt, CoreWeave is caught in the crossfire of the AI debt burden, but I wouldn’t dump the stock just yet. Here’s why.
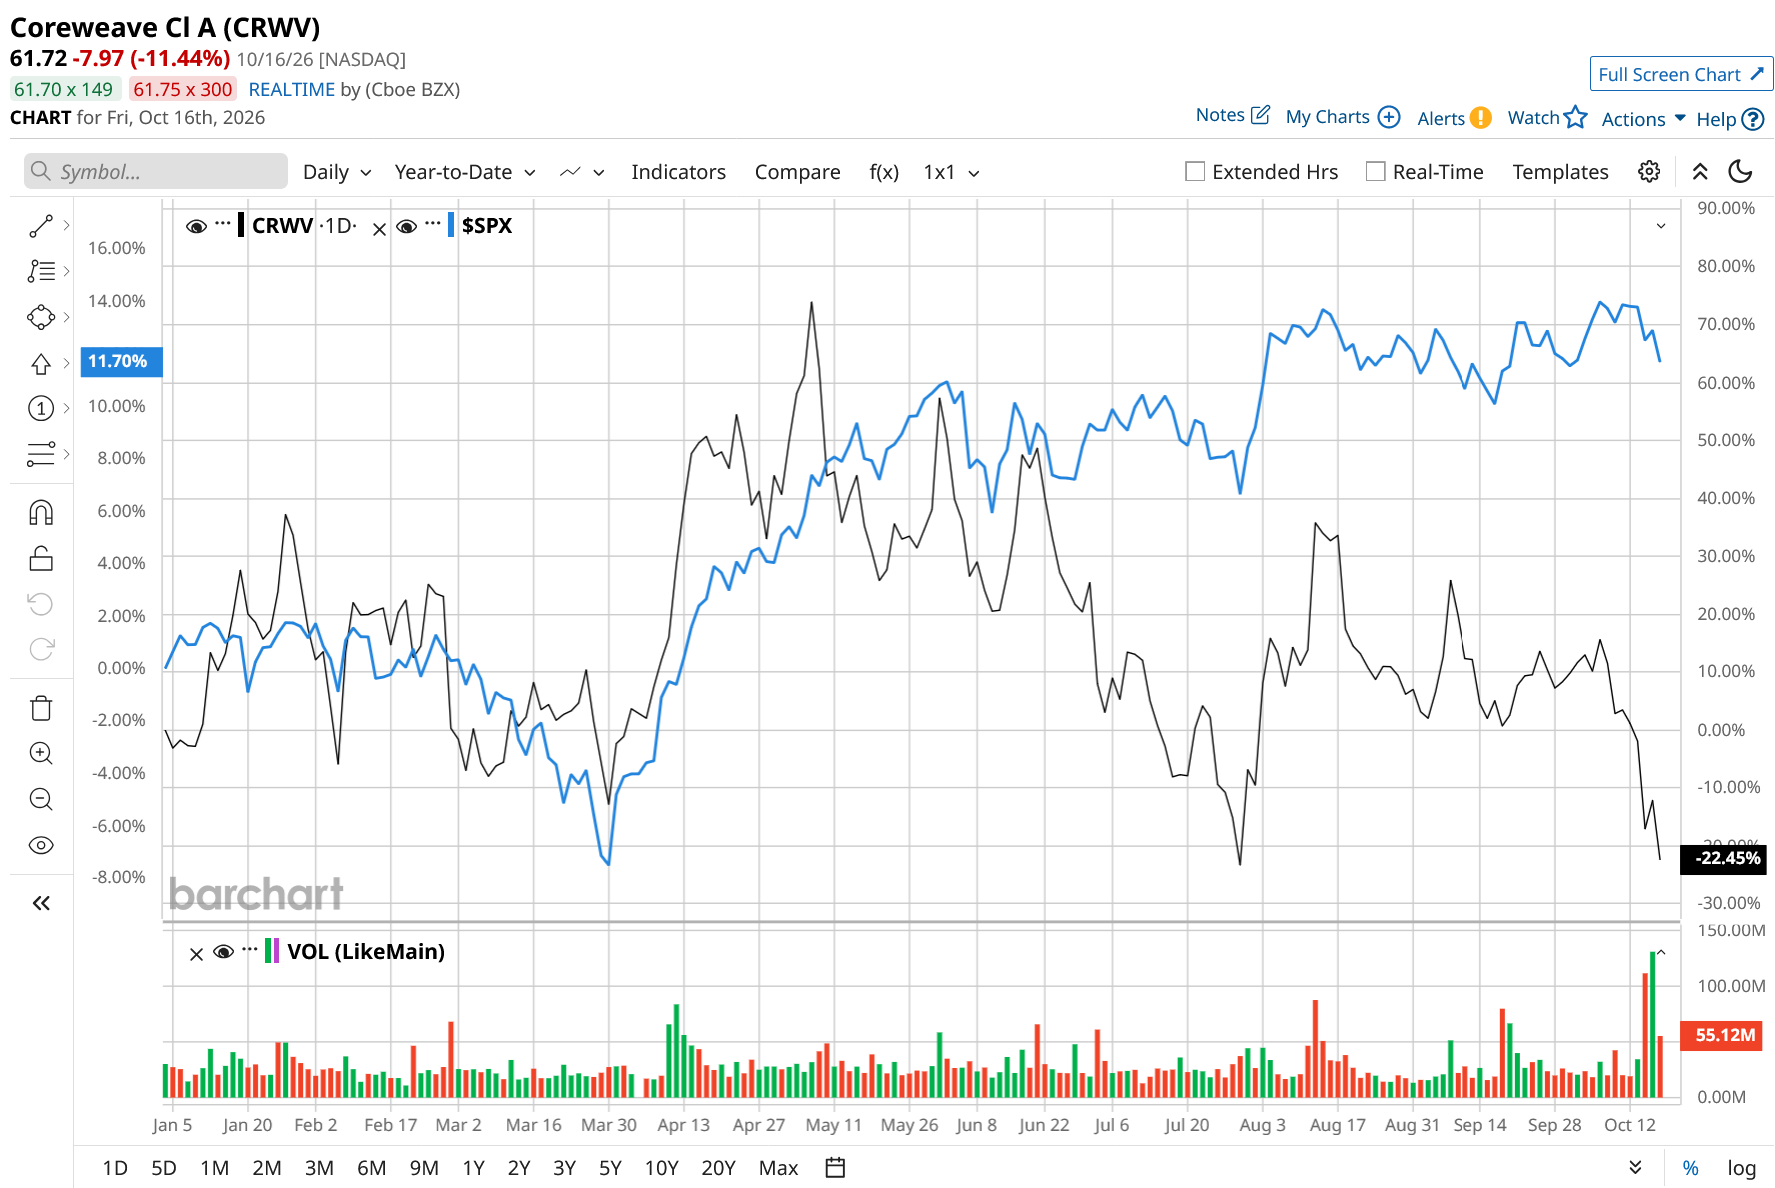
CoreWeave Becomes the Face of AI Debt Fears
The market's anxiety became hard to ignore after Reuters reported on Oct. 15 that five-year credit default swap (CDS) spreads for CoreWeave rose above 1,100 basis points. Yields on its 2031 bonds briefly hit about 16% before falling back to 14%. These changes show that investors now want much higher returns to take on the company’s credit risk. CoreWeave’s large debt load is now the main worry. According to Reuters, using LSEG data, the company’s debt is close to $50 billion. Because it has already borrowed so much, even a small shift in lenders’ risk appetite could affect CoreWeave’s ability to raise funds for future growth.
Revenue Is Soaring, but the Interest Bill Is Becoming Harder to Ignore
Although the stock is feeling the impact of CoreWeave’s debt, the company’s revenue is growing strongly. In the second quarter, revenue jumped 112% from last year to $2.6 billion. CoreWeave's revenue backlog stood at $104.2 billion at the end of Q2, followed by more than $25 billion in additional customer commitments secured early in Q3.
However, a backlog means business that has been contracted but will be delivered in the future. CoreWeave still needs to add capacity, provide computing services, and handle the costs of meeting these commitments. The company can report this as revenue only after it completes those steps. The spending required to support that growth is substantial. CoreWeave reported $9.4 billion in capital expenditures in Q2 and raised its full-year 2026 capital expenditure outlook to $35 billion to $39 billion.
The company is spending aggressively because it sees an opportunity to serve more demand, but that opportunity comes with a cost. CoreWeave reported $640 million in interest expense in Q2. Management expects this to rise to $860 million to $940 million in the third quarter as the company takes on more debt to support infrastructure projects. CoreWeave also raised about $18 billion through a mix of debt, equity, and convertible securities. Although debt remains a major funding source, the company is not relying solely on borrowing to finance its growth.
However, if lenders demand higher returns to lend to CoreWeave, the company’s borrowing costs will rise. This would leave less money for expansion and make it harder to fund new projects. Since CoreWeave needs steady investment to keep growing, higher debt costs could slow its progress. This is worth keeping an eye on.
The Bull Case Has Not Disappeared
CoreWeave has the opportunity to turn sentiment around, thanks to a $104 billion backlog and fast revenue growth. However, it needs to increase capacity, convert customer commitments into cash flow, and manage its mounting interest bill. If it does so, today's heavy investment could support meaningful future growth.
While CoreWeave's debt risks are very real, I wouldn’t dump the stock just yet. Instead, I’d watch revenue growth, capital expenditures, interest costs, cash flow, debt, and any updates to its spending plans in the next third-quarter earnings report.
Investors should watch CoreWeave’s bond yields and the cost of insuring its debt. If these risk measures fall, it may signal growing confidence in the company’s ability to repay its debt. A turnaround is possible, but CoreWeave still needs to prove its AI business can deliver real financial returns, not just more contracts.
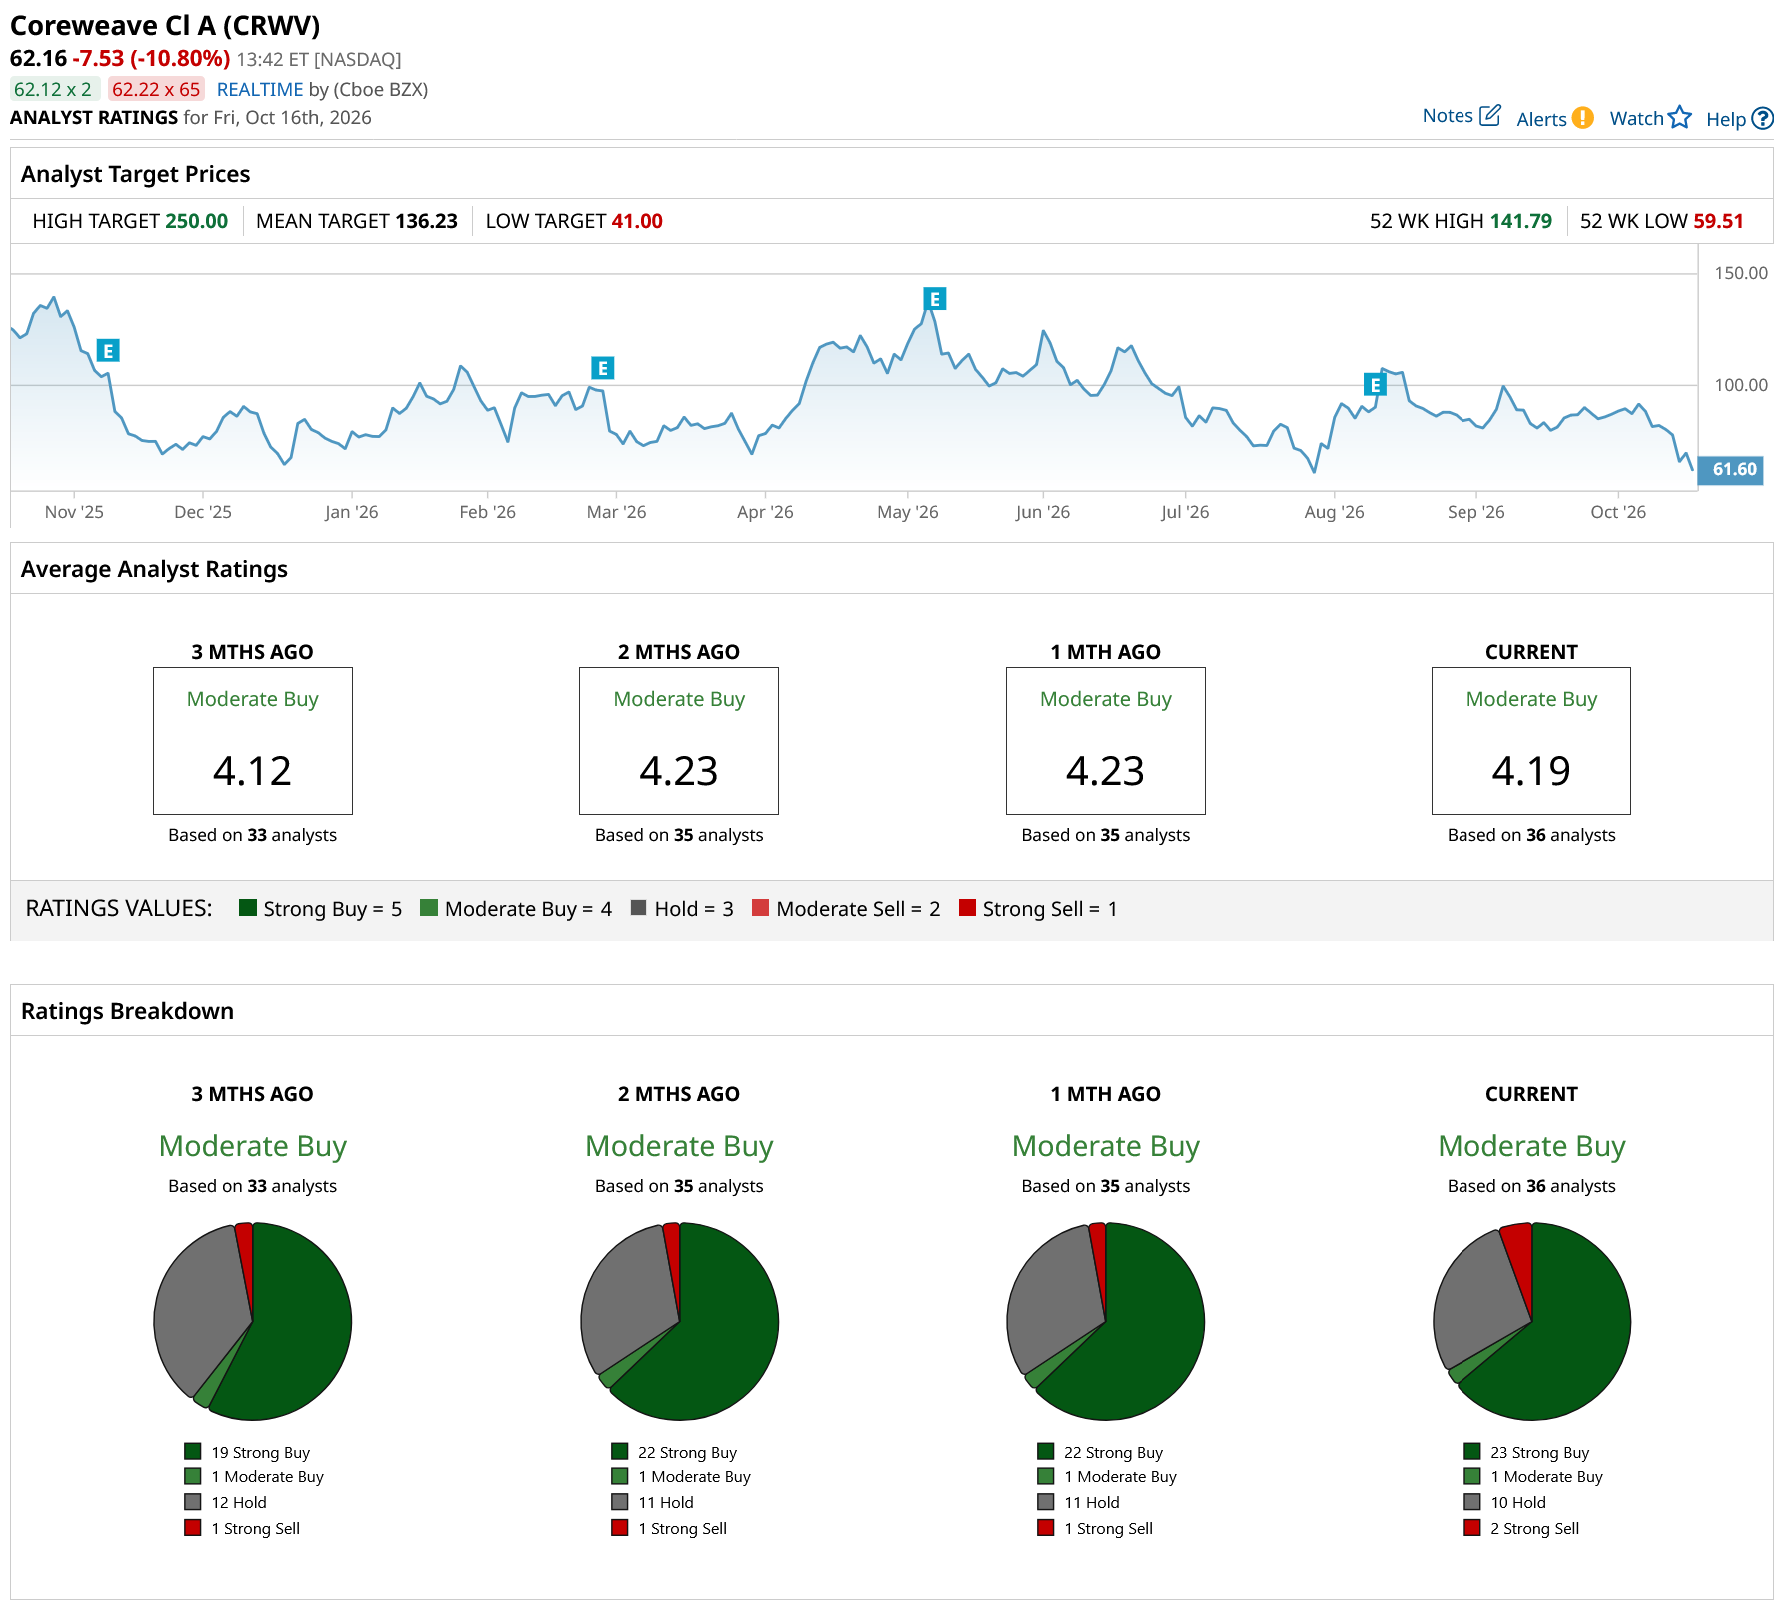
On Wall Street, CRWV stock holds an overall “Moderate Buy” rating. Of 36 analysts covering the stock, 23 rate it a “Strong Buy,” one suggests a “Moderate Buy,” 10 rate it a “Hold,” and two rate it a “Strong Sell.” CWRV is down 14% year-to-date (YTD), but the average target price of $136.23 indicates 119% potential upside from current levels. Meanwhile, the high target price of $250 implies a potential 302% rally over the next 12 months.
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.