
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Cactus (WHD) Stock Already Pricing In Too Much Optimism?
Cactus has delivered a strong share price run over the past year, yet the recent pullback puts fresh focus on whether that climb lines up with the profits the business is generating. With the stock now around US$61.19, the key issue is whether investors are paying a level that its earnings can reasonably support.
- Cactus has gained 73.6% over the past year, which puts real pressure on the question of whether its current earnings justify that kind of re-rating.
- The company’s value story now leans heavily on how reliably it can convert its operations into consistent earnings and cash flow that back up the current share price.
- There is a second opinion on Cactus worth weighing. See what analysts think Cactus's shares could be worth.
The issue now is whether Cactus’s current price can be squared with its earnings power when set against a Fair Ratio benchmark.
If you want a broader watchlist of earnings led ideas while you assess Cactus, a focused screen of 33 high quality undervalued stocks can be a useful next step.
Has Cactus Run Too Far on Earnings?
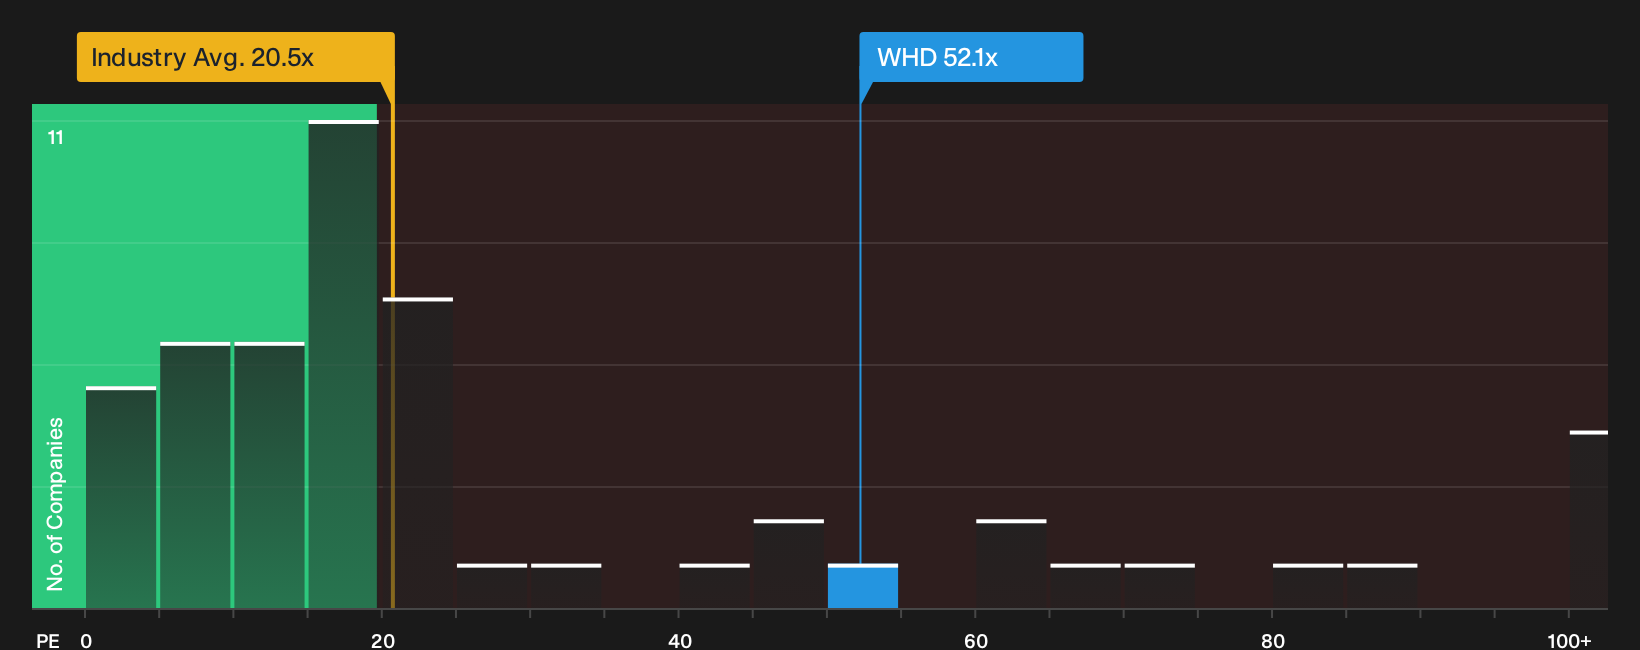
The P/E lens suits Cactus because earnings are the key driver investors are using to frame the story. On that measure, the stock trades on about 52.1x earnings, which is more than double the Energy Services industry average of roughly 20.5x. Relative to a broader peer group on about 14.7x, the gap is even wider and signals that the market is attaching a rich earnings tag to this business.
A Fair Ratio framework, which adjusts the P/E you might expect for Cactus based on its economics and risk profile, points to a lower multiple than where the shares trade today. That leaves the stock screening as overvalued on this earnings yardstick, so any holder needs to be confident that the underlying profit engine can justify paying so much more per dollar of earnings than is typical for the sector or peers. Explore the numbers behind Cactus's P/E valuation.
The Cactus Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation gap for Cactus leaves you by spelling out which paths for growth, profitability and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it appears today. Each scenario ties its number to a concrete view on how Cactus' revenue opportunity, margin profile and risk picture might shift, giving you a reference point you can revisit as new information lands.
On Cactus, community views split between those who see international growth and efficiency work supporting more upside and those who think valuation already prices in a lot of good news.
Bull case: 13% undervalued
"Heightened environmental scrutiny and the industry's preference for operational efficiency is spurring adoption of Cactus' proprietary, lower-leakage and streamlined wellhead systems..."
Discover why this Narrative puts Cactus at 13% undervalued.
Bear case: 7% overvalued
"Growing exposure to international and sour service spoolable pipe, including new orders in the Middle East and Africa, ties a larger portion of revenue to long lead, project based markets..."
Explore why this Narrative puts Cactus at 7% overvalued.
One more piece of the Cactus story worth checking
The final question is who is steering Cactus and how their pay is structured, because the way leaders are rewarded can quietly shape every decision that feeds into future results. See who runs Cactus and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com