
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Fonterra Co-operative Group (NZSE:FCG) Secures Solar Power Deal, Is It Still Below Fair Value?
Fonterra Co-operative Group (NZSE:FCG) has signed a second long term Power Purchase Agreement with Anza Power for electricity from the 110 MW Karioi Solar Farm, reinforcing its shift away from fossil fuel boilers.
Recent trading suggests interest in Fonterra Co-operative Group is building, with the share price at NZ$5.42 and a 30-day share price return of 17.83%. The 1-year total shareholder return of 61.48% and very large 3-year total shareholder return near 5x indicate long term holders have already seen substantial gains.
Scan beyond Fonterra Co-operative Group and see which other dairy and consumer stocks are showing strong momentum in our curated 618 high quality undiscovered gems list.
After a 61.48% 1-year total return and a share price at NZ$5.42, Fonterra Co-operative Group now trades against valuation estimates that imply a wide intrinsic value gap. So where does fair value really sit?
Preferred P/E of 9.6x for Fonterra Co-operative Group: Is it justified?
On Simply Wall St's estimates, Fonterra Co-operative Group is trading at about 77.3% below an intrinsic value estimate based on discounted future cash flows, with the share price at NZ$5.42 against a model value of roughly NZ$23.85. In that context, the current P/E of 9.6x hints at a valuation that is restrained compared to where some models place the business.
The P/E ratio compares the share price with earnings per share and gives you a quick sense of how much the market is paying for each dollar of profit. For a large dairy exporter like Fonterra Co-operative Group, which generated NZ$25,398.0m of revenue and NZ$1,346.0m of net income with 5.3% net margins, this metric offers a straightforward way to line up the stock against both local peers and global food producers.
Several pieces of the puzzle point in the same direction. Earnings have grown 12.1% per year over the past 5 years, with profit growth of 32.9% over the latest year and an improvement in net margins from 4.2% to 5.3%. Return on equity at 21.5% is classified as high, earnings are described as high quality, and the SWS DCF model currently treats the shares as undervalued relative to a future cash flow value of NZ$23.85. With that in mind, a single digit P/E suggests the market is placing a relatively low multiple on those earnings.
The comparison with peers sharpens that picture. Fonterra Co-operative Group trades on a P/E of 9.6x, while the peer group average sits at 19.6x and the wider global food industry average is 14.9x. That represents a steep discount to both the direct peer set and the broader sector, which points to a market valuation that is materially lower than what similar businesses are getting elsewhere.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 9.6x (UNDERVALUED).
Still, that discount can unwind quickly if dairy demand in key regions like China or Asia weakens, or if input costs pressure Fonterra Co-operative Group's current margins.
Find out about the key risks to this Fonterra Co-operative Group narrative.
Another view on Fonterra Co-operative Group's value
The P/E discount paints Fonterra Co-operative Group as inexpensive, yet the SWS DCF model goes further. That cash flow approach points to an intrinsic value of NZ$23.85 per share versus the current NZ$5.42. This indicates a wide gap that could reflect either opportunity or mispricing.
Look into how the SWS DCF model arrives at its fair value.
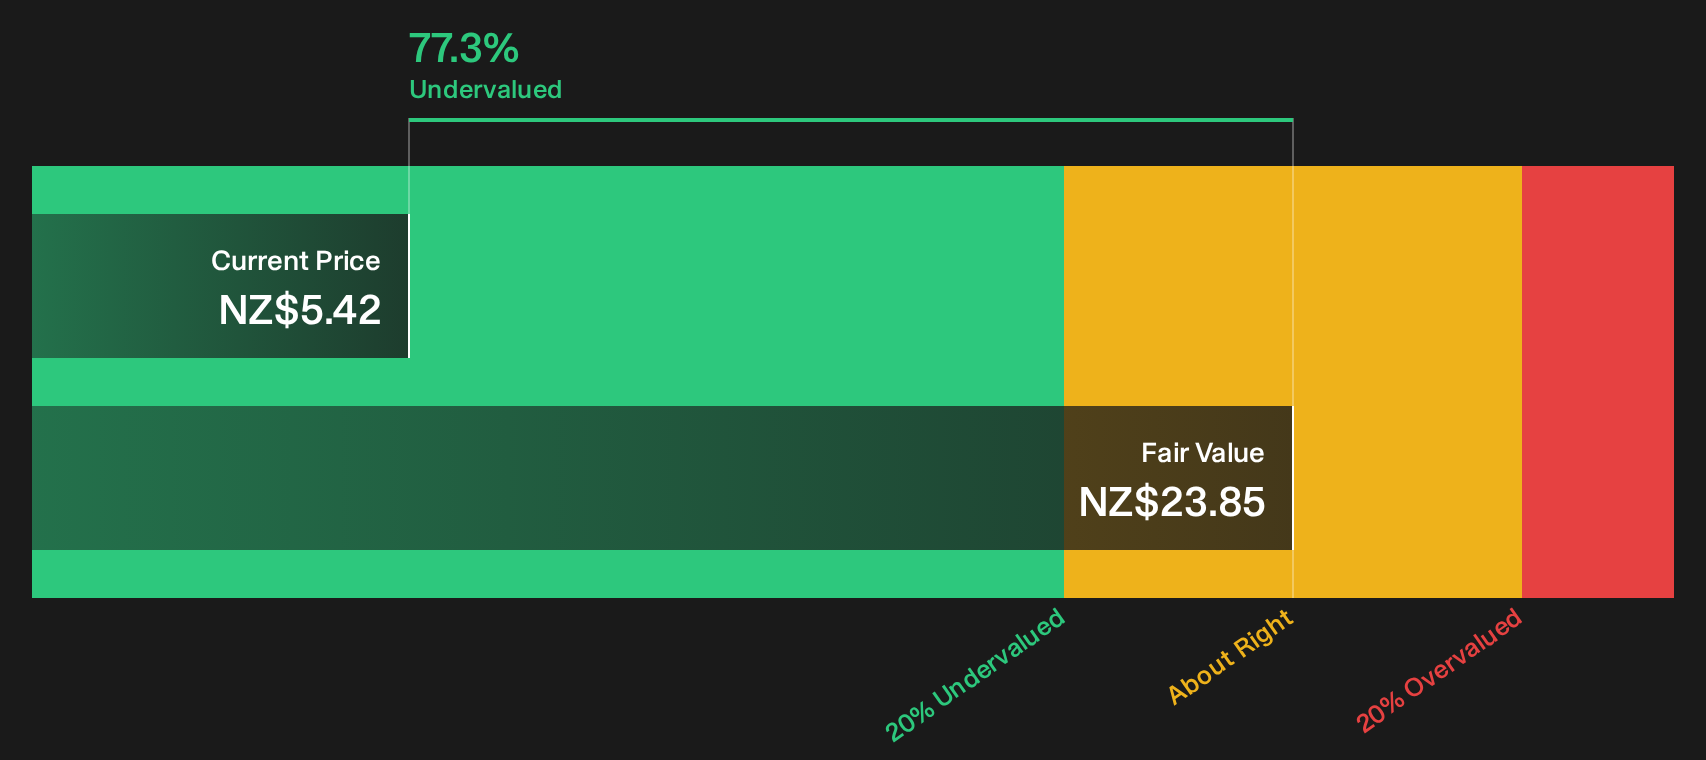
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fonterra Co-operative Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
There is a mix of optimism and caution around Fonterra Co-operative Group right now. Treat this as a prompt to review the underlying figures, weigh both the potential upside and the red flags, then reach your own verdict with the help of our 2 key rewards and 1 important warning sign
Ready for more ideas beyond Fonterra Co-operative Group?
If Fonterra Co-operative Group has you thinking harder about valuation gaps and momentum, do not stop here. Broaden your watchlist and pressure test your next moves.
- Target potential value opportunities by scanning our 193 high quality undervalued stocks that match solid fundamentals with appealing price tags.
- Strengthen your focus on resilience by using the 231 resilient stocks with low risk scores to look for companies with more stable risk profiles.
- Spot fresh opportunities before the crowd by checking the 618 high quality undiscovered gems built around under-the-radar businesses with strong underlying data.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com