
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What EssilorLuxottica Holders Got Wrong Before The Slide
EssilorLuxottica Société anonyme kept reporting higher revenue and profit, yet the share price moved in the opposite direction. For EssilorLuxottica Société anonyme shareholders, the loss over the past year was 45.0%, including dividends. If you had been weighing the bullish call for rising optical demand against warnings on digital disruption and governance risk in October 2025, which signals would have looked most decisive before that gap between business progress and portfolio reality opened up?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
This theme extends beyond EssilorLuxottica Société anonyme. See which of 128 healthcare AI stocks may still merit a closer look.
The Argument EssilorLuxottica Investors Were Weighing Up
The shares cost €270 at the start of the period, and EssilorLuxottica Société anonyme sat between two very different but reasonable stories about where the value might sit.
On the optimistic side, the bullish narrative put Fair Value at €302, or 12% above the start price. This view hinged on screens and global aging supporting demand, while smart eyewear and myopia management expanded recurring MedTech style revenue.
The cautious view set Fair Value at €180, or 33% below the start price. This perspective focused on digital commerce undercutting physical retail and on higher regulatory and execution risks from MedTech and health data exposure.
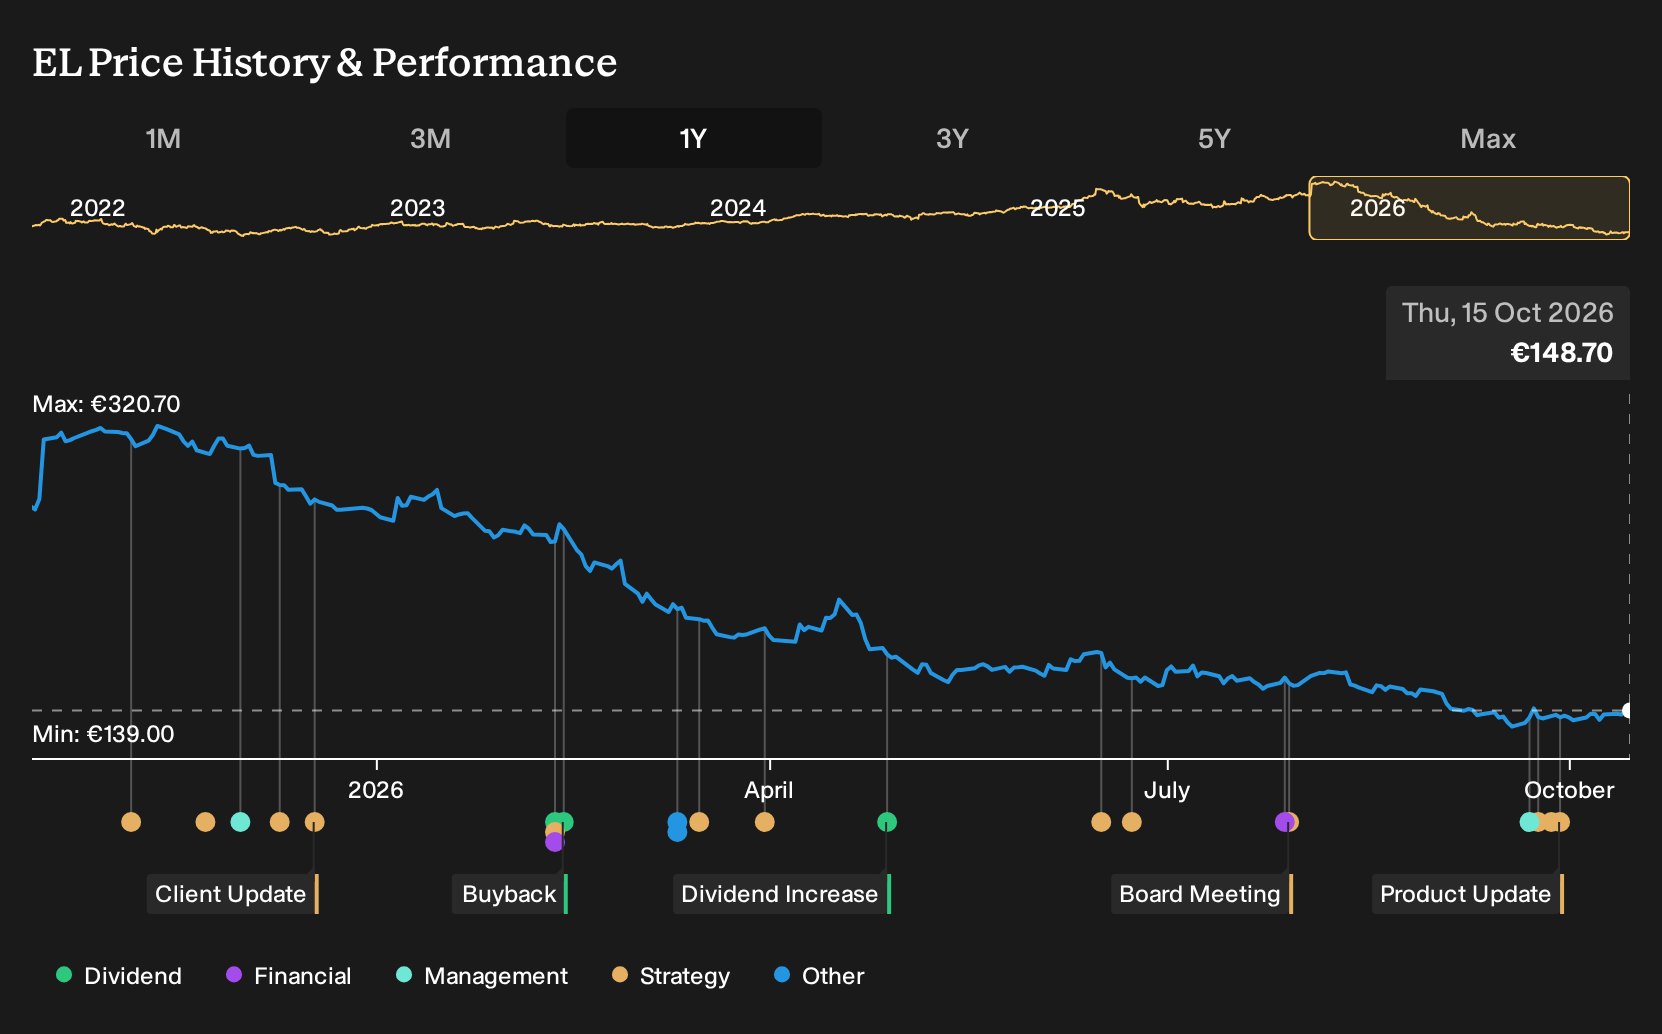
What The Evidence Did To The EssilorLuxottica Argument
EssilorLuxottica reported H1 2026 revenue of €14,818m and net income of €1,566m, with net margin rising to 10.6%. That outcome backed the bullish case that the business could grow sales and profitability together, even as smart eyewear and MedTech scaled. Governance frictions around Delfin control and Leonardo Maria Del Vecchio’s resignation challenged that strength. Overall, the evidence cut both ways.
The lesson is simple. When a story leans on pricing power and capital discipline, you track net margin and capital allocation moves such as buybacks and stock dividends, and then compare them with any governance changes that could alter who makes those calls.
What EssilorLuxottica's Lower Price Now Asks You To Believe
EssilorLuxottica trades at €149 today, with this Narrative’s Fair Value sitting above that level based on its own assessment. The argument leans on product development in smart glasses, hearing support eyewear, and myopia management, tied to deeper direct relationships with wearers and eye care professionals.
For that higher Fair Value to be reached, a buyer today would need to assume EssilorLuxottica turns these projects into durable, recurring revenue without eroding margins.
"Investments in smart eyewear, AI-enabled vision solutions, and MedTech (Ray-Ban Meta, Oakley Meta, Nuance Audio, acquisition of Optegra Eye Clinics) capitalize on long-term demand for technologically advanced and personalized eye health platforms, catalyzing product mix upgrades and higher ASPs, which will benefit gross margin and future earnings."
One Narrative disagrees with today's price. → See where this Narrative says EssilorLuxottica Société anonyme should trade
Where EssilorLuxottica’s Story Rhymes Elsewhere
EssilorLuxottica asks you to think about recurring eye care needs. One step away, hospitals face a similar pattern in surgery.
High end surgical robots are costly to install. The real economic engine comes from the tools, software and upkeep surrounding them.
Each procedure consumes specialized instruments and follows tightly controlled maintenance cycles. That pattern turns a one off sale into repeat spending over time.
If EssilorLuxottica executes on MedTech style platforms, this parallel matters. Recurring use, not hardware headlines, could quietly reshape where value accumulates.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 24% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com