
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Halted Refinery Strikes Require Action From Oil Refineries (TASE:ORL) Investors?
- In recent remarks, President Volodymyr Zelenskyy criticized ongoing Russian strikes on Ukraine's power infrastructure, while confirming that Ukraine has halted its earlier campaign against Russian oil refineries.
- This pause in refinery attacks reduces immediate physical risk to Russian fuel assets, yet keeps Oil Refineries exposed to possible pricing swings driven by energy infrastructure disruptions and geopolitical uncertainty.
- We will look at how the investment narrative for Oil Refineries could be influenced by the halt to Ukrainian strikes on Russian refineries.
Scan opportunities beyond Oil Refineries by reviewing 41 power grid technology and infrastructure stocks, which could be sensitive to the same energy infrastructure and geopolitical currents driving today’s headlines.
What Is Oil Refineries' Investment Narrative?
For an investor to own Oil Refineries, the core belief is simple. You need to think a complex, capital heavy refining and polymers platform in Haifa can keep running reliably, sell into steady fuel and petrochemical demand, and earn enough on each barrel and ton to justify the cyclical ride. The firm is valued on a low P/E of 5.7x and is trading about 23.3% below one cash flow based estimate, which already bakes in its recent move back to profitability.
The Ukraine war headline matters mainly through input and product pricing rather than direct operational exposure. Zelenskyy’s pause on strikes against Russian refineries eases one near term supply scare, but refining margins and crude costs can still swing on broader energy infrastructure risks. For Oil Refineries, the bigger immediate issues remain execution, the quality of earnings given a large one off gain of about $240m, and the fact that interest payments are not well covered by profits while earnings have trended weaker over 5 years.
Yet there is a catch in the Oil Refineries story that sits uncomfortably next to the apparent value on offer...
There's only one way to know the right time to buy, sell or hold Oil Refineries. Head to Simply Wall St's company report for the latest analysis of Oil Refineries's Fair Value.
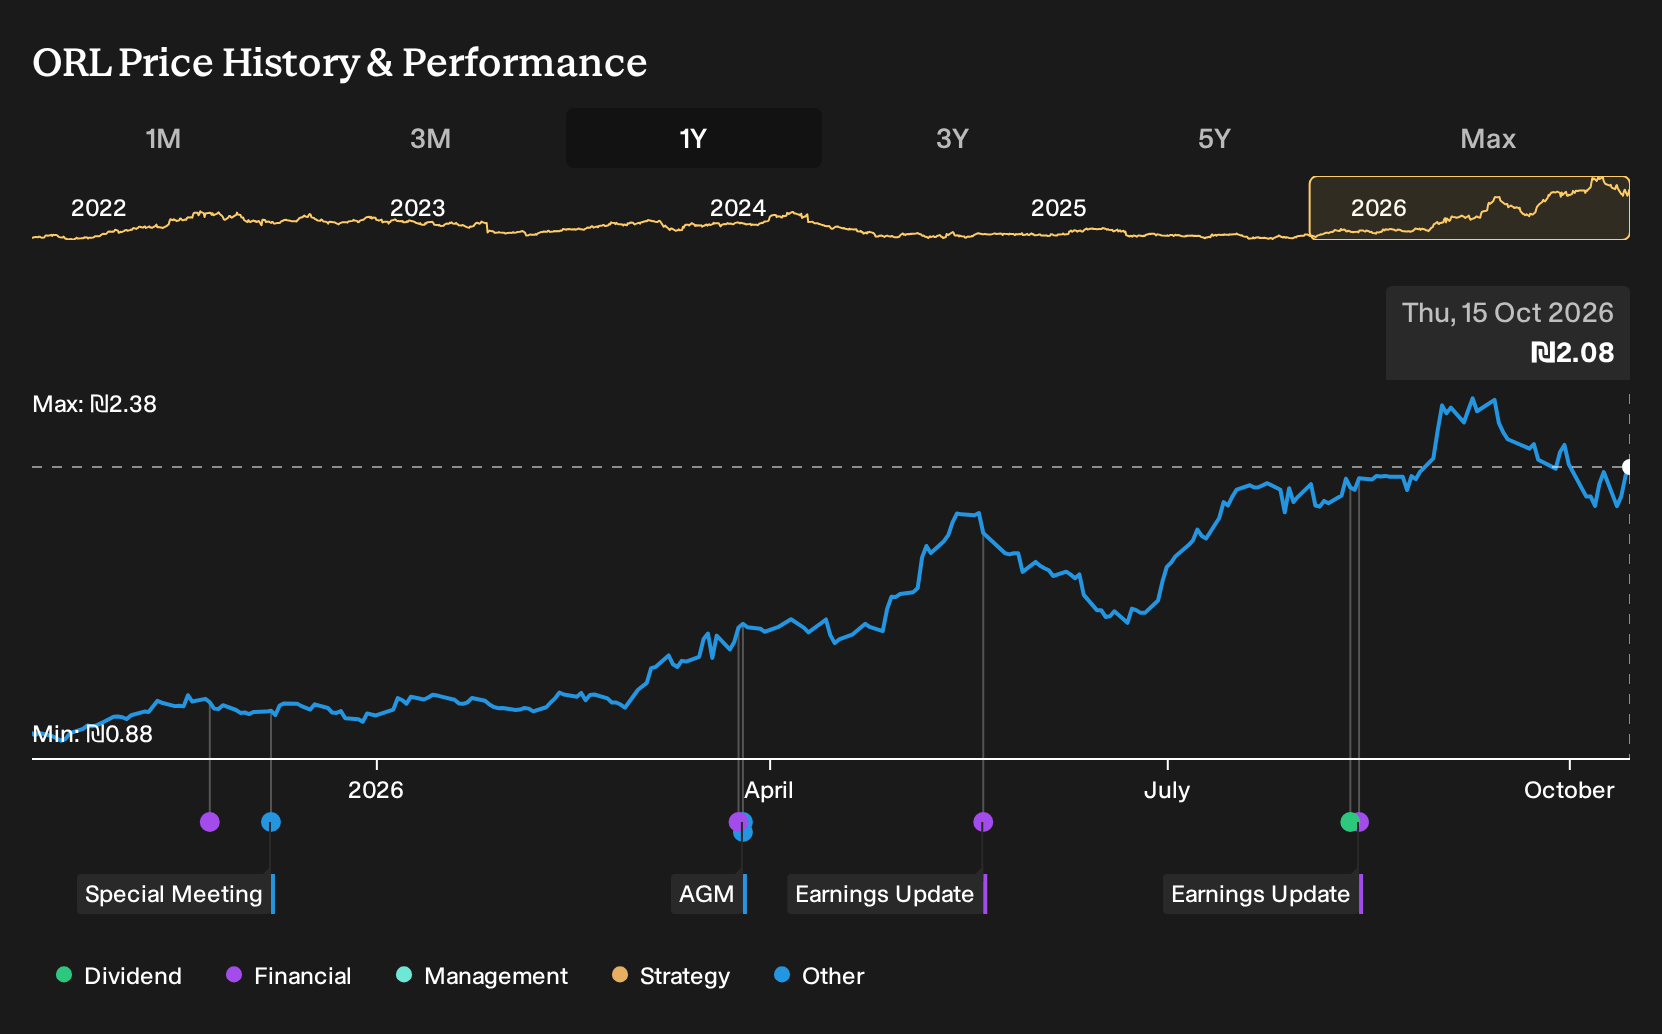
Exploring Other Perspectives
Only two fair value views from the Simply Wall St Community are on record for Oil Refineries, yet they already span a wide band from 1.099662 to 2.708888 times the current price. Those figures were set before Zelenskyy paused strikes on Russian refineries, so you may want to recheck these community viewpoints as geopolitics reshape energy pricing risk.
Explore another Oil Refineries fair value estimate, including one that suggests as much as 47% downside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Oil Refineries research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Oil Refineries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Oil Refineries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Oil Refineries?
If the situation around Oil Refineries has sharpened your appetite for opportunities linked to energy, infrastructure, or balance sheet strength, it can help to widen the lens and compare it with other businesses facing different risk and reward profiles.
The Simply Wall St Screener lets you quickly filter the market using fundamental criteria so you can focus on a shortlist that fits your own return goals and risk limits.
- For investors hunting for companies that might be overlooked yet financially robust, take a look at 617 high quality undiscovered gems that could warrant a spot on your watchlist.
- If capital preservation and lower volatility matter most, consider starting with 227 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Income focused readers who want potential cash flow from dividends as well as price moves can review 217 dividend fortresses that meet a higher yield threshold.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com