
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Space Force Contract Win Could Change The Case For SES Stock
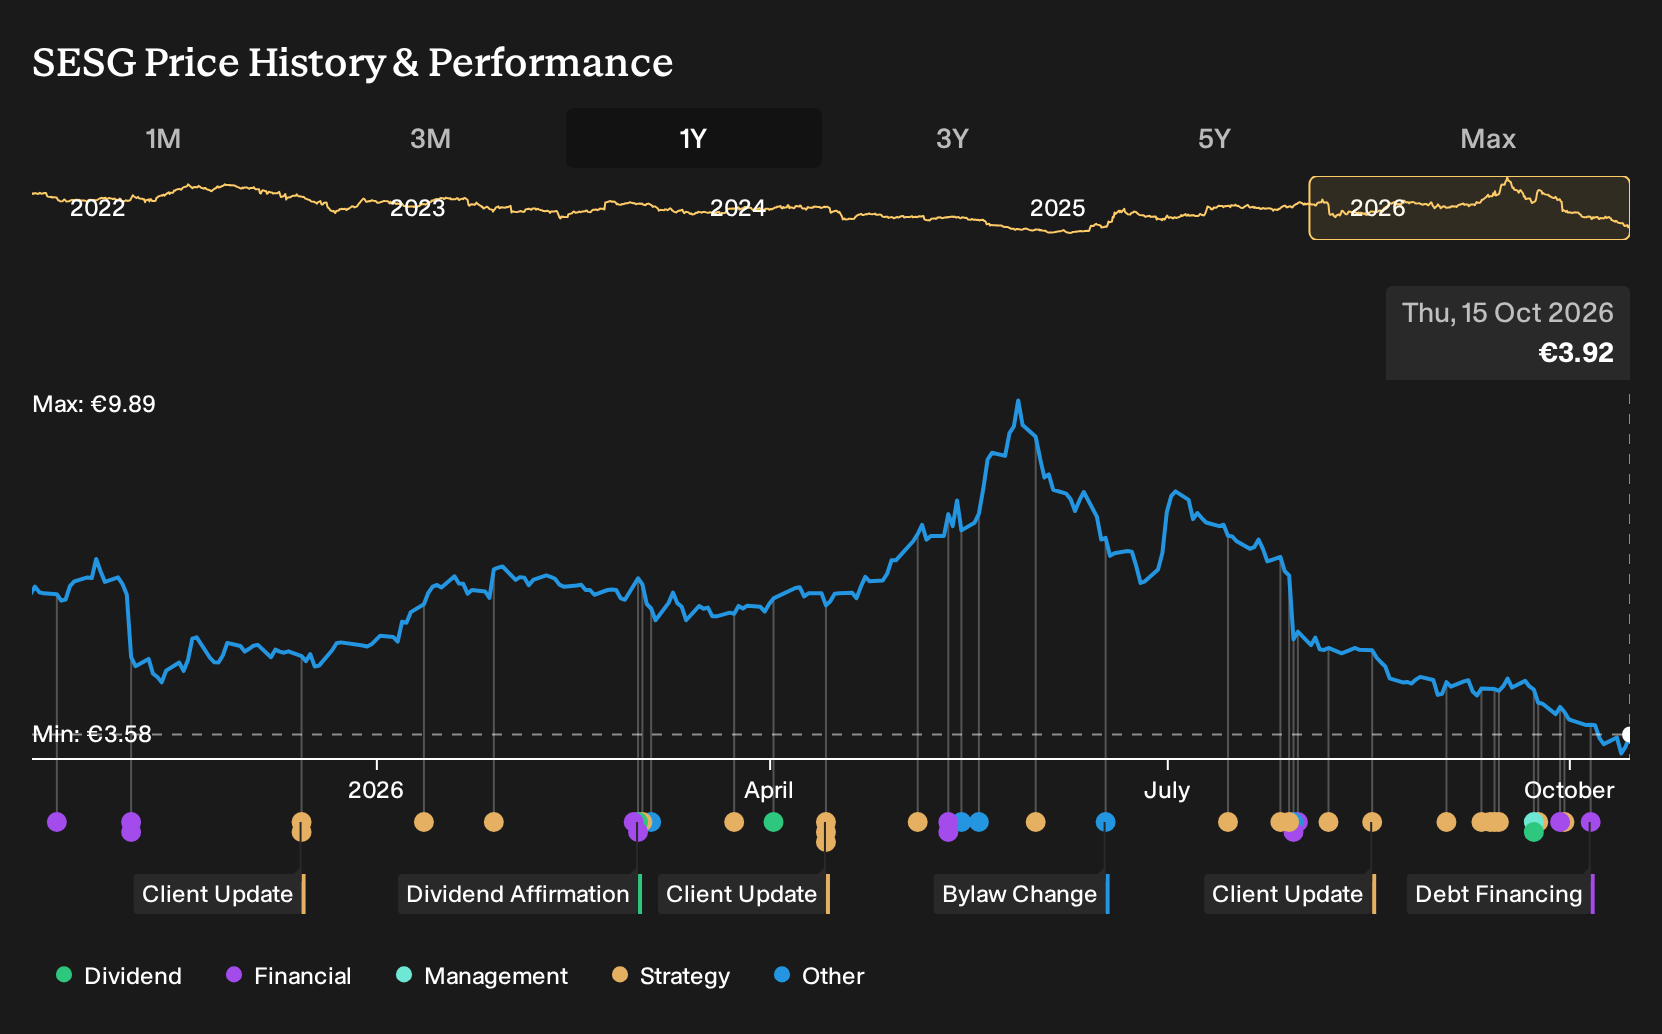
- SES announced in early October 2026 that it would purchase €363,397,000 of its €500,000,000 0.875% Guaranteed Notes due November 2027 at a price of 97.330% with no pro rata scaling following valid tenders.
- The U.S. Space Force selecting SES’s Lyntris division as prime payload integrator for the Protected Tactical Satellite Communications Global program highlights the group’s focus on government and secure connectivity contracts, alongside active balance sheet management.
- The U.S. Space Force payload integration award could reshape SES’s investment narrative.
SES Investment Narrative Recap
To own SES, you need to be comfortable with a connectivity business that is pouring money into multi orbit infrastructure while traditional video faces structural pressure. The thesis leans on Networks, including government and mobility, gradually doing more of the heavy lifting as Media stays cash generative but less central. The US Space Force work and IRIS2 projects sit right in that story.
In the short term, the key swing factor is execution on large government and aviation contracts versus the drag from weak Fixed Data and a still loss making group. Balance sheet risk remains front of mind, given interest costs and a dividend that is not covered by earnings or free cash flow.
The recent debt tender for €363,397,000 of the €500,000,000 notes due November 2027 is the most relevant near term move. Retiring a sizeable part of this 0.875% issue at a 97.330% price slightly reshapes SES’s funding mix and reduces upcoming maturities, while still leaving the group with meaningful borrowings to service.
For investors, this tender links directly to both catalysts and risk. Heavy CapEx of about €700 million in 2026, integration of Intelsat and reliance on higher risk funding mean that any step to simplify liabilities matters. The trade off is that cash spent on repurchasing debt competes with investment in O3b mPOWER, meoSphere and future free cash flow repair.
SES Forecasts And What Needs To Go Right
SES' narrative projects €3.4b revenue and €81.6 million earnings by 2029. This assumes 5.1% yearly revenue growth and an earnings swing of about €232.6 million from a loss of €151.0 million today.
Those analyst assumptions sketch out a sharp shift in the income statement. Profit margins are expected to move from a 5.1% loss today to a 2.4% profit in roughly three years. This implies that SES must turn heavy investment projects like O3b mPOWER, meoSphere and IRIS2 into paying capacity rather than stranded capital.
On earnings, the consensus points to €81.6 million by 2029, but the spread is wide. Forecasts run from a €551.8 million profit at the optimistic end to a loss of €83.0 million at the cautious end. You are therefore dealing with a story where small changes in contract timing, utilisation or CapEx discipline could swing outcomes materially.
To back the current analyst view, an investor would need to be comfortable with SES trading on a 55.4x P/E multiple on those 2029 earnings, compared with a current P/E of 21.2x on loss making numbers and a GB Media sector level of 14.2x. That implies a willingness to pay a premium for multi orbit exposure, government contracts and potential deleveraging in exchange for accepting execution risk on integration and capital spending.
Revenue expectations also build in some balance sheet and capital structure assumptions. Analysts are baking in share count growth of about 0.61% a year over the next three years and are using a discount rate around 8.7% to bring those 2029 numbers back to today. This effectively prices SES as a higher risk, capital intensive communications play rather than a mature, low leverage media utility.
The analyst consensus price target of €8.24 compares with a current share price of €7.67, which leaves about 7% implied upside in those models. That small gap suggests the average view is that SES already reflects a fair chunk of the multi orbit upgrade story, so any change in sentiment around government awards, IRIS2 execution or Intelsat integration could move the investment narrative quickly in either direction.
Uncover why SES' fair value indicates a 110% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You are seeing two very different stories about SES. The most cautious analysts focus on the risk that multi orbit projects like meoSphere and O3b mPOWER tie up cash while Media stays under pressure. Before this Space Force win, some were modelling revenue slipping toward about €3.1b by 2029 and earnings near €144.1 million. Those views were set before the contract awards and debt tender, so you may want to compare that pessimistic path with your own read on how these announcements could reshape SES over the next few years.
Explore 2 other SES fair value estimates, including one that suggests it could be worth just €7.54!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SES research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SES. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SES' overall financial health at a glance.
Looking For More Investment Ideas Beyond SES?
If the SES story has sparked ideas about where secure communications, cash flow resilience and balance sheet strength intersect, it can help to line that up against a broader watchlist built from clear, rules based stock sets.
- For investors who want to keep risk in check while still staying exposed to potential upside, scan our curated group of 227 resilient stocks with low risk scores that score well on resilience metrics.
- If valuation discipline matters most to you, review the 195 high quality undervalued stocks and see which businesses combine quality fundamentals with pricing that analysts view as attractive.
- Income focused readers can zero in on payout strength by reviewing the 217 dividend fortresses built around companies offering yields above 5% with a focus on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com