
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
JEOL (TSE:6951) Launches HAXIS As Questions Linger Over Whether The Stock Is Pricey
JEOL (TSE:6951) has scheduled the launch of its HAXIS low angle ion milling scanning electron microscope for sales beginning on 5 October 2026, targeting advanced semiconductor failure analysis workflows.
For context, JEOL’s share price has climbed to ¥7,720, with a 1 day share price return of 2.36% and a 30 day share price return of 8.44%. Despite some recent volatility, the year to date share price return of 53.33% and 3 year total shareholder return of 70.07% indicate momentum that longer term holders will be watching closely around launches like HAXIS.
Scan beyond JEOL and this HAXIS launch by comparing it with other precision tech players in the curated list of 91 robotics and automation stocks poised to benefit from semiconductor and automation demand.
After a 53.33% year to date run and a fresh HAXIS catalyst, JEOL still trades about 13% below consensus targets. Is that discount caution well placed, or an opportunity mispriced on recent enthusiasm?
Preferred P/E of 23.9x: Is It Justified For JEOL?
JEOL trades on a P/E of 23.9x against a last close of ¥7,720, while trading about 13% below the ¥8,740 analyst target. The question is whether that earnings multiple asks too much of future delivery.
The P/E ratio links what you pay per share to the profit that JEOL is currently generating. This is especially important for a specialist equipment supplier where earnings can swing with semiconductor and research spending cycles. A higher P/E usually signals that the market is willing to pay up for expected profit expansion, while a lower figure often points to more muted expectations or perceived risk.
Here, the stock is described as expensive versus the broader JP Electronic industry, with JEOL on 23.9x compared with an industry average of 15.7x. This is a sizeable premium for a company whose own net profit margin has edged slightly down from 9.7% to 9.6% and whose latest year earnings declined 19.2%. Against a peer group average P/E of 24.2x and an estimated fair P/E of 22.7x, the current multiple sits very close to peers but above the level that regression analysis suggests markets could eventually gravitate toward if sentiment cools.
Explore the SWS fair ratio for JEOL.
Result: Price-to-earnings of 23.9x (OVERVALUED).
Still, a premium P/E can come under pressure if semiconductor equipment demand softens, or if JEOL’s earnings volatility returns with a sharper downswing than analysts expect.
Find out about the key risks to this JEOL narrative.
Another View: What The SWS DCF Model Says About JEOL
The P/E premium hints at a rich price for JEOL, yet the SWS DCF model goes further and points to the shares trading above an estimated future cash flow value of ¥3,640.8. That gap frames JEOL as overvalued on cash flows and raises a simple question for you: Which signal carries more weight?
Look into how the SWS DCF model arrives at its fair value.
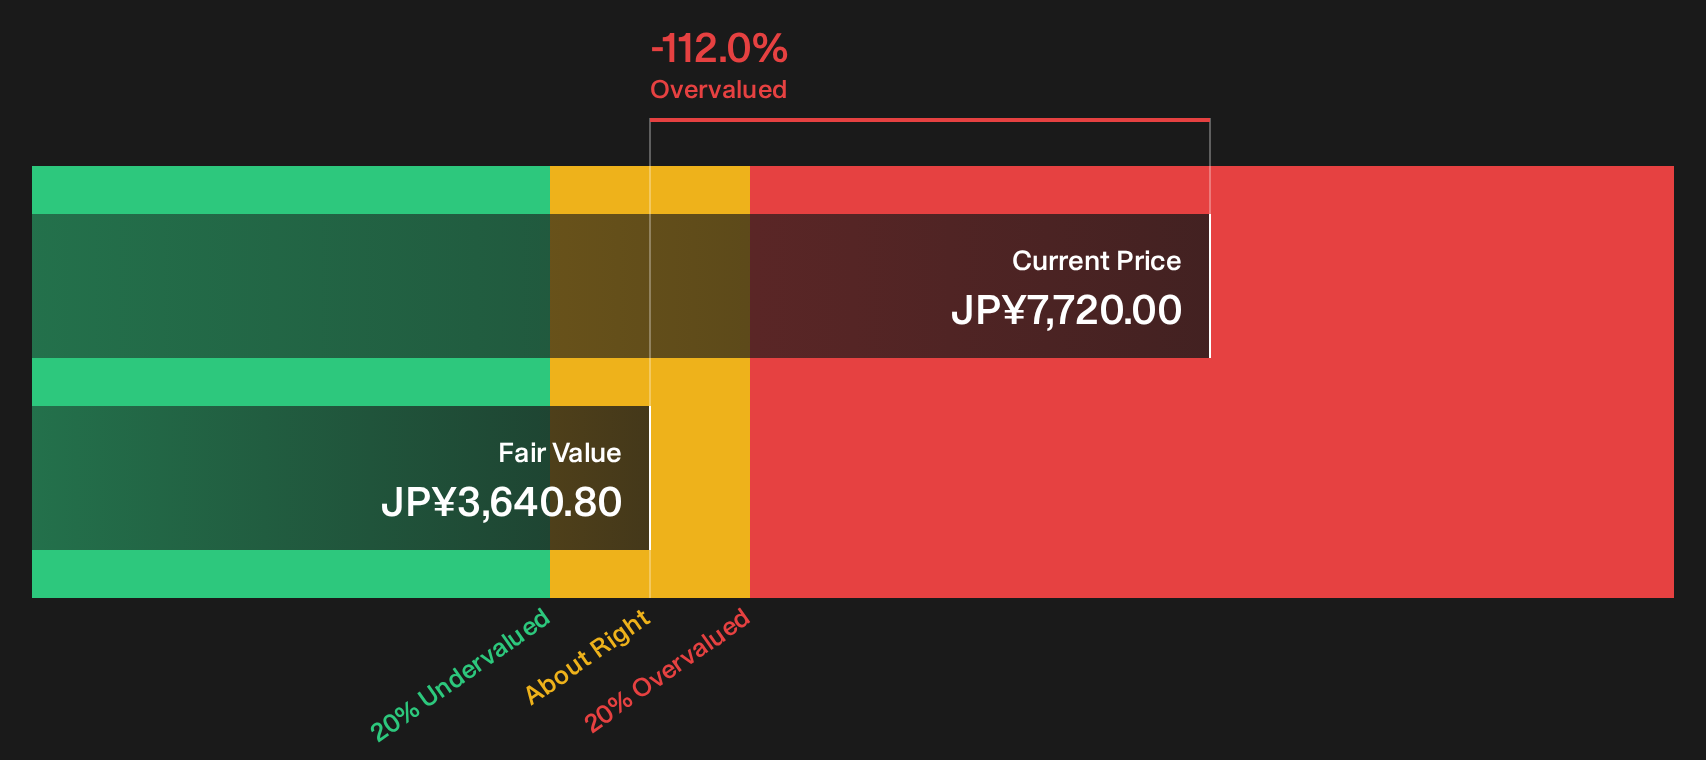
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out JEOL for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on JEOL valuation and risk rarely stay mixed for long. Move quickly, check the underlying data, and weigh the 1 key reward and 1 important warning sign.
Looking For More Ideas Beyond JEOL?
If you only stop at JEOL, you risk missing other compelling setups. Put a few minutes into broadening your watchlist and give your future self more options.
- Target reliable cash generators by scanning for companies on the list of solid balance sheet and fundamentals (21 results) that pair sturdy finances with room for better pricing.
- Hunt for mispriced potential and filter for stocks on the 14 high quality undervalued stocks that combine quality metrics with compressed market expectations.
- Seek resilient candidates and use the 22 resilient stocks with low risk scores to focus on businesses where risk scores stay contained even when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com