
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NBIS Stock Is Down 40% From Its 52-Week High. If You Buy It Now, You’re Betting on Nebius Recovering Amid Debt Concerns.
Investing in the stock market can be overwhelming because you need to consistently identify fundamentally strong companies. For instance, a company can double its revenue and still underperform by a wide margin due to high debt levels and a weak balance sheet.
Something similar is happening with Nebius (NBIS) and other neocloud stocks. These AI infrastructure companies are growing sales rapidly due to strong demand but are booking massive losses and negative free cash flow.
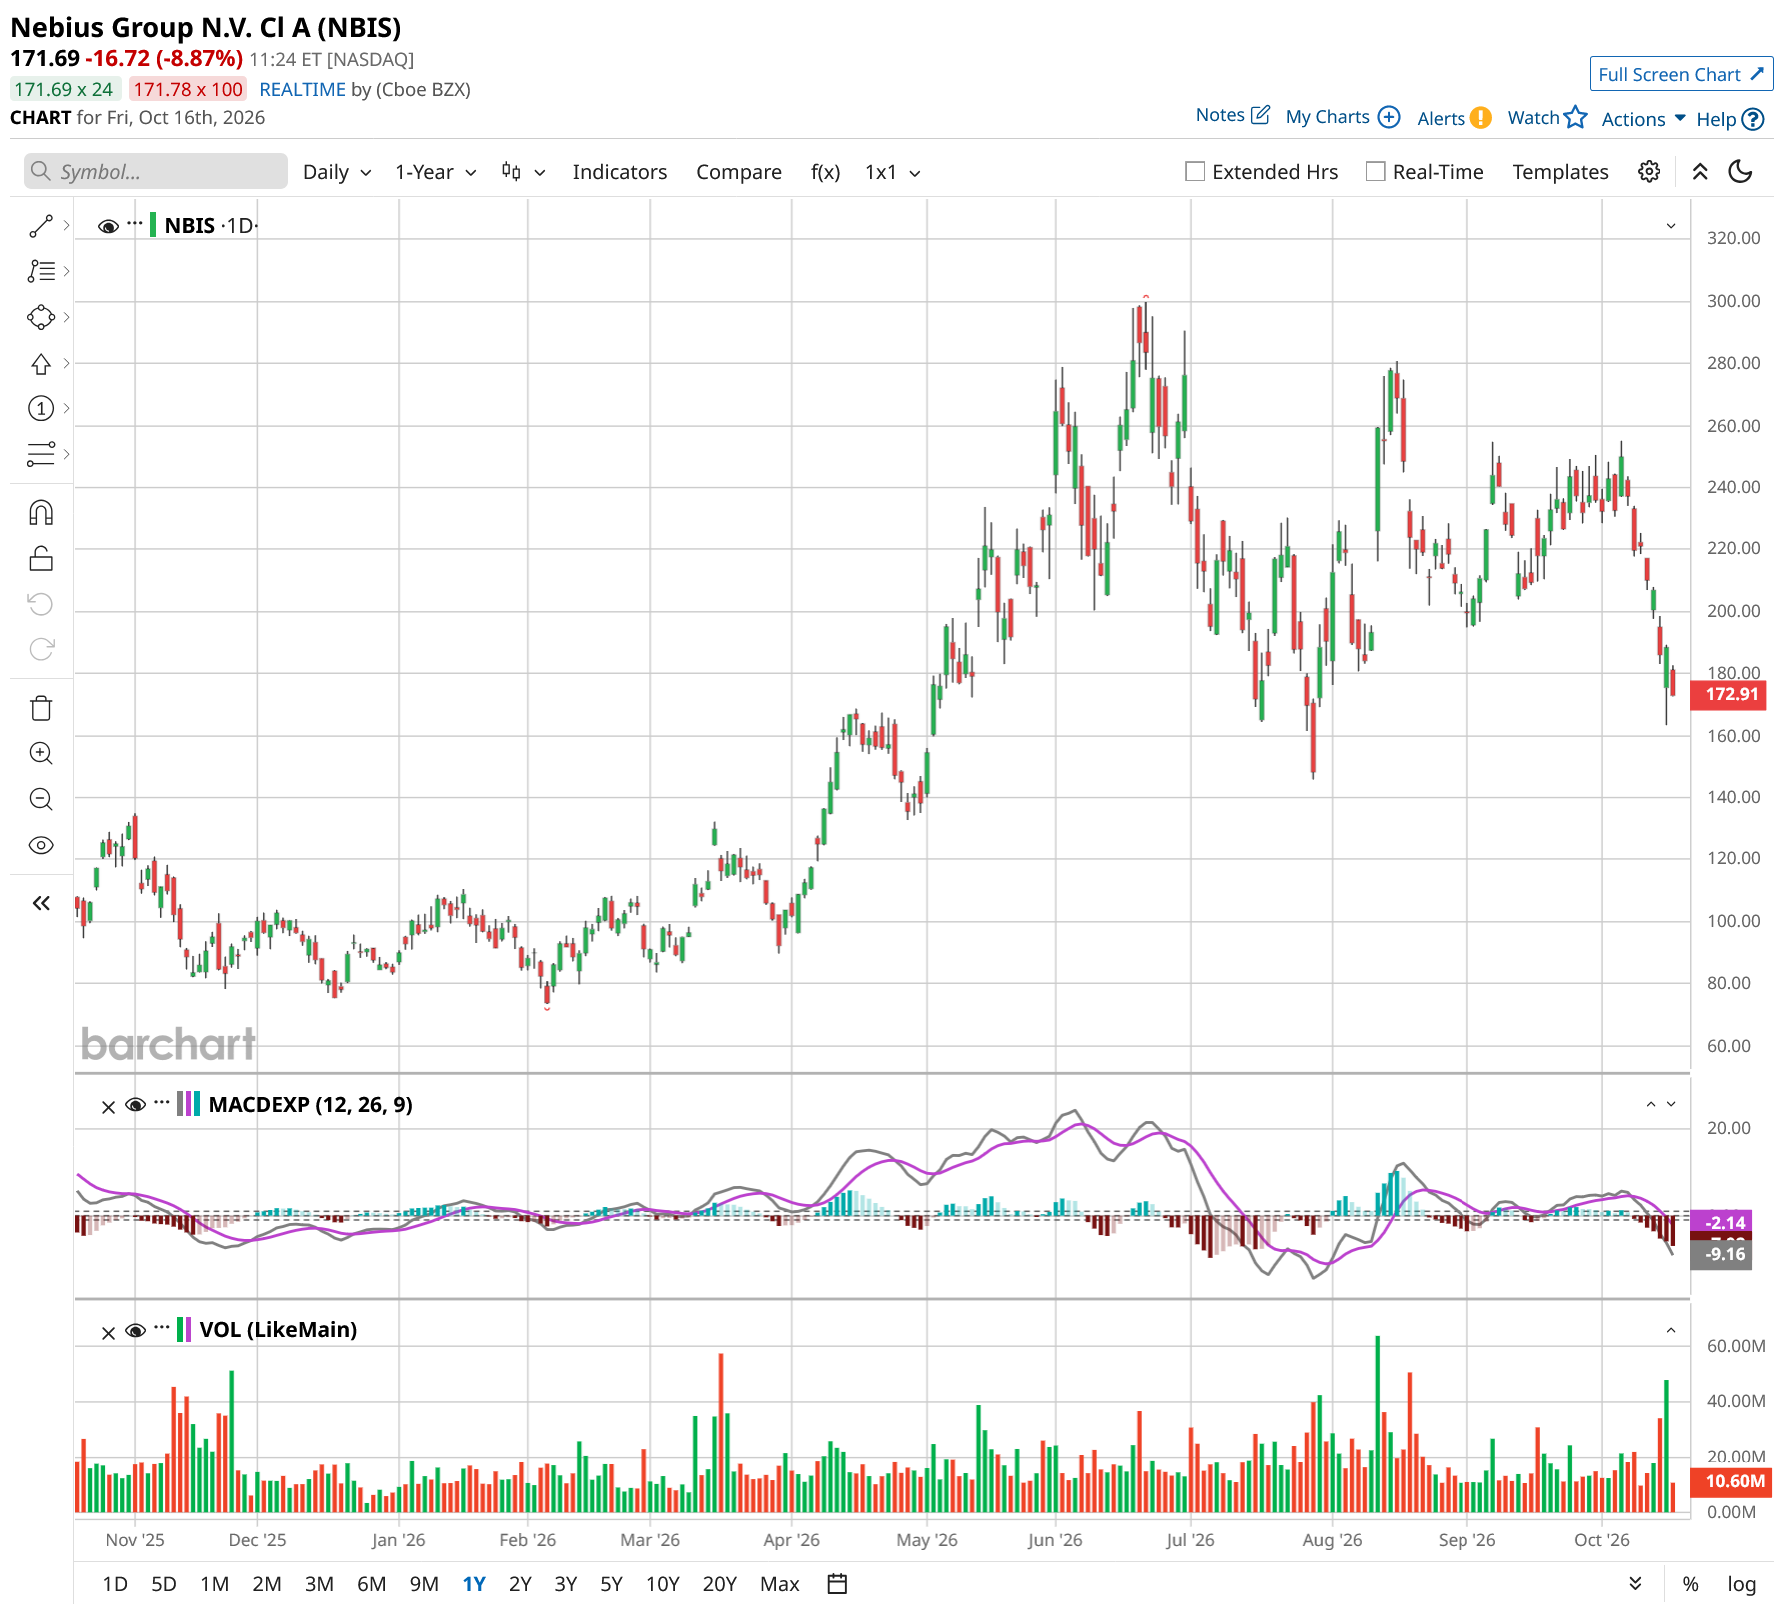
Down over 40% from its 52-week high, Nebius has a market cap of $47.6 billion as of October 2026.
Should you buy the dip in NBIS stock right now?
Why AI Computing Demand Is Massive
Nebius builds data centers, racks, and software that it rents to AI hyperscalers. CEO Arkady Volozh says AI demand far outpaces computing supply in 2026.
Volozh said Nebius started with several hundred engineers, one small 10-megawatt data center, and $2.5 billion in cash. Today, the company has raised $40 billion and contracted five gigawatts of capacity.
Volozh called the gap between demand and supply “a good problem to have,” speaking at Citi's 2026 Global TMT Conference on Sept. 9.
Think of a megawatt as a slice of data center power that Nebius rents out. Nebius initially charged about $10 million to $15 million per megawatt. Due to strong demand, it raised prices to $20 million to $25 million per megawatt. Customers who needed capacity right away even paid around $50 million on short-term contracts.
In Q2 2026:
- Nebius reported revenue of $582.3 million, up 454% year-over-year (YoY).
- In the March quarter, it posted $400 million in sales.
- Nebius reported gross margins of 77.1% and an operating loss of $176 million.
- However, operating margins narrowed from -105.8% to -30.2% over the last 12 months.
- The company lost $190.4 million, or $0.68 a share in Q2.
In the March quarter, Nebius reported net income of $621.2 million, powered by $800.5 million in non-operating income, which is not part of core business operations.
Nebius' Debt Is the Real Worry
Nebius ended Q2 with $8.5 billion in long-term debt, up from less than $1 billion last year. Its long-term debt was far lower at $4.1 billion in December 2025.
The company reported an interest expense of $119 million in Q2, up from $4.8 million last year.
Earnings before interest, taxes, depreciation, and amortization (EBITDA) stood at $118.4 million, lower than Q2 interest expenses. In plain terms, lenders took away more than every dollar of EBITDA Nebius earned.
Its cash balance fell from $9.3 billion to $8 billion over the last three months, while leases added another $1.5 billion in liabilities. Shares outstanding rose to 271.9 million from 238.7 million a year ago, up 14% YoY.
Net property, plant, and equipment jumped to $14.9 billion from $2.1 billion a year earlier. Building five gigawatts would cost $250 billion in financing, suggesting Nebius will need to raise significant capital to fund these purchases.
It can raise capital through debt, which will increase interest expenses, or through equity, which will dilute shareholder wealth.
What Gartner's Warning Means for Neoclouds
Gartner says AI data center owners need $8.5 trillion in cumulative revenue through 2030, which covers announced spending, financing costs, and a 12% return on invested capital. But Gartner expects no more than $3.6 trillion in AI revenue tied to those data centers.
The report says more than $3.5 trillion in AI infrastructure spending could be impaired by the end of 2030. Gartner also predicts that over 80% of neocloud providers will cease independent operations by 2030.
Gartner analyst Will Sommer said spending on AI-optimized infrastructure will grow too slowly for most providers to recover costs before they replace current chips. Spending is forecast at $66 billion in 2027 and $174 billion in 2030.
Gartner says hyperscalers have diversified revenue to ride this out, while neoclouds rely on a single, capital-intensive revenue stream.
Volozh argues Nebius runs a full stack, from data centers to software, and sells higher-priced products as well. He says the business model lets Nebius pay back its capital spending in 22 months.
My Take on NBIS Stock
The ongoing drawdown may accelerate over the next 12 months, especially if the AI bubble pops. Nebius is growing its debt pile faster than profits, making it a high-risk bet in an elevated interest-rate environment.
For a recovery, I would want to see three things.
- First, financing that doesn't further dilute shareholders.
- Second, demand holding up well past the current shortage.
- Third, more sales from higher-margin software products.
I would watch one number each quarter: EBITDA versus interest expense.
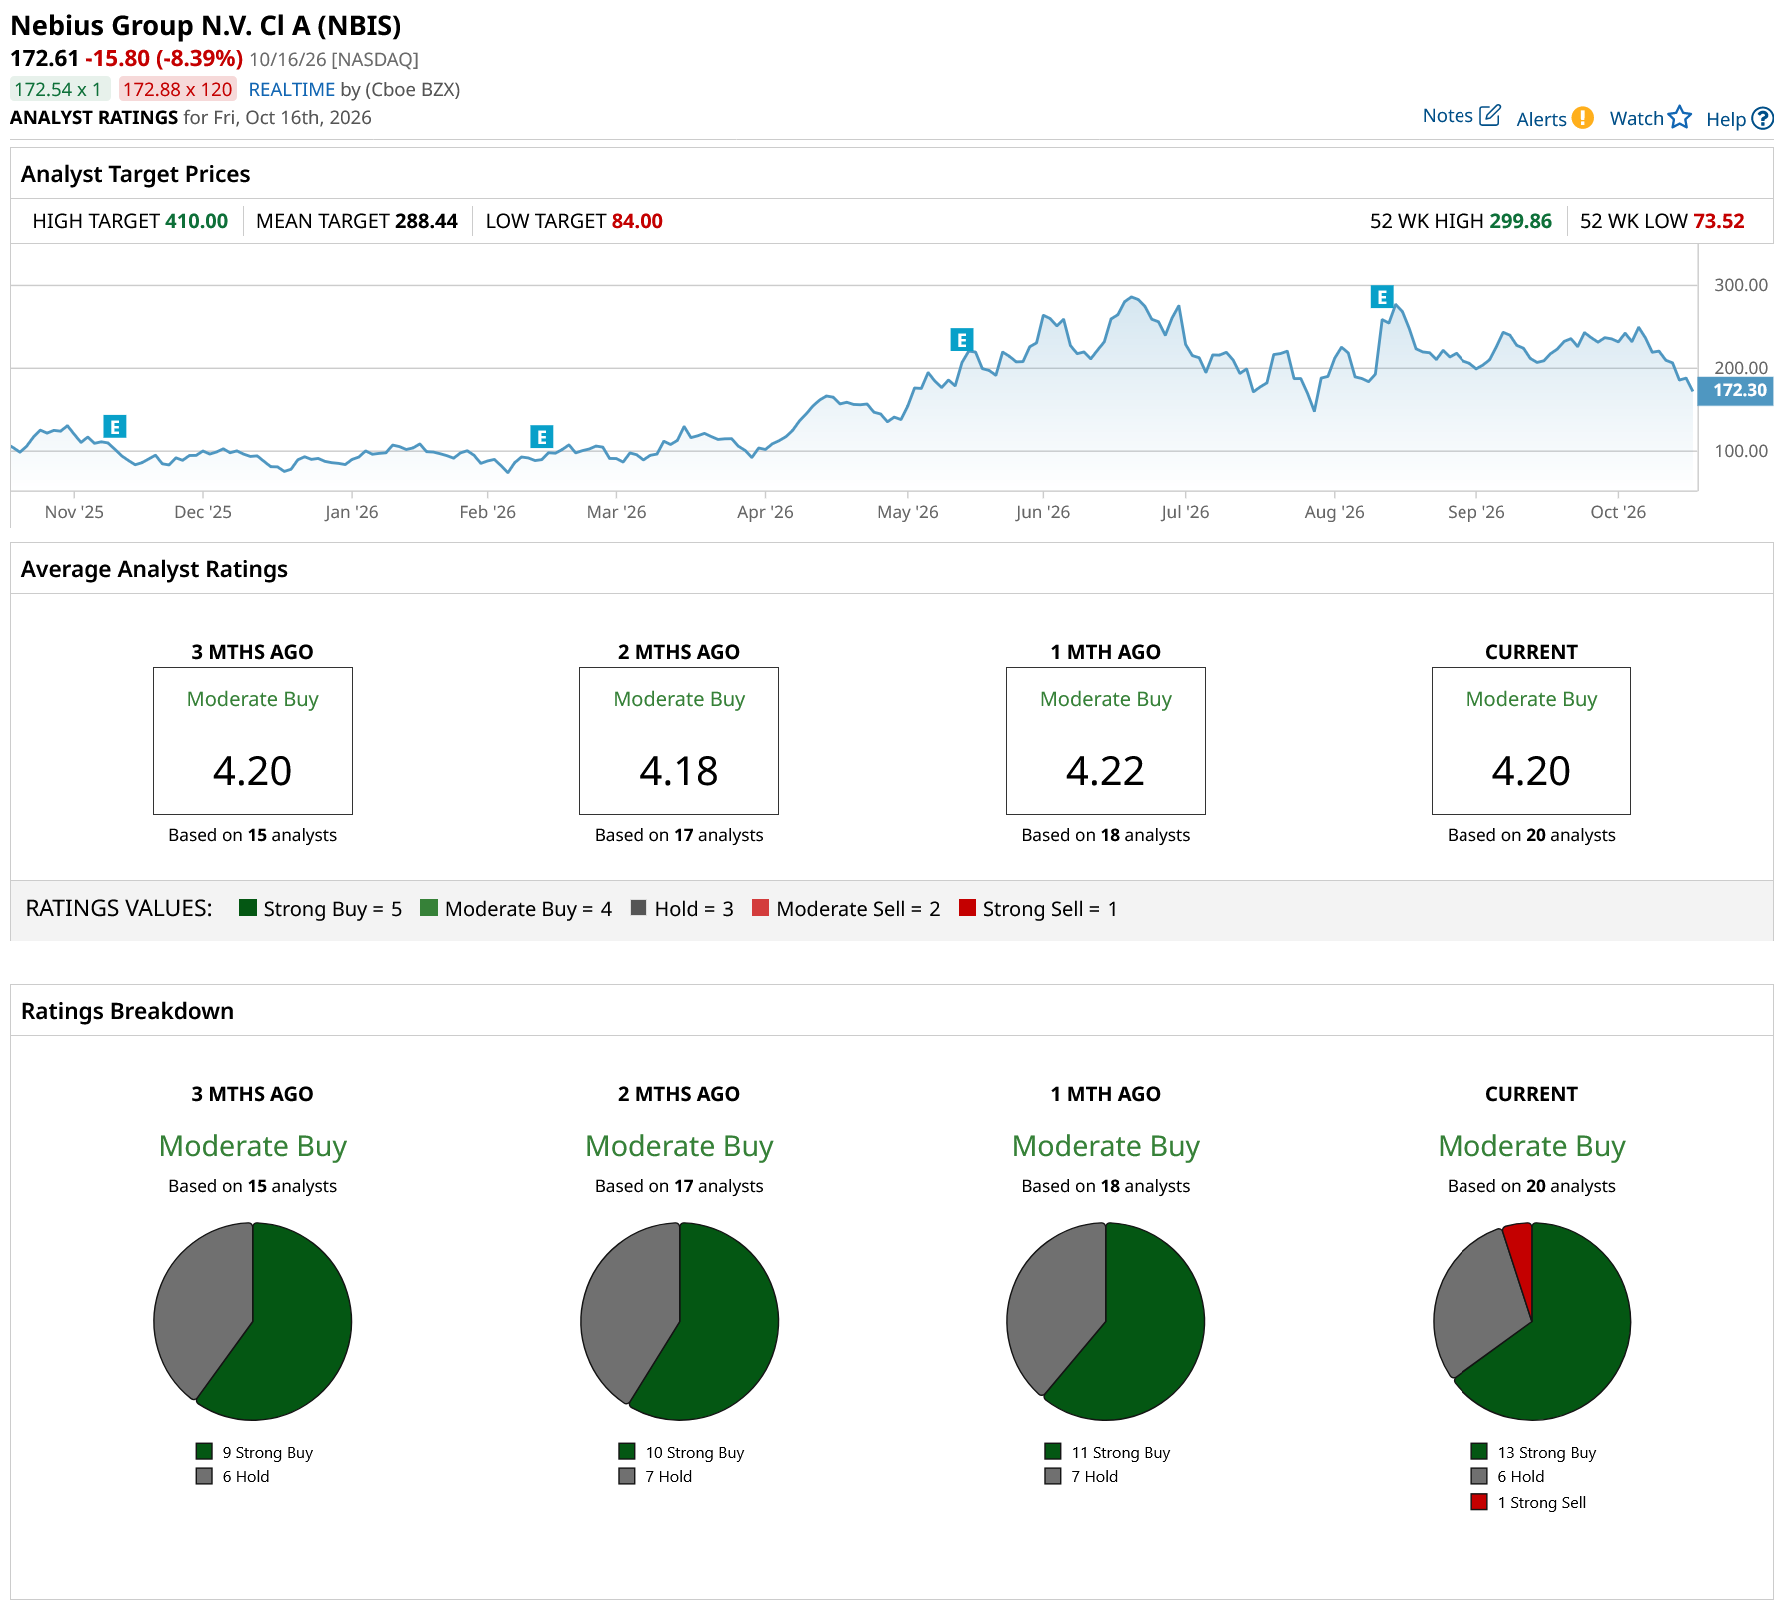
However, Wall Street remains bullish on NBIS stock. Out of the 20 analysts covering Nebius, 13 recommend “Strong Buy,” six recommend “Hold,” and one recommends “Strong Sell.” The average NBIS stock price target is $288.44, well above the current price of about $172.
On the date of publication, Aditya Raghunath did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.