
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Pacira BioSciences (PCRX), Why Is The Market Paying Closer Attention?
Pacira BioSciences (PCRX) is suddenly in focus after Viatris agreed to acquire the company in a US$1.6b cash deal, offering US$36.50 per share through a short tender offer.
Over the past month Pacira BioSciences has seen a 50.9% 30 day share price return and a 48.5% year to date share price return. The 1 year total shareholder return of 59.6% contrasts with a 5 year total shareholder return that remains down 31.6%, suggesting momentum is building recently after a tougher longer stretch.
Scan similar healthcare players that could be next on investors' radar by reviewing the hand picked 34 healthcare AI stocks alongside the Pacira BioSciences news.
Pacira BioSciences now trades within cents of the US$36.50 offer, while analyst targets and intrinsic estimates sit lower on average. Is the tender price a ceiling, or does the valuation work suggest more cushion than it appears?
Most Popular Narrative: 21.1% Overvalued
Pacira BioSciences last closed at $36.33, while the most followed narrative pegs fair value at $30.00 using a 7.24% discount rate. That gap puts the tender price in the context of a stock already trading well above this central intrinsic estimate.
Expansion of the EXPAREL patent estate to 21 listed patents, together with a volume-limited generic settlement that defers significant competition until at least 2030, provides a longer window to convert current utilization into sustained revenue and cash flow.
See why 11 investors see Pacira BioSciences as 21% overvalued.
Result: Fair Value of $30.00 (OVERVALUED)
Still, Pacira BioSciences leans heavily on EXPAREL reimbursement and faces the risk that pipeline trials or future policy decisions will not match current expectations.
Find out about the key risks to this Pacira BioSciences narrative.
Another View: Pacira BioSciences Through The SWS DCF Lens
While some commentary describes Pacira BioSciences as 21.1% overvalued at a fair value estimate of $30.00, the SWS DCF model presents a different perspective. It estimates future cash flow value at $125.40 per share, which frames the current $36.33 price as significantly below that model-derived value. This raises a key question: is it more useful to focus on a cautious valuation target or on a cash flow model that suggests a higher intrinsic value?
The strength of any DCF model depends on the assumptions that go into it, so it can be helpful to see exactly how the cash flows are projected and discounted over time. Look into how the SWS DCF model arrives at its fair value.
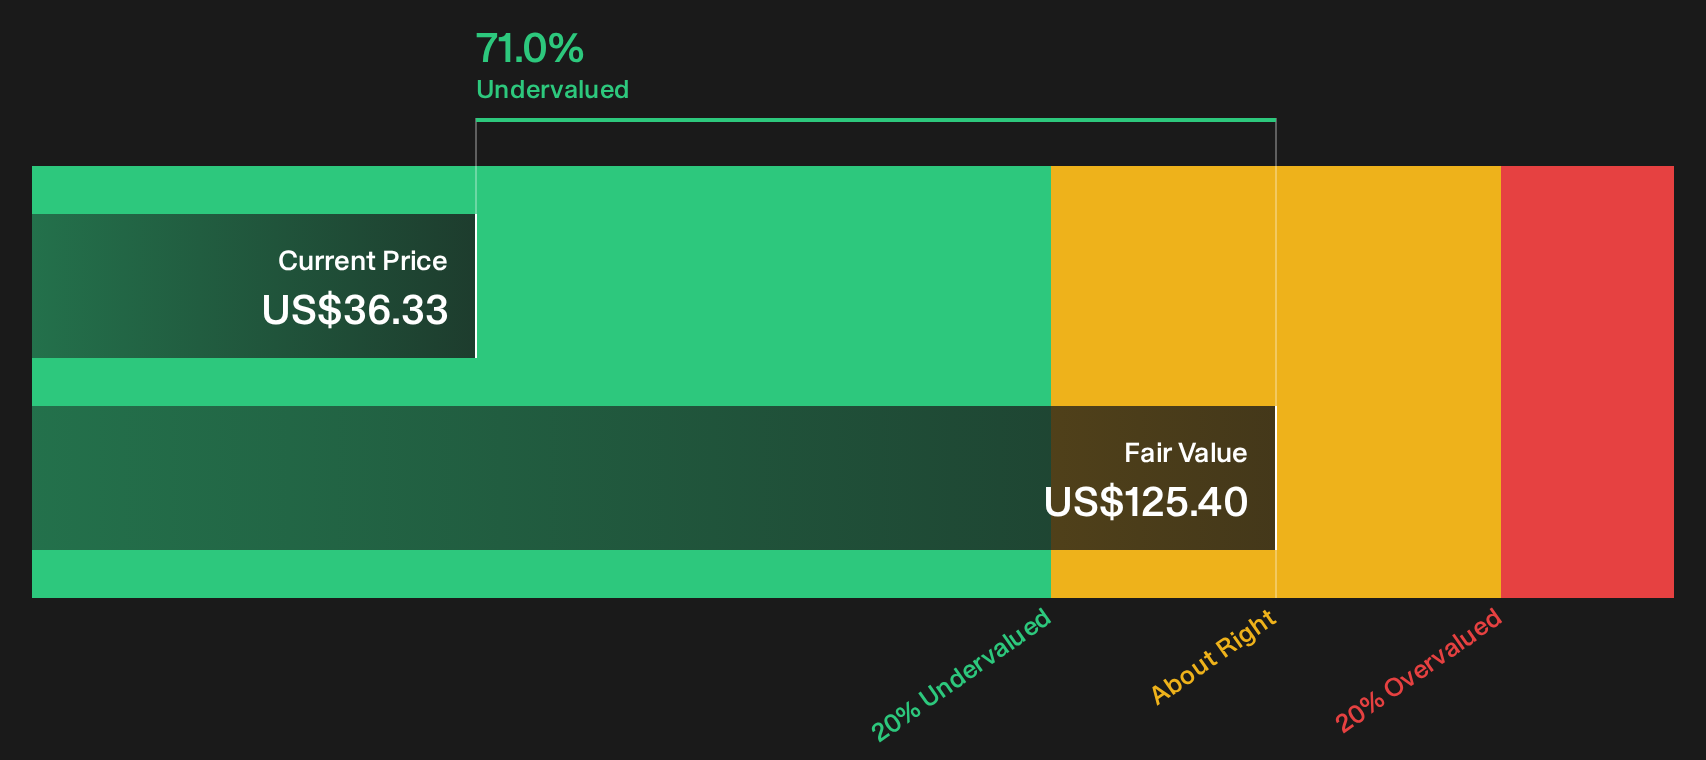
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pacira BioSciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Pacira BioSciences can make the story feel murky, so consider taking action while the facts are fresh and weigh the upside against the downside using 3 key rewards and 3 important warning signs.
Looking for more Pacira BioSciences sized opportunities?
Do not stop with Pacira BioSciences. Use the Simply Wall Street Screener to hunt for fresh ideas before other investors start paying closer attention.
- Target stronger pricing power with consistent income streams by reviewing income candidates in the 8 dividend fortresses.
- Hunt for quality at a discount by focusing on companies highlighted in the 33 high quality undervalued stocks.
- Prioritise resilience over excitement by scanning financially resilient candidates in the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com