
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CoreCivic (CXW) Dropped, So What Is Driving Attention Now?
CoreCivic (CXW) drew fresh attention after its latest quarterly update, where revenue and earnings exceeded analyst expectations and the business reported the fastest growth rate among safety and security peers.
That earnings surprise has arrived after a choppy stretch for CoreCivic’s share price, with the stock down 4.1% over the last day and 11.7% over the past month, but still showing a 64.2% year to date share price return and a 1 year total shareholder return of 76%. Taken together, these figures point to strong longer term momentum despite the recent pullback.
Scan other safety and security plays showing similar momentum by reviewing the hand picked 32 resilient stocks with low risk scores alongside CoreCivic after this earnings surprise.
The sharp pullback after CoreCivic’s earnings driven jump raises a simple question. Are you watching a reset in sentiment, or is the market second guessing how much of that business strength is already in the price?
Most Popular Narrative: 25% Undervalued
CoreCivic last closed at $31.23, while the most followed narrative anchors fair value at $41.80 using a 7.47% discount rate and a detailed earnings path. That gap frames the current pullback as a valuation debate rather than just a sentiment swing.
The combination of roughly US$1b of expected cash, reduced debt of about US$739.1 million, sizeable revolver capacity and a remaining US$755.8 million buyback authorization gives CoreCivic room to deploy capital into further share repurchases. This can lift future EPS even if operating income trends remain steady.
See why 15 investors see CoreCivic as 25% undervalued.
Result: Fair Value of $41.80 (UNDERVALUED)
Still, a sharp reversal in immigration detention policy or renewed scrutiny on federal contracts could quickly challenge the CoreCivic narrative that hinges on ICE-driven demand.
Find out about the key risks to this CoreCivic narrative.
Another View On CoreCivic’s Valuation
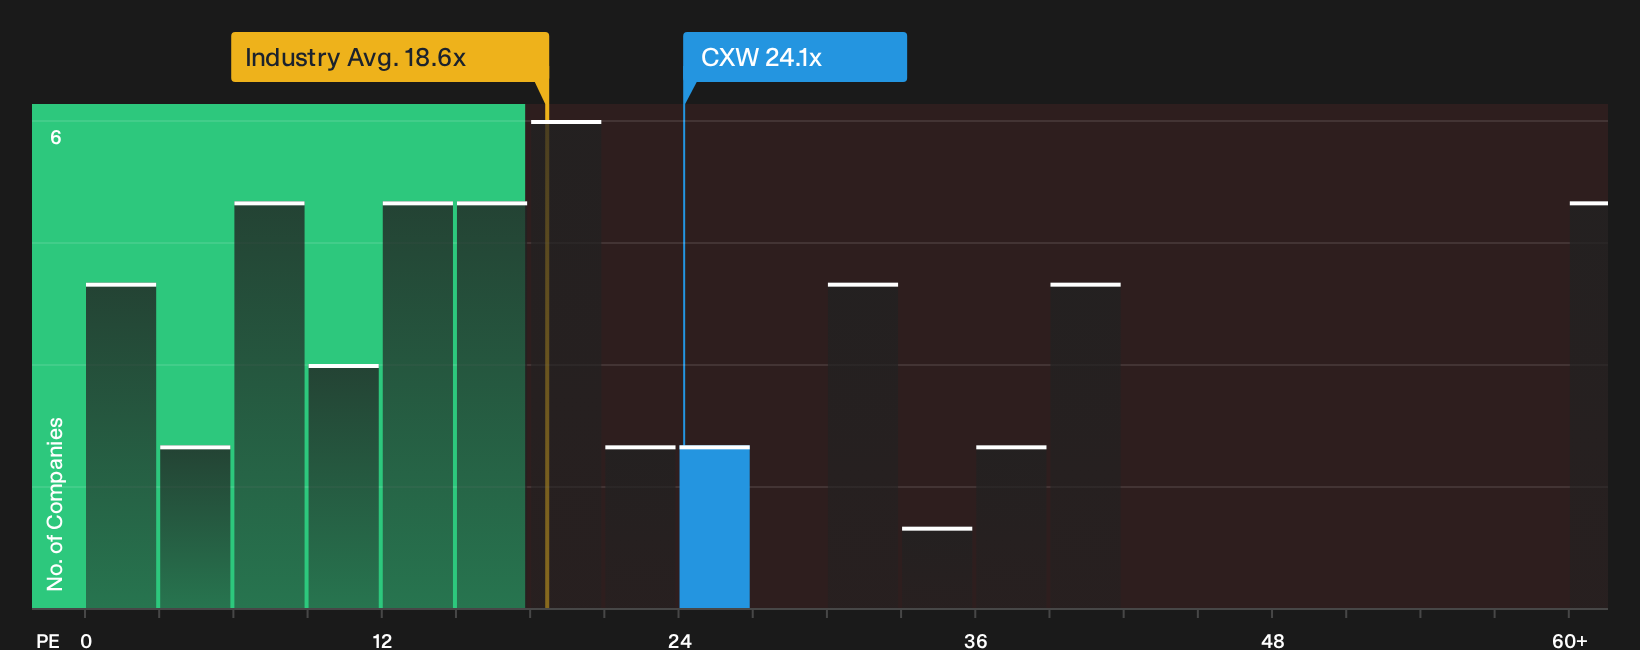
That 25% undervalued narrative leans on earnings forecasts and a fair value of $41.80. A simple P/E check tells a very different story. CoreCivic trades on roughly 24.1x earnings, while the fair ratio sits nearer 7.8x, and the US Commercial Services group clusters around 18.7x.
This places the stock at a premium to both peers and that fair ratio. That raises a practical question for you: Is the higher multiple a sign of confidence in CoreCivic’s contract mix and cash generation, or is it extra valuation risk if expectations slip?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on CoreCivic after all this, or leaning firmly one way? Move fast, check the data, and weigh the 2 key rewards and 3 important warning signs.
Looking for more CoreCivic sized opportunities?
If CoreCivic has sharpened your focus on valuation and momentum, do not stop here. Broaden your watchlist now or you risk missing the next move.
- Target stronger value by scanning companies screened for quality at a reasonable price with the 33 high quality undervalued stocks.
- Build a sturdier portfolio by focusing on balance sheets that look resilient using the list of solid balance sheet and fundamentals (25 results).
- Pursue underfollowed ideas by zeroing in on the 20 high quality undiscovered gems that many investors are not watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com