
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For MGM Resorts International Stock Could Change Following New Las Vegas Restaurant Opening
- MGM Resorts International is adding The Corner Store to The Cosmopolitan of Las Vegas, bringing the New York SoHo restaurant concept to the resort’s third floor with a multi-room bar, dining space and private room that extends its collaboration with Catch Hospitality Group.
- The expansion highlights MGM Resorts International’s focus on differentiated dining experiences that can support guest traffic, length of stay and higher food and beverage spend across The Cosmopolitan’s existing footprint.
- The next step is to consider how MGM Resorts International’s broader investment narrative may be influenced by this higher-end, experience-driven dining addition.
Explore other experience-led operators in the hospitality sector that may be showing trends similar to MGM Resorts International with our curated list of 20 high quality undiscovered gems.
What Is MGM Resorts International's Investment Narrative?
MGM Resorts International asks you to buy into a simple idea. Premium experiences can keep guests on property longer and support steady cash generation from rooms, gaming, dining and entertainment. The Corner Store opening at The Cosmopolitan fits that script. It is an experience-heavy, high check size concept that leans into existing foot traffic rather than requiring a new resort build, which keeps capital needs more contained than a ground up project.
In the short term, this restaurant is unlikely to move US$7.3b of market cap on its own, especially with the share price down 24.8% over 30 days and 36.1% over 90 days. The more important questions stay around MGM Resorts International’s leverage, one off items that affected recent earnings, modest forecast revenue and profit growth, and whether management can keep pricing power while servicing higher risk funding.
Even so, there is a less comfortable angle that sits behind all of this guest experience optimism and it starts with ...
There's only one way to know the right time to buy, sell or hold MGM Resorts International. Head to Simply Wall St's company report for the latest analysis of MGM Resorts International's Fair Value.
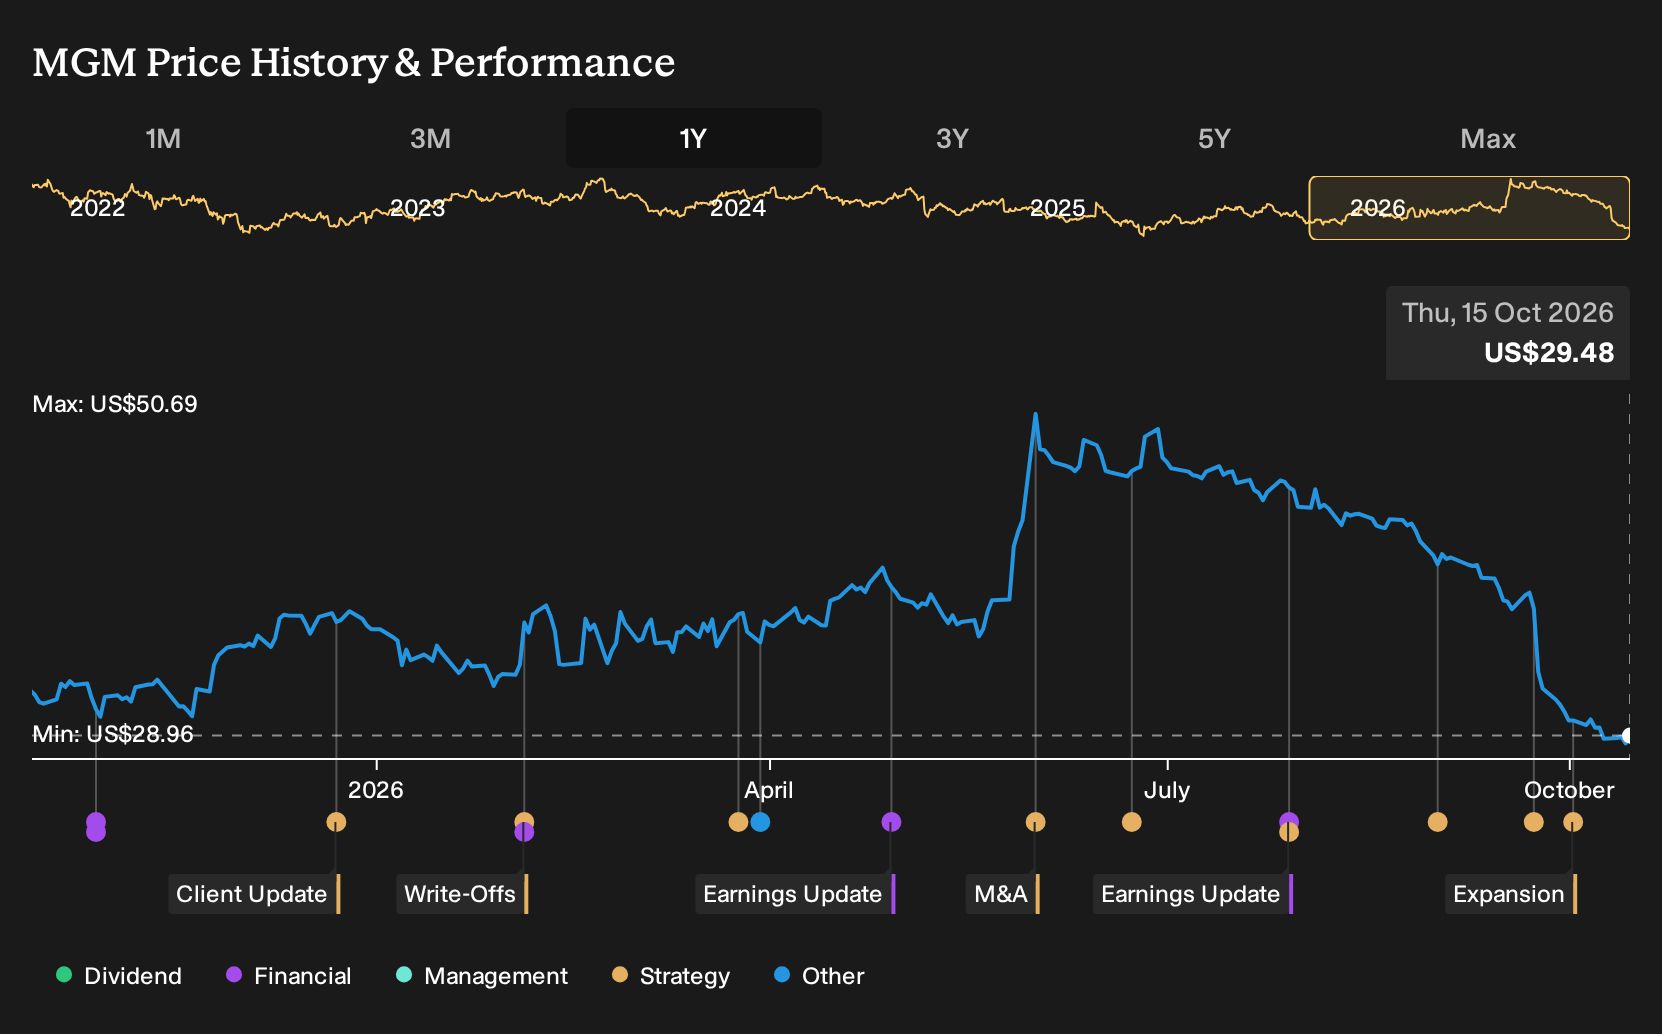
Exploring Other Perspectives
Here is a very different angle to weigh. The most bearish analysts think MGM Resorts International struggles to turn premium concepts like The Corner Store into meaningfully stronger profitability while self insurance and legal costs stay heavy. They were assuming revenue of about US$17.9b and earnings of US$541.5m by 2029 before this news, which is far more cautious than the higher analyst earnings view of US$710.1m. That gap shows how wide opinions already were before the Las Vegas opening, so treat this restaurant as one more reason to explore both optimistic and pessimistic cases for yourself.
Explore 6 other MGM Resorts International fair value estimates, including one that suggests up to 5% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MGM Resorts International research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MGM Resorts International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MGM Resorts International's overall financial health at a glance.
Looking For More Investment Ideas Beyond MGM Resorts International?
If the MGM Resorts International story has you thinking about where else experience, balance sheet strength and income potential might matter, use this as a springboard to widen your watchlist with screeners tailored to different goals.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching its finances.
- If consistent income is a priority, use our tool focused on 8 dividend fortresses to see which businesses currently offer higher yields with staying power in mind.
- For those who like to search off the beaten path, hunt through a 20 high quality undiscovered gems that may not be widely followed yet still show strong underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com