
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Disney Could Buy Character.ai. What That Means for DIS Stock.
Artificial intelligence (AI) companion app operator Character.ai has filed for Chapter 11 bankruptcy protection after finding its platform costly to develop and grow. Character.ai’s platform was known for direct conversations with AI characters. Entertainment industry giant The Walt Disney Company (DIS) has emerged as a stalking horse bidder to license certain intellectual property from the company for $20 million and provide transition support through former employees hired by Disney.
Character.ai has been plagued with litigation costs, with several lawsuits related to its chatbot safety. Earlier, Disney had also sent a cease-and-desist letter to Character.ai, warning that the company should stop using copyrighted characters without authorization. Now, as Disney has become a bidder, it has an opportunity to incorporate conversational AI technology that supports interactive characters into its experiences. Strategically, this could provide low-cost access to AI talent and potential product ideas.
Let's take a closer look at Disney as it gears up for a potential acquisition.
About Disney Stock
The Walt Disney Company, headquartered in Burbank, California, is a global entertainment and media enterprise operating through Disney Entertainment, ESPN, and Disney Experiences. It is currently expanding streaming through Disney+ and Hulu integration, advancing ESPN’s direct-to-consumer strategy, and investing in theme parks, resorts, and cruise ships. Disney is also developing new attractions while expanding Disney Cruise Line capacity. The company has a market capitalization of $188.19 billion.
Disney's stock is up just 1.5% over the past 52 weeks as investors weigh its strong parks and cruise business against persistent pressure in traditional television and uneven confidence in streaming profitability. However, it has jumped 7.3% over the past six months. DIS stock reached a 52-week low of $92.18 on March 27, but is up 21% from that level.
Although volatility has capped Disney’s gains, its valuation still surpasses that of its peers. Its forward-adjusted price-to-earnings (non-GAAP) of 15.74x is higher than the industry average of 12.52x.
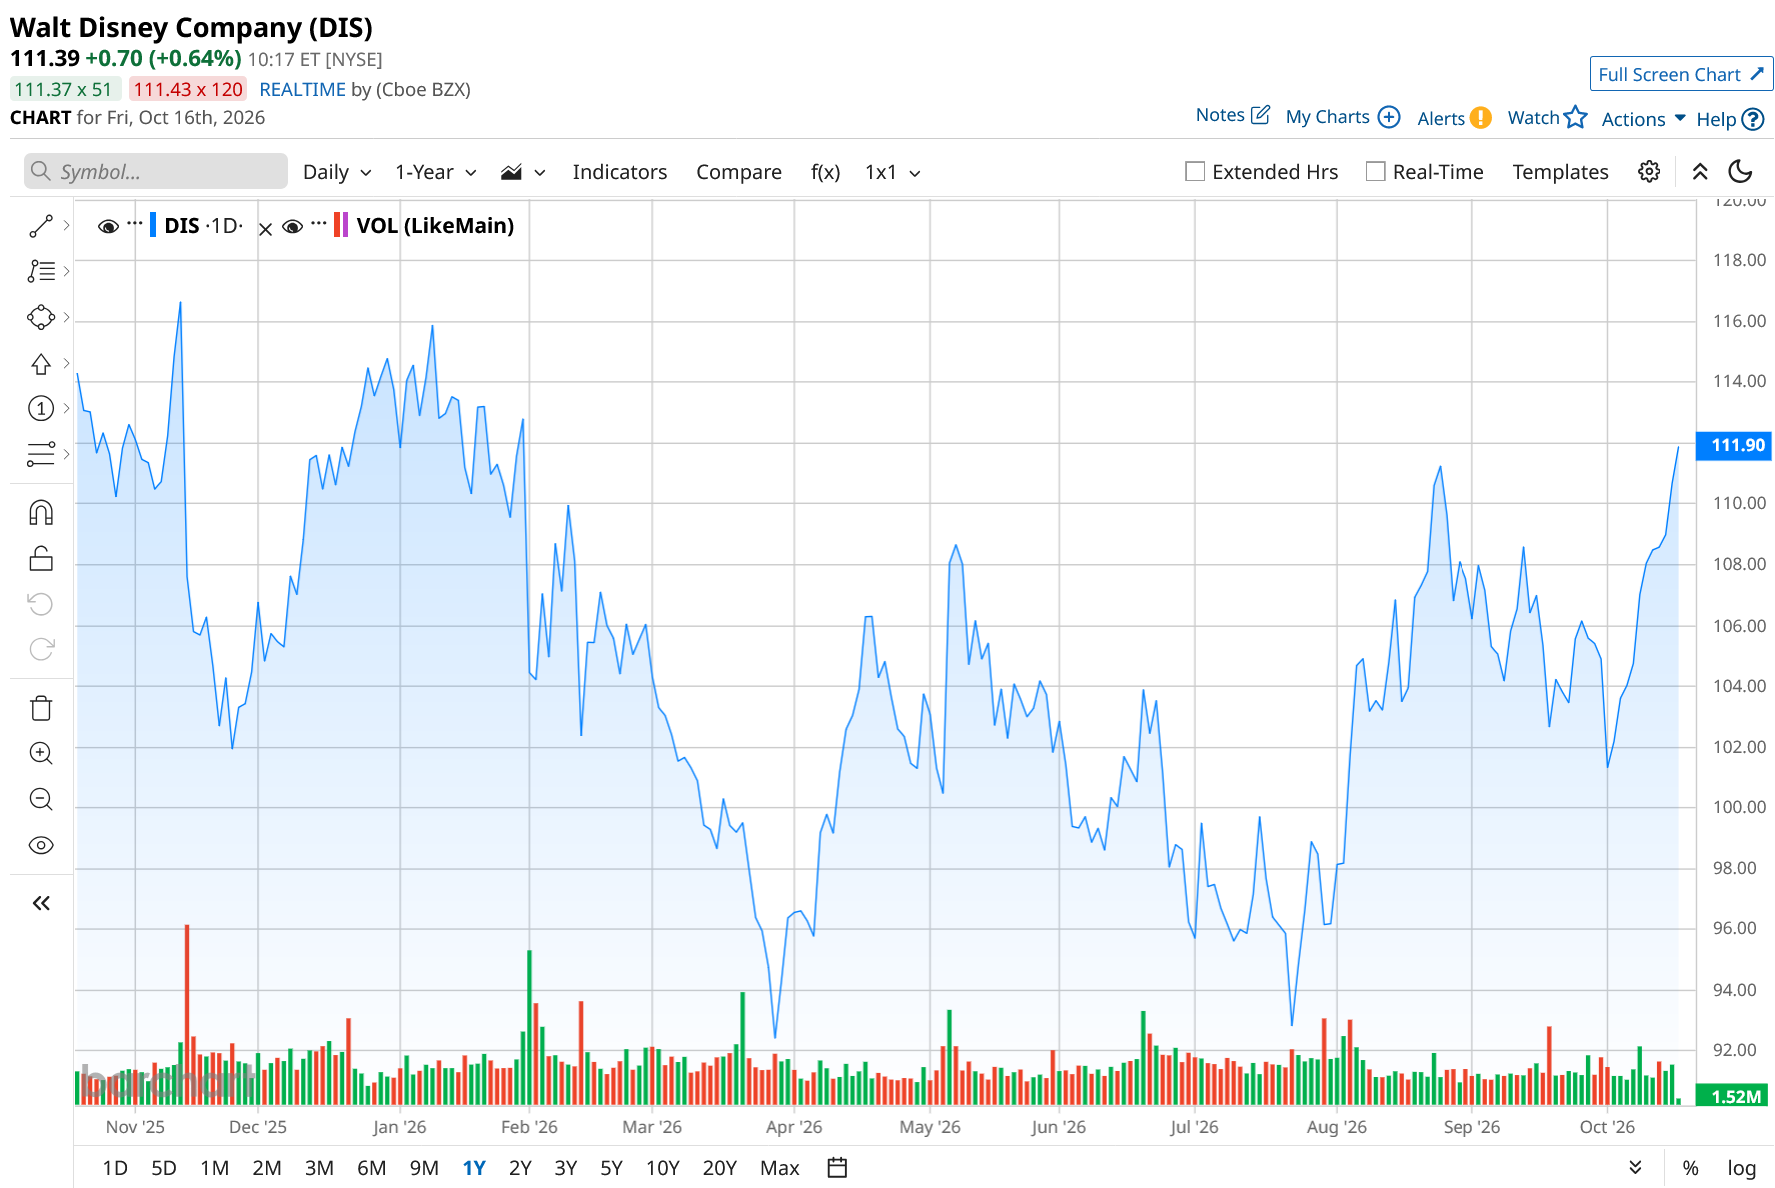
Q3 Earnings Rise as Parks Revenue Increases
For the third quarter of fiscal 2026 (quarter ended June 27), Disney’s revenues increased 7% year-over-year (YoY) to $25.25 billion. This was led by 11% revenue growth in domestic parks and experiences, including the expanding Disney Cruise Line portfolio. Total experiences revenue increased 10% YoY to $9.97 billion, driven by roughly 6% volume and 3% rate across the global portfolio.
The company maintains a leadership position in both the physical and digital worlds. Disney is also aggressively investing in its IP, which is paying back in box-office collections, direct-to-consumer avenues through Disney+, and ESPN-related operations. This is also increasing Disney’s profits. The company’s total segment operating income rose 21% from the prior-year period to $5.56 billion. Excluding certain items, Disney’s EPS increased 28% YoY to $2.06. Its free cash flow for the quarter was $3.07 billion, up 63% YoY.
For fiscal 2026, Disney expects adjusted EPS growth of approximately 12%, excluding the impact of the 53rd week. Wall Street analysts are also optimistic about Disney’s bottom-line trajectory. For fiscal 2026, its profit is expected to jump 16.7% YoY to $6.92, followed by an 8% growth to $7.47 in fiscal 2027.
How Do Analysts View DIS Stock?
This month, analysts at Needham reiterated a “Buy” rating and set a $125 price target on DIS stock. The firm’s analysts highlighted Disney’s rising streaming revenue and the boost to capacity and premium pricing from its newly launched cruise ships.
Raymond James analysts reiterated an “Outperform” rating on the stock while lowering the price target from $120 to $119. The firm’s analysts expect some softness in Asia parks. Moreover, Raymond James now assumes a slower ramp in direct-to-consumer margins but faster short- to mid-term revenue growth.
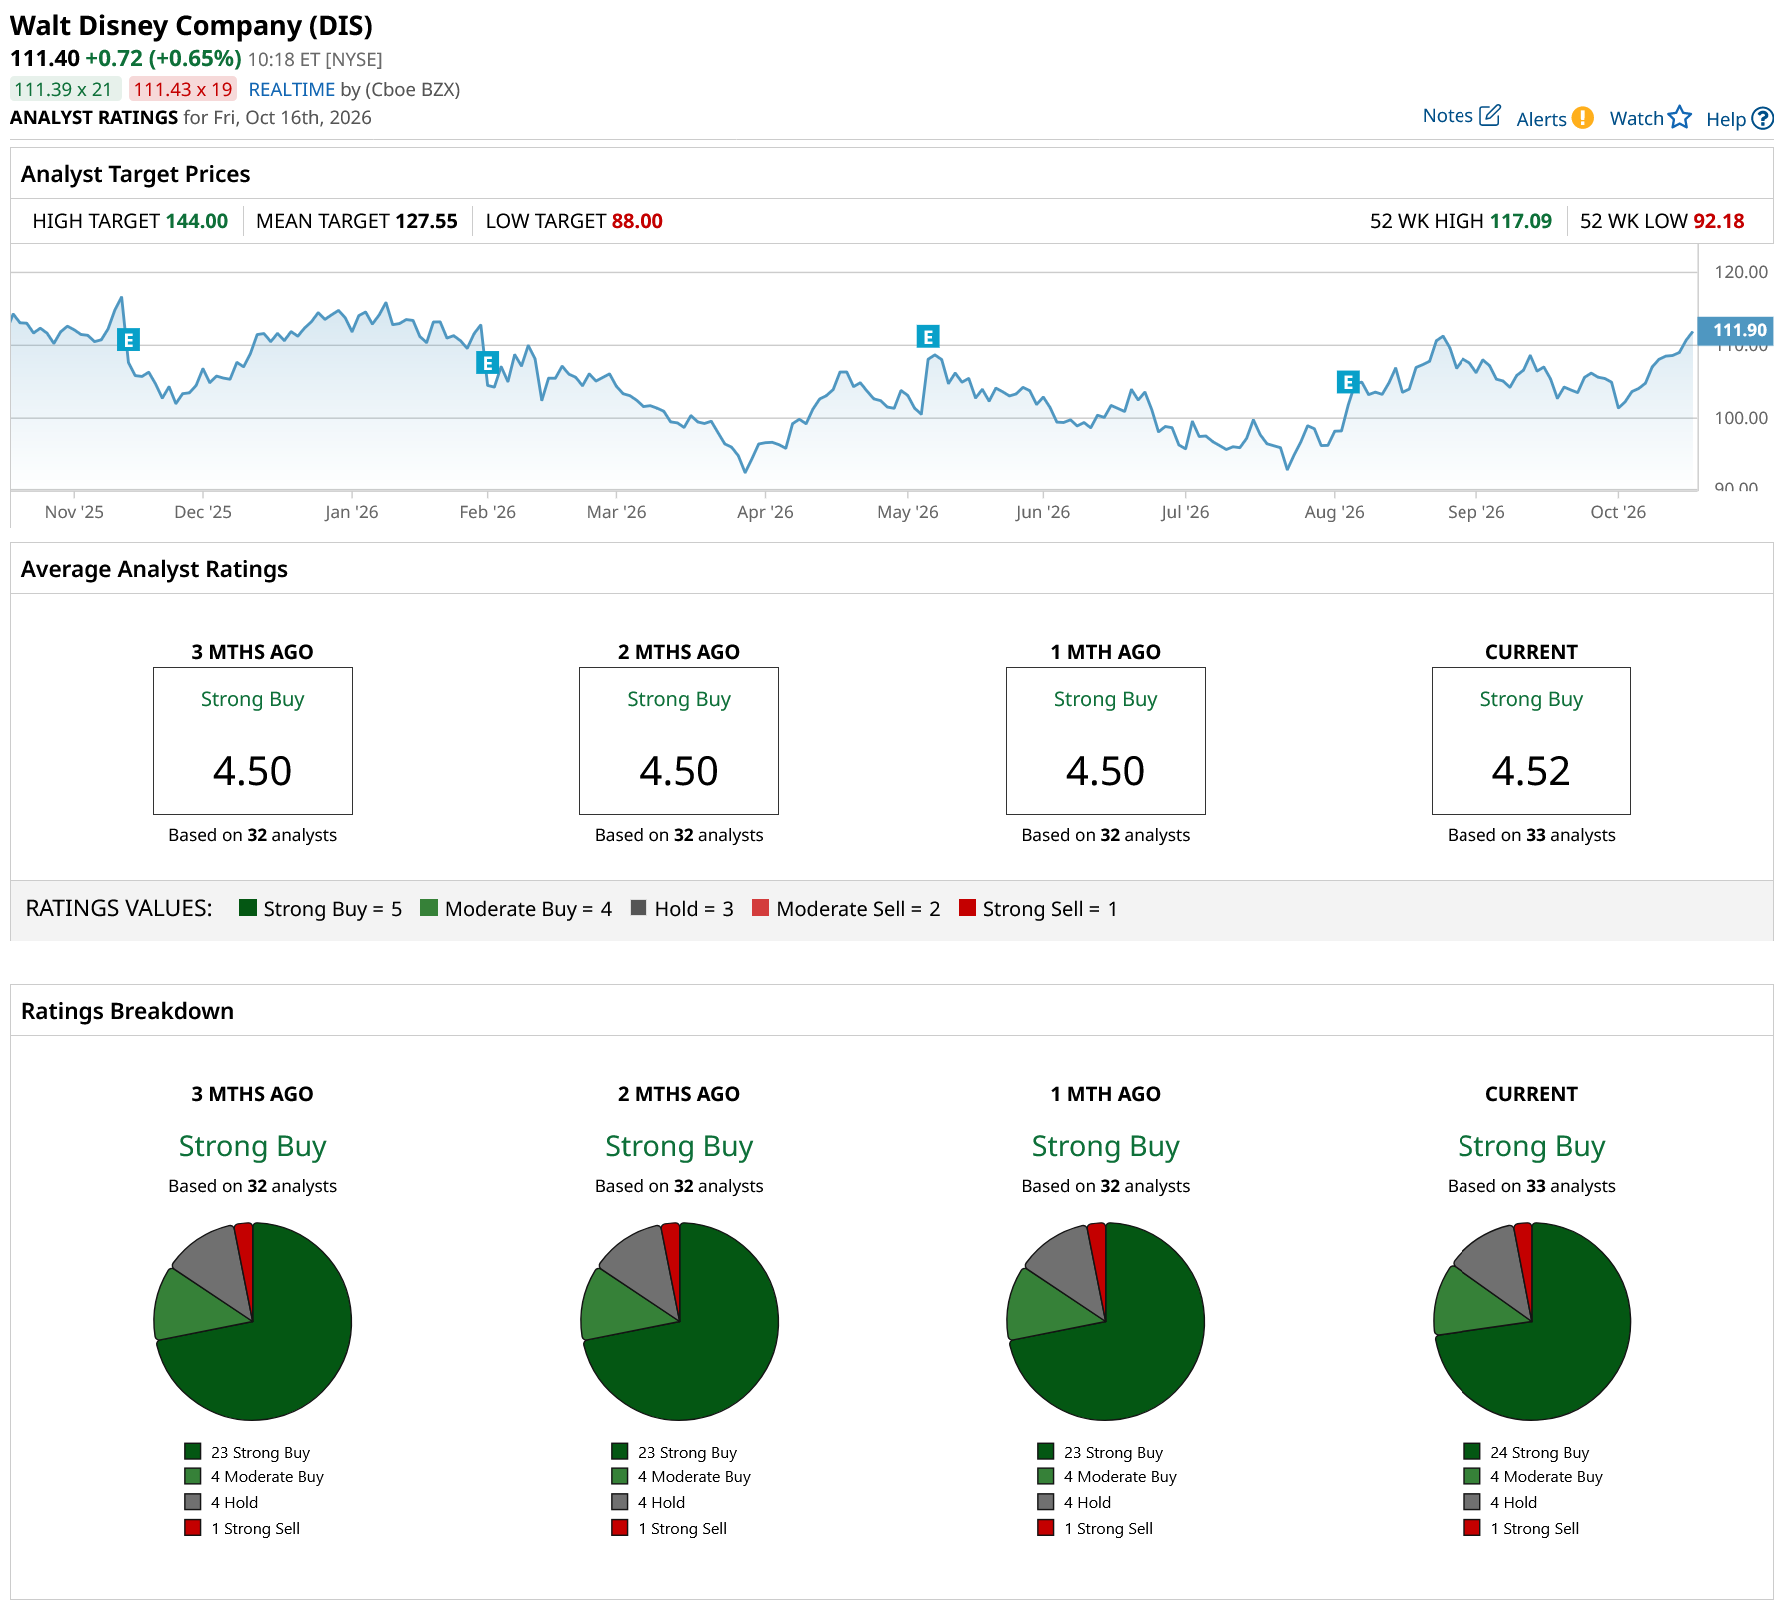
Disney has been in the spotlight on Wall Street for a long time, with analysts awarding it a consensus “Strong Buy” rating overall. Of the 33 analysts rating DIS stock, a majority of 24 analysts have given it a “Strong Buy” rating, four analysts suggest “Moderate Buy,” while four analysts are playing it safe with a “Hold” rating, and one analyst gave a “Strong Sell” rating. The consensus price target of $127.55 represents 15% upside from current levels. The Street-high price target of $144 indicates a 29% upside.
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.