
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Qualys Doubters Missed
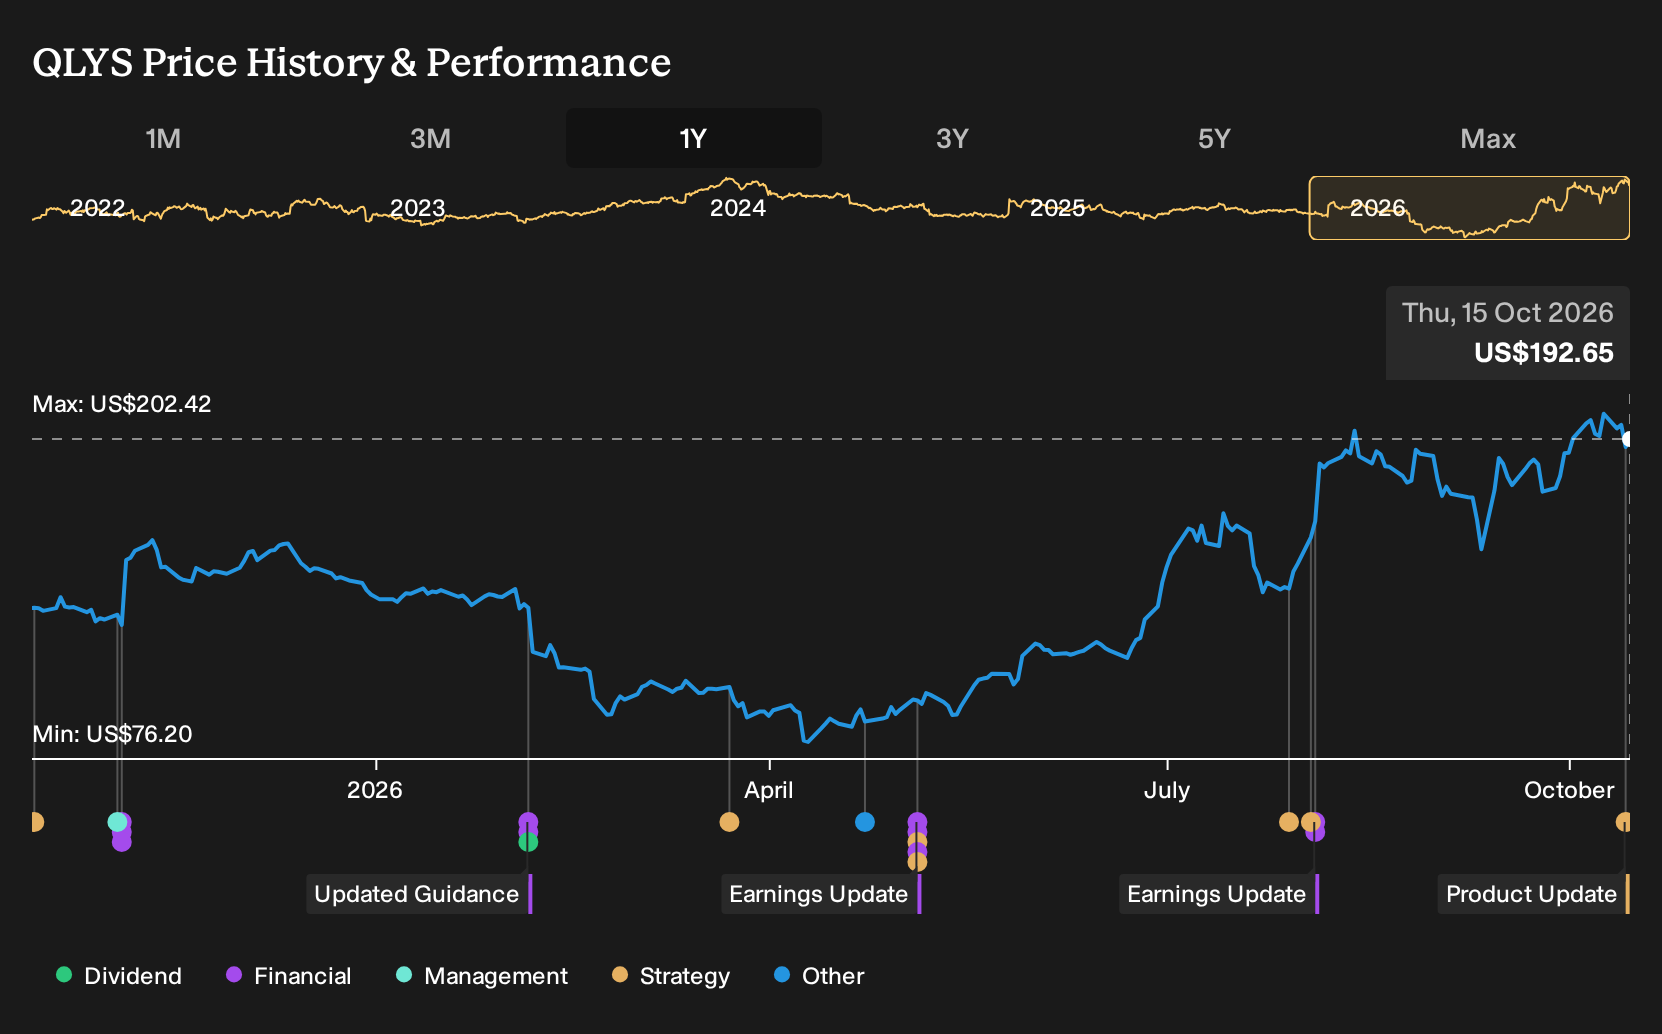
If you only read the headlines about Qualys wrestling with slower billings and fresh AI competition at the start of this period, a smooth ride was not the obvious outcome. Holding Qualys over the past year would have returned 51.0%, including dividends. If you had bought on 15 October 2025, with analysts split between AI fuelled upside and cloud giants squeezing third party security, what exactly did that payoff say about which risk story mattered most?
This theme extends beyond Qualys. See which of 55 AI infrastructure stocks may still merit a closer look.
The Two Qualys Stories Investors Had To Weigh
The shares cost US$128 at the start of the period, which left you choosing between two very different Qualys stories.
On the upbeat side, the Enterprise TruRisk and TotalAI thesis pointed to a Fair Value of US$173, a price implied by assumptions about future delivery. That view leaned on revenue growth of 8.3% a year and a future P/E of 40.0x.
The sceptical view argued that hyperscale cloud security could cap demand, with a Fair Value of US$94.5 based on slower adoption and margin pressure. This narrative leaned on a lower assumed P/E of 24.8x and pressure from bundled cloud tools.
What The Qualys Evidence Actually Tested
Qualys rolled out new AI led products such as TruRisk Eliminate 2.0 and expanded TotalAI and TotalCloud, which backed the bullish view that Enterprise TruRisk and AI security could matter. Revenue reached US$182.2 million in Q2 2026 versus US$164.1 million a year earlier and profit also rose, so the evidence leaned toward the optimistic case rather than the cautious cloud squeeze.
The useful takeaway is simple. When a story hinges on new platforms pulling their weight, treat product launches and segment guidance as key evidence and compare them directly with actual revenue and earnings in later reports.
What Qualys Buyers Are Assuming Today
Qualys now trades at US$193. The selected Narrative sees its Fair Value below that level and argues that current billing trends and premium pricing leave little room if newer AI modules and partner-led sales underperform.
For today’s price to add up, a buyer has to believe Qualys converts AI-native risk operations and autonomous remediation into clearly stronger ARR and billings.
"The main thing that has to go right is that Qualys converts its AI-native Risk Operations Center, autonomous remediation at scale, and expanding partner-led channel into meaningfully higher ARR and billings growth than the roughly high single to low double digit rates currently seen."
One Narrative disagrees with today's price. → See where this Narrative says Qualys should trade
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 31% below our estimate - builds out branded and private label coconut drinks across retail, online and foodservice channels.
- Company 2 - 33% below our estimate - ships lidar units into large scale production programs as customers progress from pilots to deployment.
- Company 3 - 43% below our estimate - expands premium teahouse locations while growing a membership base that drives frequent repeat orders.
Those are three of them. See the full list of 33 companies trading below our fair value estimates →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com