
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Morningstar (MORN) AI Tool Launch
- Morningstar and its PitchBook subsidiary recently rolled out new AI driven tools, including Morningstar Direct AI and PitchBook AI, aimed at automating research, product design, and private market workflows for professional investors.
- The push to embed Morningstar data, ratings, and private market intelligence directly into agentic software and external AI assistants signals a deeper focus on turning its research assets into workflow tools that clients may integrate into daily decision making.
- We will look at how Morningstar's investment narrative is shaped by this push into agentic AI tools for public and private markets.
Scan how AI heavyweights like Morningstar are reshaping research workflows, then size up other potential beneficiaries in our curated list of 55 AI infrastructure stocks.
Morningstar Investment Narrative Recap
To own Morningstar, you need to believe its research, data, and index assets can keep turning into sticky, fee based tools across public and private markets. In the near term, a key swing factor is whether clients actually shift real workflows onto Direct AI and PitchBook AI, which could tighten usage around Morningstar’s platforms rather than generic AI tools.
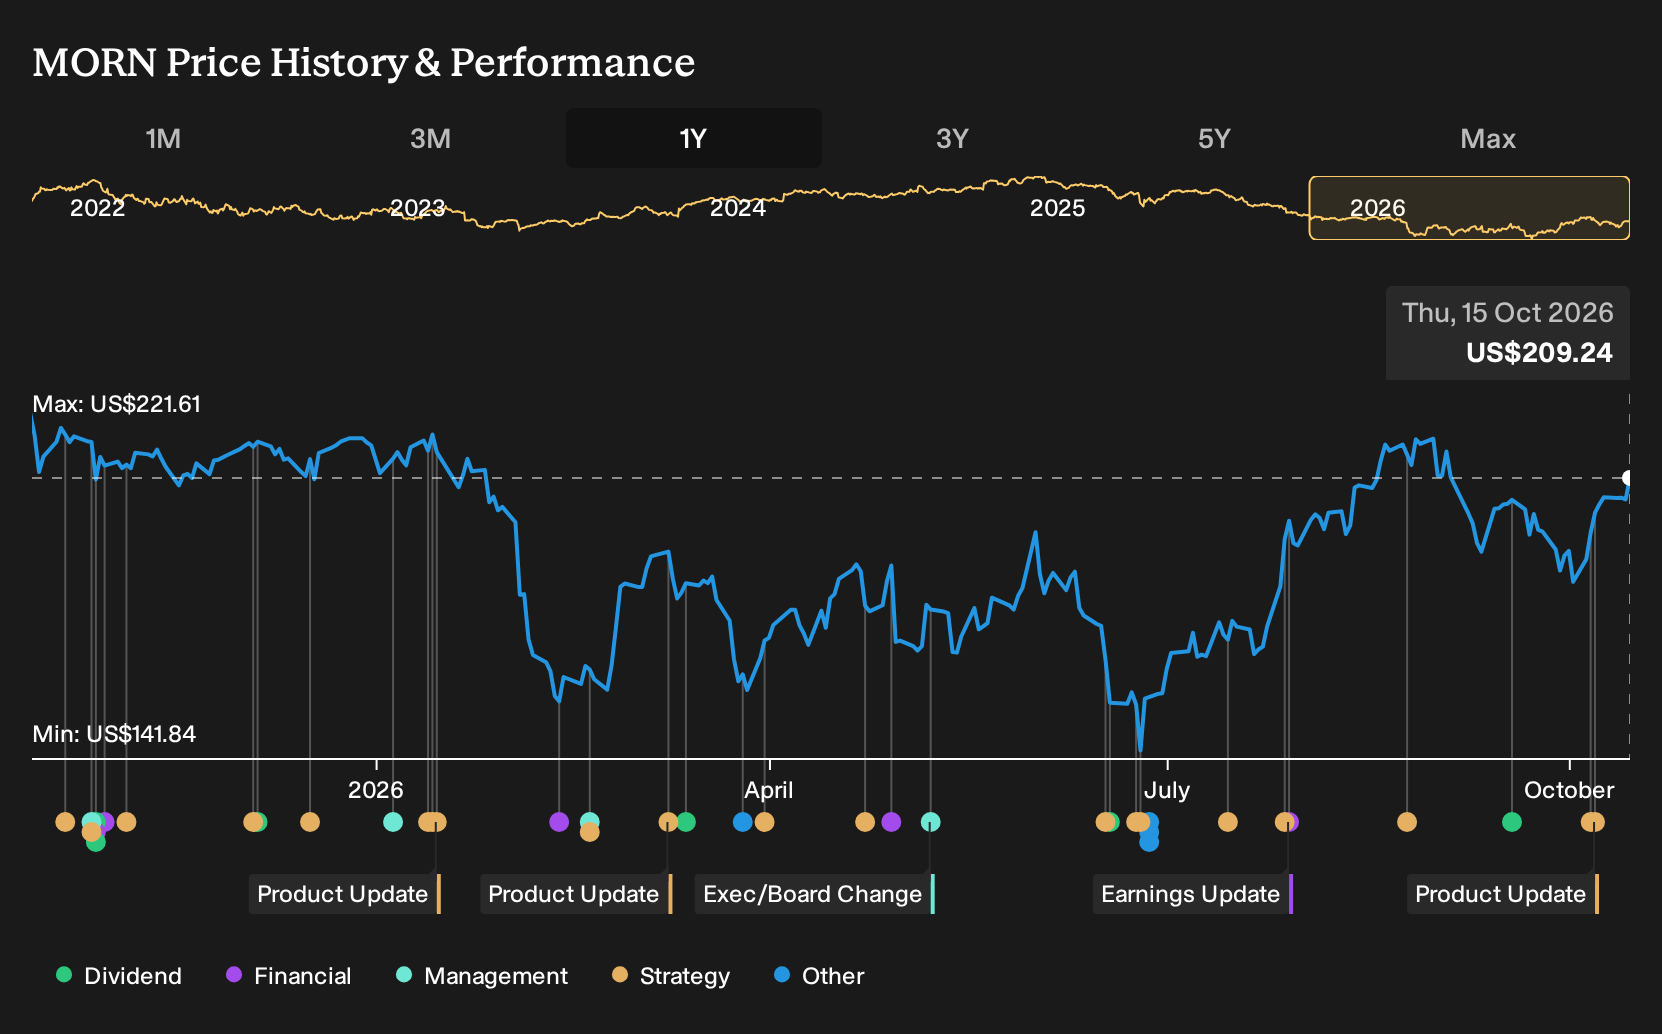
The biggest risk is that this AI push does not translate into broad adoption, which would cap any uplift in licensing and subscription revenue. High debt and a share price that has lagged the wider US market over 3 years keep execution risk in focus if these products stall.
Morningstar Direct AI sits at the center of this story. It bundles Product Development, Distribution, and Manager Research agents on a browser based interface, all grounded in Morningstar datasets and analyst frameworks. That directly connects to the existing catalyst around integrating content into AI assistants to drive higher revenue per user and better margins.
For investors, the operational question is simple: Do these agents, plus PitchBook AI, move customers from occasional research use to daily workflow reliance? If clients keep defaulting to third party tools, the upside around AI driven portfolio monitoring, model portfolio work, and index licensing looks harder to realize in the time frame analysts are modeling.
Morningstar's current analyst storyline points to forecast revenues of US$3.0b and projected earnings of US$534.0m by 2029. This outlook is built on assumed revenue growth of 5.6% a year and an earnings increase of about US$112.4m from US$421.6m today.
Uncover why Morningstar's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly US$163 to US$329, so some contributors see Morningstar as heavily discounted while others lean toward a richer appraisal. Those views pre date the Direct AI rollout and new Envestnet access. Consider both the AI tools and adoption risks, and weigh several contrasting opinions.
Explore 4 other Morningstar fair value estimates, including one that suggests as much as 22% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Morningstar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Morningstar. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Morningstar's overall financial health at a glance.
Looking for more investment ideas beyond Morningstar?
Once you have formed a view on Morningstar, it can help to widen the lens and compare it with other opportunities that fit your style, risk tolerance, and income needs. The Simply Wall St Screener lets you filter for specific traits so you can build a focused watchlist rather than a random collection of tickers.
- If you want to hunt for potential bargains with quality fundamentals, start by scanning a 33 high quality undervalued stocks that match your preferred metrics and see how they stack up against Morningstar on your dashboard.
- For readers who care most about capital strength and resilience, look through a list of solid balance sheet and fundamentals (25 results) to find businesses that keep leverage in check and maintain room to invest through different cycles.
- If your priority is finding names with fewer flagged risk factors, filter for a 32 resilient stocks with low risk scores and compare those with Morningstar to see which align best with your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com