
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What to Expect From Arista Networks’ Next Quarterly Earnings Report
Arista Networks, Inc. (ANET), headquartered in Santa Clara, California, develops, markets, and sells data-driven, client to cloud networking solutions for data center, campus, and routing environments. Valued at $234.1 billion by market cap, the leading tech company offers ethernet switches, pass-through cards, transceivers, and enhanced operating systems. It also provides host adapter solutions and networking services. The cloud networking giant is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Tuesday, Nov. 3.
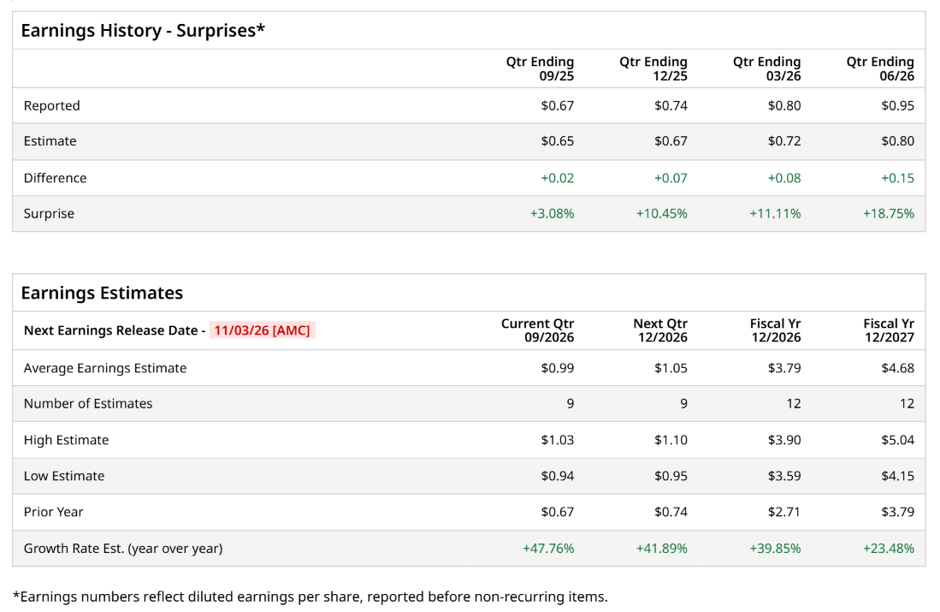
Ahead of the event, analysts expect Arista Networks to report a profit of $0.99 per share on a diluted basis, up 47.8% from $0.67 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Arista Networks to report EPS of $3.79, up 39.9% from $2.71 in fiscal 2025. Its EPS is expected to rise 23.5% year over year to $4.68 in fiscal 2027.
ANET stock has outperformed the S&P 500 Index’s ($SPX) 16.1% gains over the past 52 weeks, with shares up 24.2% during this period. However, it underperformed the State Street Technology Select Sector SPDR ETF’s (XLK) 31.4% rise over the same time frame.
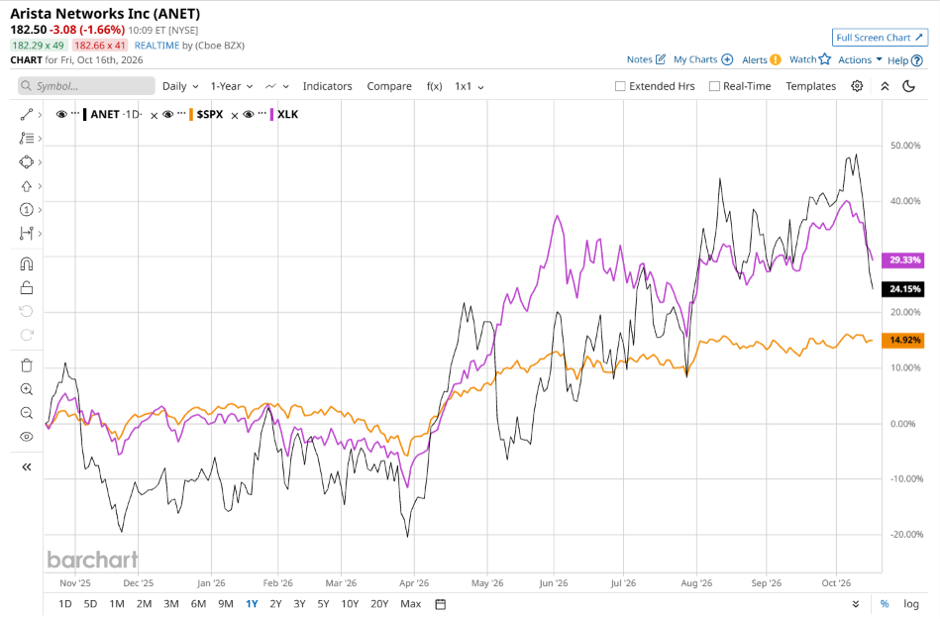
ANET's performance reflects a tension between its exceptional operational growth, fueled by robust hyperscaler demand and strong artificial intelligence networking adoption, and investor caution regarding its premium valuation. While the company has delivered record-breaking revenues and impressive earnings growth, short-term pullbacks and a mixed trajectory have been driven by high price multiples relative to historical averages, broader macroeconomic shifts leading to periodic tech sector rotations, and substantial pre-arranged insider stock sales.
Analysts’ consensus opinion on ANET stock is bullish, with a “Strong Buy” rating overall. Out of 27 analysts covering the stock, 23 advise a “Strong Buy” rating, three suggest a “Moderate Buy,” and one gives a “Hold.” ANET’s average analyst price target is $249.44, indicating a notable potential upside of 37.7% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.