
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Store Expansion Might Change The Case For Investing In La Z Boy Stock
- La-Z-Boy recently expanded its company-owned retail footprint across several U.S. states including Georgia, Florida, Tennessee, Mississippi, Massachusetts, Wisconsin, Colorado and Arizona, lifting the company-owned store count to a record 237 locations, which represents more than 62% of its total stores.
- This larger company-operated network gives La-Z-Boy more direct control over merchandising, pricing, customer experience and data. This structure can influence how efficiently the furniture maker turns showroom traffic and online interest into profitable sales.
- We will now look at how La-Z-Boy's record 237 company-owned stores could reshape the investment narrative built around its retail model.
La-Z-Boy Investment Narrative Recap
To own La-Z-Boy, you need to believe its shift toward more controlled, company-owned retail and a streamlined upholstery focus can offset current margin pressure. The expansion to 237 company-operated stores fits that idea, since a larger direct channel can concentrate merchandising, pricing and data around what actually sells.
The near term swing factor is whether those extra retail locations, along with distribution and portfolio changes, can ease friction costs that have kept adjusted operating margin at 3.9% and contributed to a recent GAAP operating loss. The biggest risk remains Joybird and weaker wholesale trends continuing to weigh on group profitability.
The most relevant backdrop for this store rollout is La-Z-Boy’s multiyear distribution and home delivery revamp. Management is consolidating 15 distribution centers into 3 hubs, with an expectation of cutting square footage by about 30% and delivery mileage by about 20%. That project targets a 50 to 75 basis point lift in wholesale margins once transition costs settle.
For investors, that means the retail expansion and distribution overhaul are tightly linked. A denser company-owned store network only fully pays off if product flows efficiently through those hubs and service levels stay consistent. Execution risk is a factor, because friction from these projects has already pressured earnings, while successful completion could support margin improvement across the broader business.
La-Z-Boy's narrative projects US$2.2b revenue and US$119.9m earnings by 2029, which implies 1.6% yearly revenue growth and an earnings increase of about US$38m from US$81.5m today.
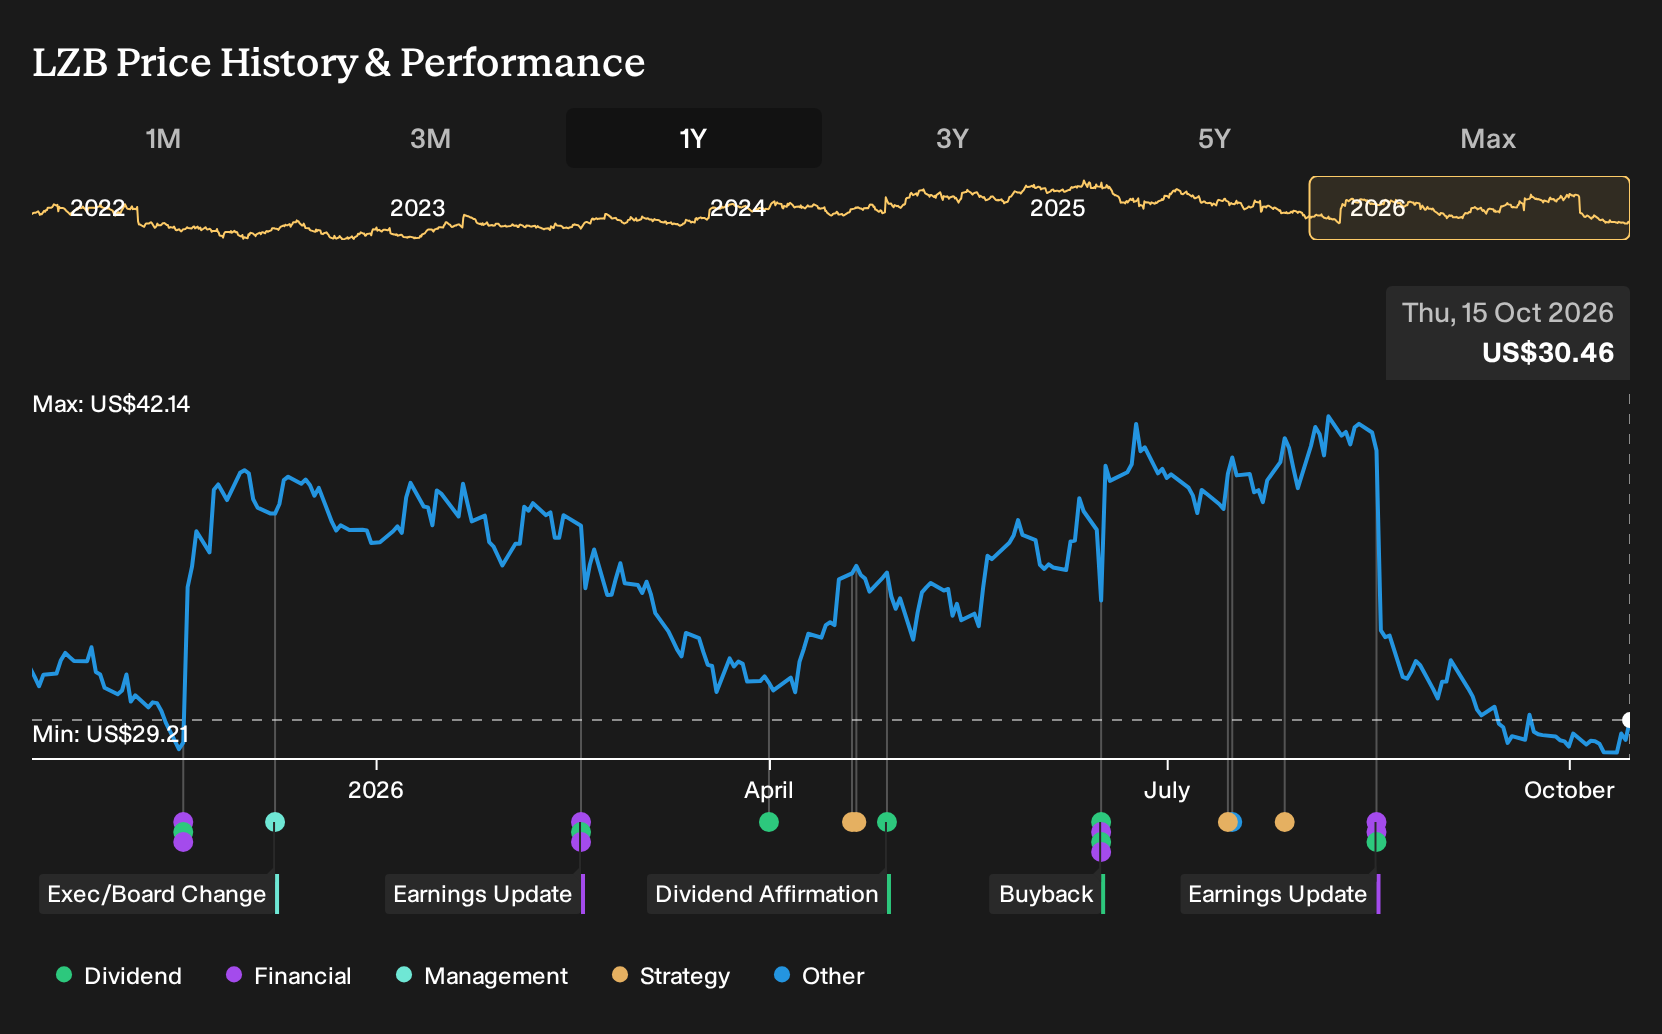
Discover why La-Z-Boy's fair value points to a 35% potential upside from its current price before this discount narrows.
Exploring Other Perspectives
Not every analyst sees La-Z-Boy's store buildout as a clear win. The most cautious group worries that a heavier brick and mortar focus could clash with rising e-commerce habits, so their earlier forecasts kept revenue around US$2.2b by 2029 but paired that with US$156.7m in earnings. Those estimates came before this expansion news, so opinions may change as more information becomes available, and it can be useful to review several viewpoints before deciding what makes sense for you.
Explore 3 other La-Z-Boy fair value estimates, including one that suggests it could be worth just $41.00!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your La-Z-Boy research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for La-Z-Boy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate La-Z-Boy's overall financial health at a glance.
Looking for more investment ideas beyond La-Z-Boy?
If La-Z-Boy has put the furniture and home category on your radar, it can be useful to compare it with other businesses that share similar strengths, like balance sheet resilience or attractive payouts. The Simply Wall St screener lets you quickly filter for the traits that matter most to you, so you can build a watchlist that matches your own risk and return preferences.
- For investors who want stability first, focus on companies with durable finances and steady fundamentals through our list of solid balance sheet and fundamentals (25 results).
- If you are hunting for overlooked potential, scan for quality businesses that the market has not fully priced in yet using the 20 high quality undiscovered gems.
- If income is your priority, seek out companies aiming to provide sizeable yields through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com